Quarter · Market review
90 days: supply and borrowing change business costs
Over 90 days, energy supply disruptions and trade decisions changed operating conditions for companies, while greater inflation risks pushed central-bank rates higher. Data released on 7 October showed an uneven rebound in German August production, while longer-maturity US yields rose. Faster reserve releases could ease some fuel expenses if pledged products reach their buyers.
Period covered: 2026-07-11 – 2026-10-08Information as of 21 min read
On 7 October, the Fed released its September minutes, Destatis showed an uneven German production rebound and the IEA clarified releases already pledged. Short- and long-maturity US yields moved in different directions.
The Fed target range remains 3.75–4.00%. September participants’ discussions are not a new decision, and reserve pledges will not reduce costs until the required fuel is delivered.
Quarter
What happened
The starting point: interest rates had already risen on 17 June
This rolling 90-day period begins on 11 July. Before it began, on 17 June, the European Central Bank’s previously announced interest rate increase took effect. The rate on banks’ overnight deposits rose from 2.00% to 2.25%. These are the initial conditions before the period under review, not a new event within it.
Also on 17 June, the Federal Reserve left the federal funds target range at 3.50–3.75%. It made no change on 29 July. Europe also chose a pause on 23 July. For a business with debt, this meant that energy costs would not be offset by automatically and rapidly falling interest rates.
The starting backdrop: the 18 June agreement had not yet restored shipping
On 18 June, the US announced the signing of a memorandum with Iran. For oil buyers, implementation mattered more: whether ships could sail safely, insurance would be available and oil would actually reach them.
More reliable deliveries would have reduced importing industries’ need to hold expensive inventories. Hauliers would have found fuel and route planning easier. But the agreement itself was not a statistical record of restored flows. July and August data later required a more cautious assessment of precisely this assumption.
July: the supply recovery was not sustained
Just before this period began, the International Energy Agency’s 10 July review described a partial recovery in June flows and ceasefire violations on 7–8 July. Its 12 August report said Persian Gulf oil exports in July, including routes bypassing the strait, averaged 15 million barrels per day. That was 2.1 million, or about 12%, below June.
This comparison describes two monthly averages, not a one-day shipping halt. It showed that June’s hopes had not been enough to deliver a lasting improvement. US military statements on 5 and 8 September about strikes on Iranian tankers were a reminder that delivery security remained unresolved. A particular price move cannot be attributed solely to these statements.
23 July: trade rules and sanctions added to the planning burden
The European Union’s 21st sanctions package against Russia expanded restrictions on energy, financial services and the shadow fleet. For companies, this matters beyond politics: payment, insurance and cargo transport options change. But an announced restriction is not a measured fall in exports of the same size.
On 23 July, the Office of the US Trade Representative announced tariff measures on imports from 60 economies, including the European Union. The action concerned insufficient bans on importing goods made with forced labour. Tariffs and exemptions depended on the product and its origin. US importers had to check whether ordered goods would become more expensive, while their overseas suppliers faced the risk that higher final prices would weaken demand.
Late July and August: technology suppliers earned revenue while customers invested
Technology suppliers’ revenue grew while their customers spent heavily on equipment and infrastructure. On 29 July, Microsoft reported capital expenditure, including finance leases, of 41 billion US dollars for the quarter ended 30 June. Cash purchases of property and equipment were 35.8 billion dollars. These amounts must not be added together: the first includes finance leases, while the second shows asset purchases paid for in cash during the quarter.
The company generated 55.4 billion dollars in operating cash flow. Subtracting cash purchases of property and equipment left 19.6 billion dollars. This explains why a rapid pace of construction is not automatically a bad signal: what matters is how much cash the business generates and how much more it needs from outside.
On 26 August, chip designer NVIDIA reported revenue of 96.221 billion dollars for the quarter ended 26 July, up 106% year on year. Operating profit grew 124%. Some customer spending had therefore already become real earnings for the supplier. For customers to earn a return on their investments, however, their new services need demand and must cover equipment, electricity and financing costs.
August and September: growth continued, but costs did not disappear
Both the US and euro-area economies grew in the second quarter. The third estimate of US gross domestic product, published on 30 September, showed annualised growth of 2.2%, or 0.6% quarter on quarter. The second US estimate released on 26 August had been lower. Euro-area growth was revised to 0.6% quarter on quarter on 7 September. On the same quarterly comparison basis, growth in the two regions matched.
The initial US estimate for August, released on 4 September, showed 162,000 additional jobs, but the gain was revised to 133,000 on 2 October. On 9 September, second-quarter revenue growth in selected US service industries was revised to 3.0% from the previous quarter. This revenue measure has not been adjusted for prices. Rising sales and a greater real volume of services delivered are therefore not the same thing.
9–11 September: a higher energy-price forecast was followed by an ECB rate increase
On 9 September, the US Energy Information Administration raised its second-half average Brent price forecast to about 90 dollars per barrel. Model inputs were finalised on 3 September. This is a conditional average for a future period, not the oil price in a particular September session and not an already measured effect of later military action.
On 10 September, the European Central Bank announced another interest rate increase of 0.25 percentage points. The deposit facility rate rose from 2.25% to 2.50% on 16 September. On 11 September, the US Consumer Price Index showed annual inflation of 3.4% in August, the same as in July. The seasonally adjusted monthly change accelerated from 0.1% to 0.4%. These data were known before the Federal Reserve meeting of 15–16 September, which subsequently raised the target range.
? How should we read GDP and price indices?
Gross domestic product measures the value of final goods and services produced in an economy. Real growth removes the effect of prices. US quarterly growth is often reported at an annualised rate, as if the same change continued for four quarters. The Consumer Price Index measures a basket of prices weighted by consumption. Its annual and monthly changes have different comparison bases. The Personal Consumption Expenditures Price Index also includes spending made on consumers’ behalf, uses different weights and accounts for changes in the composition of consumption; these two price indices should not be treated as interchangeable.
Mid-September: June’s hopes were not enough to restore supply
The International Energy Agency’s 11 September forecast projected a larger fall in oil supply than in demand this year. This is a forecast, not the final annual result.
Lower demand does not automatically mean cheaper oil. If the volume reaching buyers falls faster, fuel bills can remain high even as the economy slows. This can help an energy producer only if it can deliver its output. For a haulier or an energy-buying factory, the same situation raises costs.
16–24 September: US bond yields rose again after a brief decline
On 16 September the Federal Reserve raised its target range to 3.75–4.00%. An earlier European decision lifting the deposit rate to 2.50% took effect on the same day. The US ten-year yield fell to 4.96% on 21–22 September, but reached 5.18% on 24 September. The fall in US bond yields was therefore short-lived.
The preliminary S&P Global US PMI Composite Output Index, covering manufacturing and services activity, reached 58.4 in the release of 23 September, compared with 56.0 in August. Seasonally adjusted initial unemployment benefit claims of 197,000 for the week ending 19 September, released on 24 September, at that time added to the evidence that the economy was not weakening sharply. On 1 October, that week’s claims were revised to 198,000; the newer week ending 26 September recorded 197,000. Claims are not a count of jobs created or a final measure of an entire quarter’s growth.
? Purchasing Managers’ Index: what does the threshold mean?
The company survey compares activity with the previous month. Above 50 generally indicates expansion and below 50 contraction. A reading of 58.4 does not mean growth of 58.4%; the preliminary measure may be revised.
September’s decisions extended beyond the US and euro area. On 18 September the Bank of Japan set an overnight interest-rate target of 1.25%, effective from 24 September. On 17 September the Bank of England left Bank Rate at 3.75%. These different paths matter for Japanese bonds and yen-funded investments, as well as British companies’ borrowing costs.
25–28 September: uneven demand and trade relief not yet in force
US August durable-goods orders, reported on 25 September, reached $338.6 billion and were virtually unchanged from revised July. Orders for non-defence capital goods excluding aircraft nevertheless rose 1.6%, while shipments increased 0.6%. These are monthly changes adjusted for seasonality, but not for prices. On the same day, the University of Michigan’s final September consumer sentiment index stood at 48.1, compared with 51.7 in August. Business-equipment demand and households’ assessments were therefore sending different signals.
On 27 September, the White House published US and Chinese lists covering about $30 billion of imports in each direction, proposed for lower tariffs. The US list of imports from China includes plastic tableware and bedding; China’s list of imports from the US includes beef and dairy products. This publication did not bring tariff reductions into force. On 28 September, China reported that August profit at larger industrial enterprises was 4.2% higher than a year earlier; July’s growth was 11.2%. These are year-on-year comparisons; they do not show whether profit rose or fell from July to August. Companies’ profits would depend not only on lower tariffs, but also on selling more goods at profitable prices.
30 September: spending remained resilient while energy prices rose
Figures released by the US Bureau of Economic Analysis on 30 September showed real consumer spending rising 0.6% month on month in August, while real disposable income was unchanged. The Personal Consumption Expenditures Price Index, or PCE, was 3.4% higher year on year; excluding food and energy, the increase was 3.0%. July’s annual readings were identical in the same revised data series.
Germany’s preliminary national September inflation rate rose from 2.9% to 3.3%, with energy inflation increasing from 10.5% to 14.9%, while the rate excluding food and energy remained at 2.4%. France’s measure under the common European methodology rose from 2.6% to 3.4%. On the same day, China’s manufacturing Purchasing Managers’ Index rose from 49.8 to 50.1, but its new-orders index fell from 50.6 to 50.5 and the raw-material purchase-price index increased from 56.6 to 60.8. The different indices showed growing activity alongside uneven cost increases.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
30 September: memory-chip maker Micron reported higher revenue
US memory-chip maker Micron reported on 30 September that revenue for its fiscal quarter ended 3 September was $54.229 billion, compared with $11.315 billion a year earlier. This year’s quarter contained 14 weeks against 13 in the previous year, so the periods are not identical in length. The result added to the record of rising technology-supplier revenue. However, the value of the company’s shares depends on more than revenue already earned: it also matters how much future growth investors already expect.
1 October: orders held up while new borrowing cost more
The Institute for Supply Management’s September manufacturing survey, released on 1 October, put its Purchasing Managers’ Index at 54.5. Activity was still expanding, but the prices-paid index increased from 71.1 to 77.9. For a manufacturer, this means an opportunity to sell more without necessarily earning more if higher material costs cannot be passed on to customers.
On the same day, the European Central Bank reported that the euro-area new mortgage rate indicator rose to 3.60% in August, consumer credit rates to 7.92%, while the corporate borrowing cost indicator was almost unchanged at 3.77%. These are averages for new agreements, not changes in payments on existing Lithuanian loans. August statistics do not yet show the effects of the subsequent September rate increase.
Eurostat reported on 1 October that Lithuanian house transaction prices were 14.3% higher year on year in the second quarter, against 4.0% in the euro area. This April–June comparison describes prices, not rental income or net investment returns. A home buyer needs to consider both the purchase price and future mortgage payment, but later euro-area lending rates cannot be presented as the cause of earlier Lithuanian price growth.
2–4 October: US jobs growth slowed while energy risks persisted
On 2 October, the US Bureau of Labor Statistics reported that nonfarm payrolls rose by 29,000 in September, following a revised increase of 133,000 in August. The combined July and August result was revised down by 60,000. The weakness was not confined to the latest month: the earlier path of jobs growth was also lower than previously reported.
The September unemployment rate was 4.2%. Slower jobs growth can limit growth in household income and discretionary spending. These figures do not by themselves establish an economy-wide downturn, however.
? Unemployment rate: what is the denominator?
It is the share of the labour force who are not employed, are actively looking for work and are available to work, rather than a share of the whole population. Unemployment and payroll figures come from different surveys, so their monthly movements need not match.
Also on 2 October, Eurostat’s flash estimate showed euro area annual consumer inflation rising from 3.2% to 3.8% in September. These are prices paid by consumers, not the producer selling prices discussed below. On 4 October, seven countries in the OPEC+ group of oil producers retained September production targets for November; these are agreed volumes, not confirmed actual oil supply.
5–6 October releases: higher costs and uneven demand
On 5 October, the Nasdaq Composite share-price index rose 1.05% from its 2 October close, measured in US dollars. The US 10-year Treasury yield meanwhile increased from 5.28% to 5.31%. These are different market measures: rising share prices do not establish that companies can borrow more cheaply.
On 5 October, the US Institute for Supply Management’s September Services Purchasing Managers’ Index (ISM Services PMI) fell from 55.4 to 54.9, while its prices index increased from 72.6 to 74.0. Activity expanded more slowly but cost pressures became more widespread.
? Services and prices indices: what do they measure?
The services survey index gives equal weight to activity, new orders, employment and delivery times. A reading above 50 indicates prevailing expansion compared with the previous month. The separate prices index measures the breadth of price increases: 74 points does not mean 74% inflation.
On 6 October, Destatis reported that German manufacturing orders fell 10.6% in August from July, but only 0.1% excluding large contracts. The category covering ships, aircraft, trains and military vehicles had received unusually large orders in July. Even so, June–August orders excluding large contracts were 2.6% below the preceding three months, leaving regular demand weak.
? Manufacturing orders: how do they differ from revenue?
These are new orders adjusted for prices, seasonal effects and the calendar; August figures are preliminary. An order is not yet a finished product or collected revenue. The overall series and the population excluding large contracts are not additive components of the decline.
On 5 October, Eurostat reported that euro area industrial producer prices rose 1.9% in August from the previous month, with energy up 5.6% and industry excluding energy up 0.2%.
? Producer prices: what do they not show?
The Industrial Producer Price Index measures domestic selling prices, not a company’s entire input-cost basket or consumer inflation. August is compared with July; the energy group’s 5.6% rise is not its percentage-point contribution to the overall index.
Also on 5 October, ECB Executive Board member Philip Lane explained that costlier energy leaves households less money for other goods, while higher long-term interest rates constrain consumption and investment. This was his assessment, not a new interest-rate decision.
6 October retail data: the recovery remains small
On 6 October, Eurostat reported that euro area retail volumes rose 0.1% in August after declining 0.6% in July. Non-food volumes increased 0.5%, while fuel fell 1.9%. This was a small overall recovery with different product groups moving in different directions.
? Retail volume: how does it differ from revenue?
The volume measure removes price changes, and the monthly comparison is seasonally and calendar adjusted. It therefore describes changes in quantities sold, not retailers’ revenue or profit.
Fed minutes: most September participants envisaged another rate rise
On 7 October, the US central bank, the Federal Reserve (Fed), released the minutes of its 15–16 September meeting. Most participants had then considered another rate increase likely to be appropriate by the end of the year. This was not a new October decision: on 16 September, the target range had been raised by 0.25 percentage points to 3.75–4.00%.
September meeting participants did not yet have the jobs report released on 2 October. The assessment recorded in the minutes therefore cannot be treated as a response to that subsequent labour-market slowdown.
The September assessment was not only about expensive oil. Participants also discussed rapidly growing investment in artificial intelligence infrastructure: it supports orders but can increase the costs of materials, transport and other resources. The longer energy remains expensive, the greater the risk that cost increases in individual sectors will spread into broader inflation.
? Fed minutes: what do they show?
The minutes describe the information available and discussions held at the meeting, not an assessment of data published later. A majority view about a future increase is not a vote for that future decision; it will depend on new information.
US yields moved in different directions as the auction cleared at 5.30%
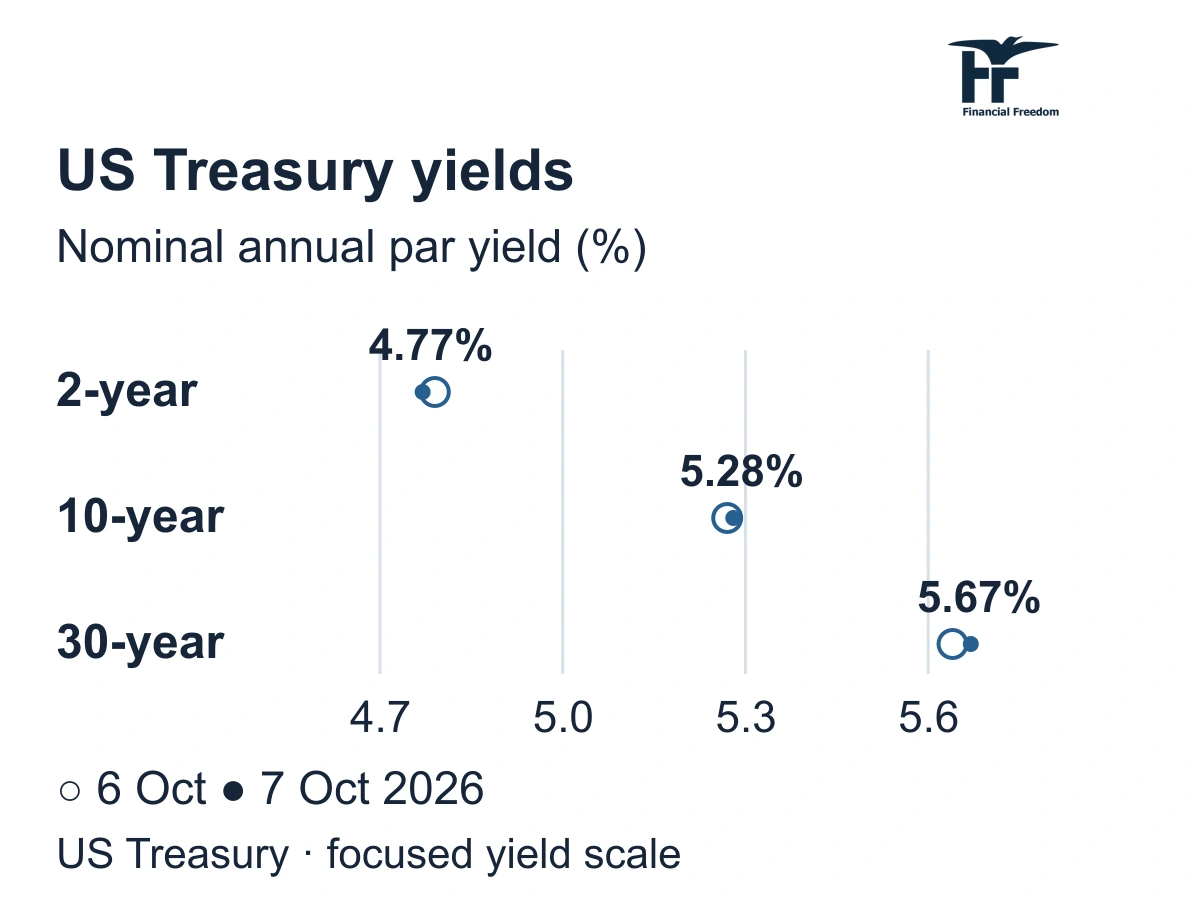
US Treasury yields did not move in one direction on 7 October. The annual two-year yield declined from 4.79% to 4.77%, but the 10-year yield rose from 5.27% to 5.28%, while the 30-year yield increased from 5.64% to 5.67%. Shorter-maturity bonds and longer-term borrowing costs presented different pictures that day.
On the same day, the US Treasury sold a further $39 billion of previously issued 10-year notes. The auction’s highest accepted annual yield was 5.30%, and the bid-to-cover ratio was 2.77. The auction shows the terms on which the government raised fresh money; it is not a return investors have already earned over a year.
? Bond yields and auctions: how should they be read?
Treasury daily yields are derived from indicative market quotations around 15:30 New York time; they are not averages of actual trades. The auction’s highest accepted yield is set at a different time and through a different process. The ratio of 2.77 compares public bids with the amount sold, not the number of unique buyers or future price direction.
German production rebounded, but construction and car factories moved in opposite directions
On 7 October, Germany’s statistical office Destatis reported that production rose 2.0% in August from July. Construction, which increased 9.3%, provided the main positive contribution. The headline therefore points more to an increase in construction work than to a uniform recovery across factories. More completed work can support sales of building materials and equipment, but the measure does not itself show suppliers’ profits.
Industry excluding energy and construction grew only 0.6% month on month. Machinery and equipment production rose 5.3%, while automotive production fell 5.4%. Destatis noted that factory holidays being more concentrated in August explained part of the automotive decline. Fewer cars produced do not therefore establish an equivalent decline in orders or sales.
The longer comparison remains modest: total production in June–August was just 0.4% above the preceding three months. July’s decline was revised to 1.2%. Production in energy-intensive branches fell another 0.5% in August. These differences matter for chemical and other materials producers: an increase in Germany’s overall output does not yet mean their sales are recovering.
? Production volume: what does the monthly change measure?
The measure removes price changes, and the monthly comparison is seasonally and calendar adjusted. August figures are provisional. The headline includes construction; it does not measure company revenue, profit or share returns.
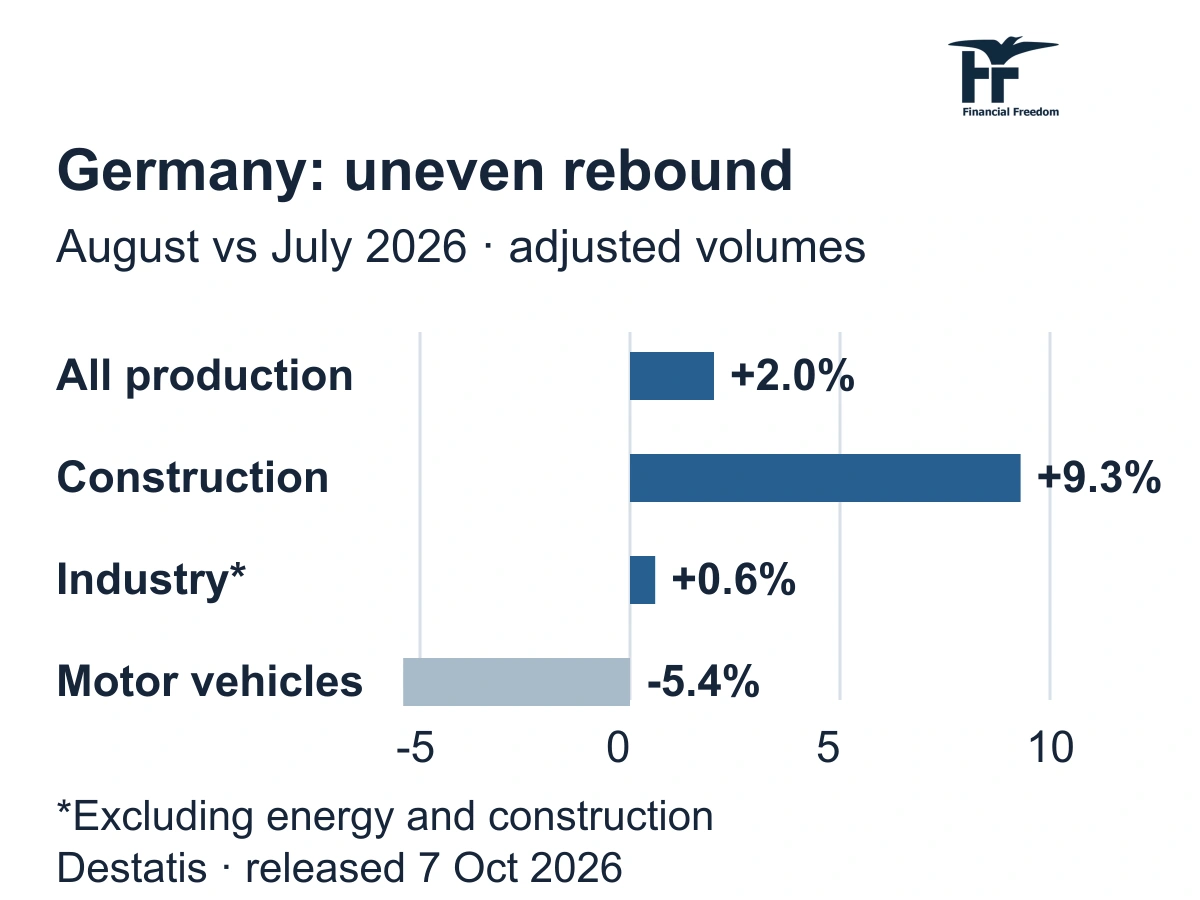
Orders and production cover the same August but measure different stages. Factories can fulfil earlier contracts even while new orders decline. The output rebound therefore does not itself contradict the weakness in new orders reported on 6 October.
Reserve commitments still need delivery, while the diesel stock shortage persists
On 6 October, the US Energy Information Administration raised its fourth-quarter average Brent oil price forecast from $91 to $105 a barrel. On 7 October, the International Energy Agency (IEA) said member governments support accelerating March reserve commitments and prioritising diesel where possible. Faster fulfilment is not confirmation of additional oil delivered.
About 325 million barrels have been released under the March collective action. The remaining pledges would bring approximately 100 million barrels to market. This remainder must not be counted as a separate new volume added to the earlier plan. The agency gave no precise delivery timetable. Actual cargoes and their product mix matter to fuel buyers, not just the announcement.
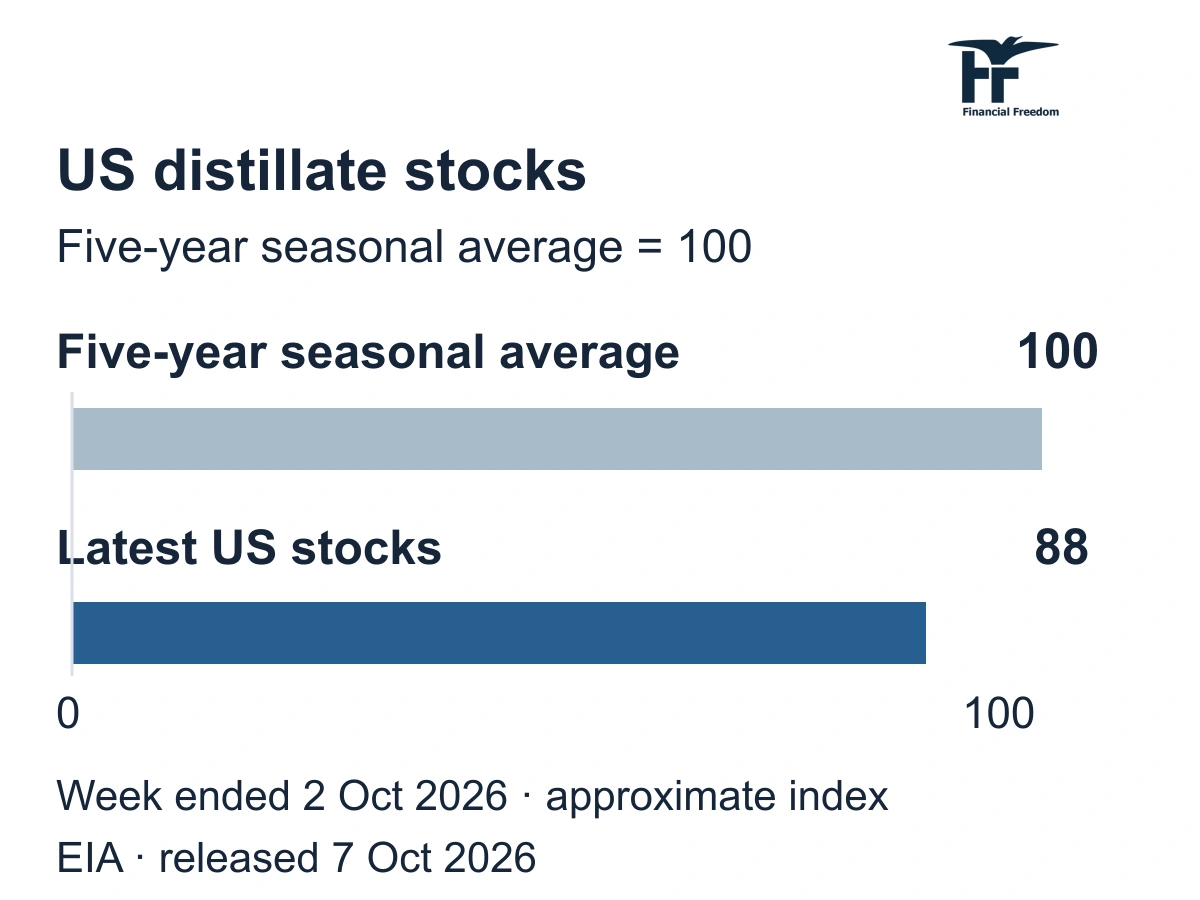
The EIA’s US weekly report, released on 7 October, showed distillate stocks broadly unchanged at about 105.1 million barrels in the week ending 2 October. They remained 12% below the five-year average. Additional crude pledges need not quickly lower diesel prices: crude must still be refined and products delivered.
? Distillate stocks: what is included?
Distillates include diesel and heating oil, not diesel alone. This compares US stocks with the five-year average for the corresponding season. A US weekly measure does not describe all global inventories.
Financial independence calculator
How much would you need to save?
Enter your target monthly income and current savings. See the gap and how changing your saving period affects the result.
Results depend on your assumptions, not guaranteed returns.
Quarter
What matters now
Growing investment does not remove borrowing-cost risks
Artificial intelligence infrastructure suppliers can face growth and more expensive borrowing at the same time. Data centre construction supports demand for chips, electrical equipment and engineering services. However, operators financing expansion with debt must consider future refinancing rates. More orders therefore do not necessarily mean an equal increase in profits: company costs and borrowing terms also matter.
Holders of long-maturity fixed-rate bonds face a different risk. If inflation forced the central bank to keep rates high for longer and market yields rose, those bonds could lose value. Weaker demand or easing energy costs would provide a counterweight. In September, participants viewed the labour market as stable but noted that the share of people finding a new job was low even though companies were laying off few workers.
Long-term borrowing depends on the specific debt
Heavily indebted property and infrastructure companies need to consider the rates they will pay when refinancing. However, a small daily yield move does not itself change a payment on an existing fixed-rate loan. The debt’s maturity, contractual terms and need for fresh funding determine the difference.
Germany’s headline recovery has not equalised company prospects
More completed work gives building-material and machinery producers scope to use equipment more fully and cover fixed costs. For automotive and energy-intensive chemical shares, their own sales and expenses matter more. A German equity fund holds different sectors, so higher overall production does not benefit every company equally. Factory holidays can temporarily distort monthly comparisons.
Diesel deliveries matter for freight costs and refiners’ profits
Faster diesel delivery could ease shortages and costs for road freight and agriculture. Product scarcity can help refiners earn a wider gap between product selling prices and crude purchase costs. That advantage could weaken if shortages ease. Reserve releases are temporary: prolonged disruptions also depend on operating refineries and open transport routes.
A weaker euro raises import costs and supports unhedged dollar assets
The European Central Bank reference rate fell to $1.1177 per euro on 7 October from $1.1269 on 6 October. A euro area importer needs more euros for the same dollar-priced fuel purchase. The currency move increases the euro value of a Lithuanian investor’s unhedged US bonds or shares if their dollar price is unchanged. Asset-price changes and any currency hedge also affect the total result.
? ECB reference rate: how should it be read?
This is US dollars per euro: a lower number means a weaker euro. The informational daily rate is not a transaction price. Its timing differs from the US market close, so it cannot precisely convert that session’s investment return into euros.
Quarter
What comes next
8 October, 11:30 Lithuania time. Fed Governor Christopher Waller is scheduled to speak on the economic outlook. Will the current assessment of inflation and growth differ from the September minutes?
8 October. The European Central Bank is scheduled to publish the account of its 9–10 September monetary-policy meeting. How did the council then assess energy inflation and weaker demand? This discusses an earlier decision; it is not a new rate decision.
8 October, 15:30 Lithuania time. The US will release its weekly number of people applying for unemployment benefits for the first time. Are companies beginning to cut staff more quickly?
8 October, 20:00 Lithuania time. Competitive bidding closes for a $22 billion reopening of 30-year Treasury bonds. The result will help assess demand for very long-term government borrowing.
14 October, 15:30 Lithuania time. The US will release September consumer price data. Is price pressure easing, or are broader increases persisting?
14 October. The International Energy Agency is scheduled to publish its October Oil Market Report. It will help assess changes in oil supply, shortages of refined products and the demand outlook; forecasts are not consumption already realised.
15 October, 19:00 Lithuania time. The US Energy Information Administration is scheduled to publish its weekly petroleum report for the week ending 9 October. Will distillate stocks begin to recover, or will fuel-supply pressure persist? Because of a US holiday, the release is scheduled for Thursday rather than the usual Wednesday.
28 October. The next Fed rate decision is scheduled. Will inflation and labour-market data published subsequently justify the further increase envisaged by September participants?
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.