Week · Market review
Week: fuel supply, consumers and borrowing costs
On 6–12 October, the gap between hopes and actual sales or deliveries became clearer. German orders and euro area retail volumes showed uneven demand, US consumers rated current conditions worse, and on Sunday the IEA asked members to consider more diesel. The weekly question is whether cost relief will arrive before weaker demand weighs on company profits.
Period covered: 2026-10-06 – 2026-10-12Information as of 12 min read
On 11 October, the IEA asked members to assess additional diesel releases. The US survey and German insolvency statistics published on 9 October add to the assessment of demand and credit risk.
No additional diesel volume has been agreed. The US policy-rate range remains 3.75–4.00%, and the euro area deposit rate is 2.50%; the stock-release request does not change those decisions.
Week
What happened
6 October: German orders showed weaker regular demand
On 6 October, Destatis reported that German manufacturing orders fell 10.6% in August from July, but only 0.1% excluding large contracts. The category covering ships, aircraft, trains and military vehicles had received unusually large orders in July. Even so, June–August orders excluding large contracts were 2.6% below the preceding three months, leaving regular demand weak.
? Manufacturing orders: how do they differ from revenue?
These are new orders adjusted for prices, seasonal effects and the calendar; August figures are preliminary. An order is not yet a finished product or collected revenue. The overall series and the population excluding large contracts are not additive components of the decline.
6 October retail data: the recovery remains small
On 6 October, Eurostat reported that euro area retail volumes rose 0.1% in August after declining 0.6% in July. Non-food volumes increased 0.5%, while fuel fell 1.9%. This was a small overall recovery with different product groups moving in different directions.
? Retail volume: how does it differ from revenue?
The volume measure removes price changes, and the monthly comparison is seasonally and calendar adjusted. It therefore describes changes in quantities sold, not retailers’ revenue or profit.
7 October: September Fed minutes and long-term borrowing
The US central bank’s 15–16 September minutes, released on 7 October, recalled that most participants had then envisaged another rate rise. The 0.25-percentage-point rise decided on 16 September took effect the next day, taking the range to 3.75–4.00%. These were earlier meeting discussions, not a new October decision.
On 7 October, the US Treasury sold a further $39 billion of 10-year bonds at a high yield of 5.30%, with a bid-to-cover ratio of 2.77. This is an auction of a specific issue, not a bond fund’s overall return.
German exports fell, but sales to different destinations diverged
The rise in Germany’s August production reported on 7 October was mainly driven by construction; trade figures released on 8 October showed that exports had not recovered in the same way that month. According to the statistical office Destatis, August goods exports fell 0.8% from July to €137.6 billion. Imports rose 0.9% to €118.1 billion. The goods trade surplus narrowed from July’s €21.6 billion to €19.5 billion.
The clearest new difference is between destination markets. Exports to the United States fell 6.3%, while shipments to the euro area rose 0.8%, China 4.7% and the United Kingdom 16.7%. Exporters did not experience a uniform decline. Moreover, sales to the US remained 22.6% above August 2025: the monthly fall did not erase the earlier year-on-year increase.
These figures do not yet explain which goods or causes produced the differences. The decline in exports to the US therefore cannot simply be attributed to tariffs: a more detailed goods breakdown and companies’ own sales may still change the assessment.
? Export change: what is being compared?
August and July goods values in euros are calendar and seasonally adjusted. They measure nominal value, not physical quantities alone. Destination changes are not additive contributions to the total; the annual comparison uses a different denominator.
Europe’s risk assessment linked technology borrowing and profit expectations
On 8 October, the European Systemic Risk Board published the assessment from its 1 October meeting: EU financial-stability risks had increased during the preceding quarter. The Board highlighted technology companies borrowing to expand artificial intelligence and the risk that future profit expectations may be too optimistic. This is a warning about a possible scenario, not a report of those companies already defaulting.
The risk extends beyond technology shares. More expensive government debt servicing reduces fiscal room, while funds investing with borrowed money can amplify bond-market swings. Conversely, the Board noted European banks’ strong capital, liquidity and profitability. Technology-financing concentration is smaller in the EU than in the US, so the two regions should not be treated as carrying identical risks.
8 October context: no promise of a rate pause
US central-bank Governor Christopher Waller on 8 October left open another rate rise if data develop as he expects. The European Central Bank’s September meeting account released that day also announced no new decision. September’s discussion had not yet shown a broad spread of energy inflation to wages and other prices; that remained an important condition for further rises.
In the US Treasury’s $22 billion reopening auction of 30-year bonds on 8 October, the high yield was 5.618%, compared with 5.308% in the same issue’s 10 September auction. This monthly comparison of new government borrowing differs from the indicative Friday yield discussed later; it is not a bond fund return.
The IEA asks members to consider further diesel releases, but no new volume is agreed
On 11 October, the International Energy Agency (IEA) asked member countries to assess whether additional diesel stock releases were needed. If governments chose to proceed, they should specify volumes and timing and clearly distinguish additional releases from earlier commitments. This is a new request, not an agreed additional number of barrels.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
The important distinction for investors is that crude oil is not yet fuel suitable for a truck. It needs refining and delivery to where diesel is scarce. An improvement in supply therefore depends not just on total stocks, but on which product is released and when it arrives. The IEA Oil Market Report on 14 October will help assess refining and supply conditions; the Governing Board meeting on 15 October will review countries’ actions.
? Emergency oil stocks: does a pledge already mean supply?
Public emergency stocks are oil and oil products held by governments to respond to supply disruptions. A pledged release, a quantity sold and fuel delivered to a buyer are different stages; additional action must be distinguished from the remainder of an earlier commitment.
US consumers rated current conditions more poorly, while their outlook improved
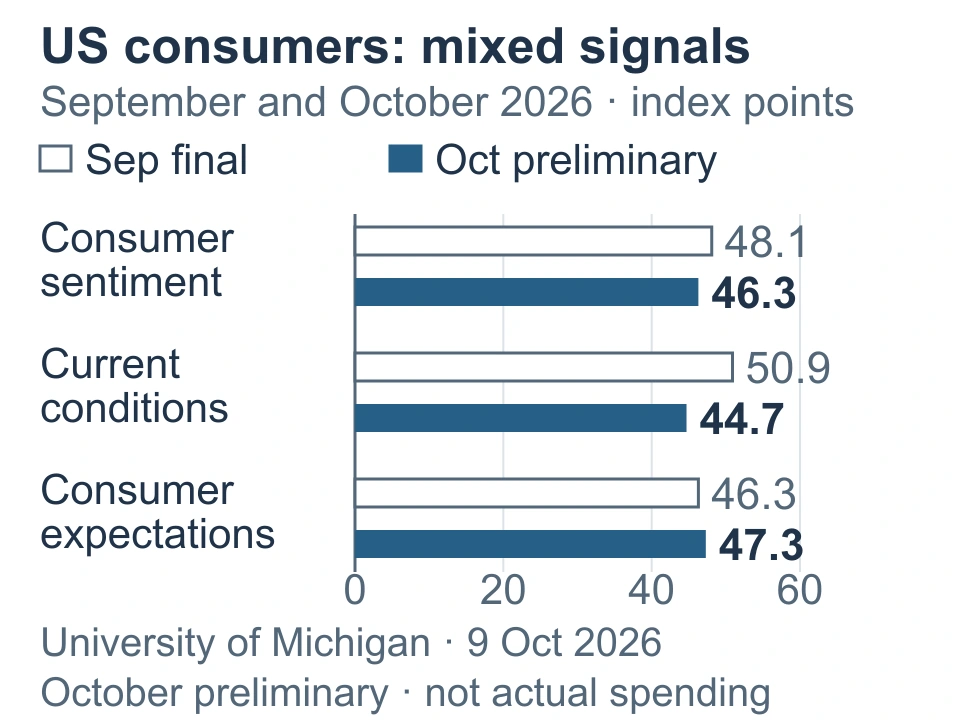
On 9 October, the University of Michigan published its preliminary October survey of US consumers. The sentiment index fell from September’s 48.1 to 46.3 points.
The assessment of current economic conditions deteriorated most sharply: its index fell from 50.9 to 44.7 points. The university highlighted high prices and borrowing costs that made consumers less comfortable with major purchases. However, the expectations index rose from 46.3 to 47.3 points, so the survey does not show a uniform deterioration across all expectations.
Meanwhile, the median of consumers’ expected inflation over the coming year rose from 4.6 to 4.7%. Weaker sentiment and higher price expectations can coexist: people who approach purchases more cautiously do not necessarily expect goods to become cheaper soon.
? Consumer surveys and inflation expectations: what do they show?
The survey measures consumers’ views, not a change in spending that has already taken place. The median is the middle response: half expect inflation no higher and half no lower; it is not a central-bank forecast or actual price growth. October’s results are still preliminary.
US bond yields rebounded on Friday from Thursday’s levels
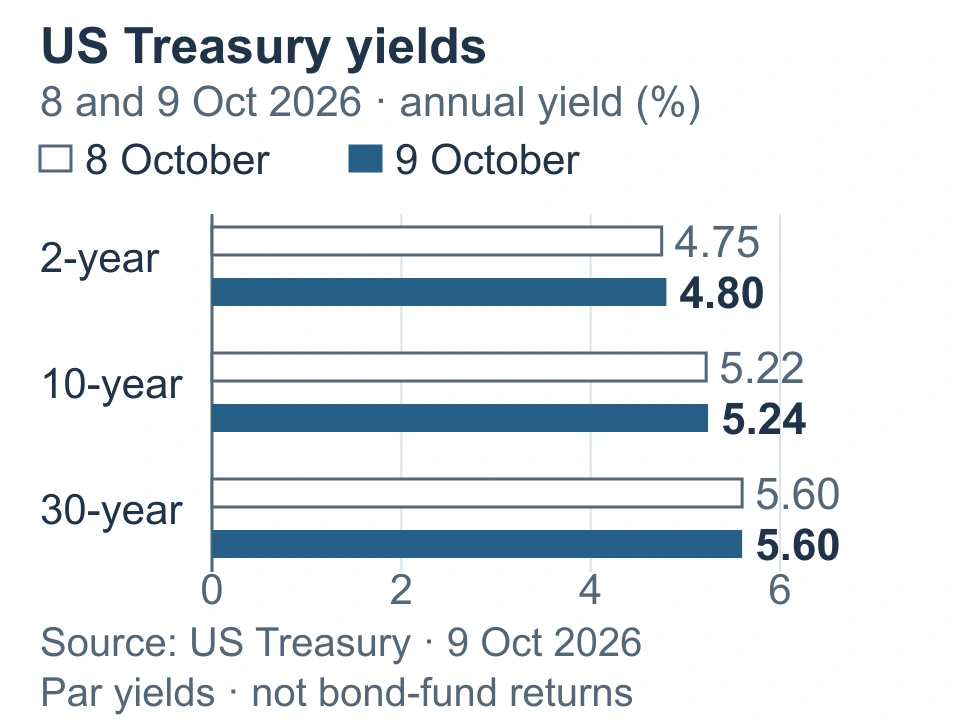
On 9 October, the annual yield on 10-year US Treasury securities rose from the previous trading day’s 5.22 to 5.24%. The decline on 8 October therefore did not continue on Friday. This is the latest officially published observation available before Monday morning.
The two-year yield rose from 4.75 to 4.80%, while the 30-year yield remained at 5.60%. However, the weekly comparison points in the other direction: since 2 October, yields at these maturities fell by 3, 4 and 3 basis points respectively. One day’s rebound did not erase the small weekly decline.
? Bond yield: how does it differ from return?
This is an indicative annual constant-maturity yield derived from US Treasury quotations, not a fund return already earned or the central bank’s policy rate. One basis point equals 0.01 percentage point. The table alone does not prove that the consumer survey caused Friday’s move.
German insolvency cases rise, but creditors' total claims fall
On 9 October, Germany’s statistical office Destatis reported that in July 2026 courts registered 2,373 corporate insolvency cases. That was 8.0% more than in July 2025.
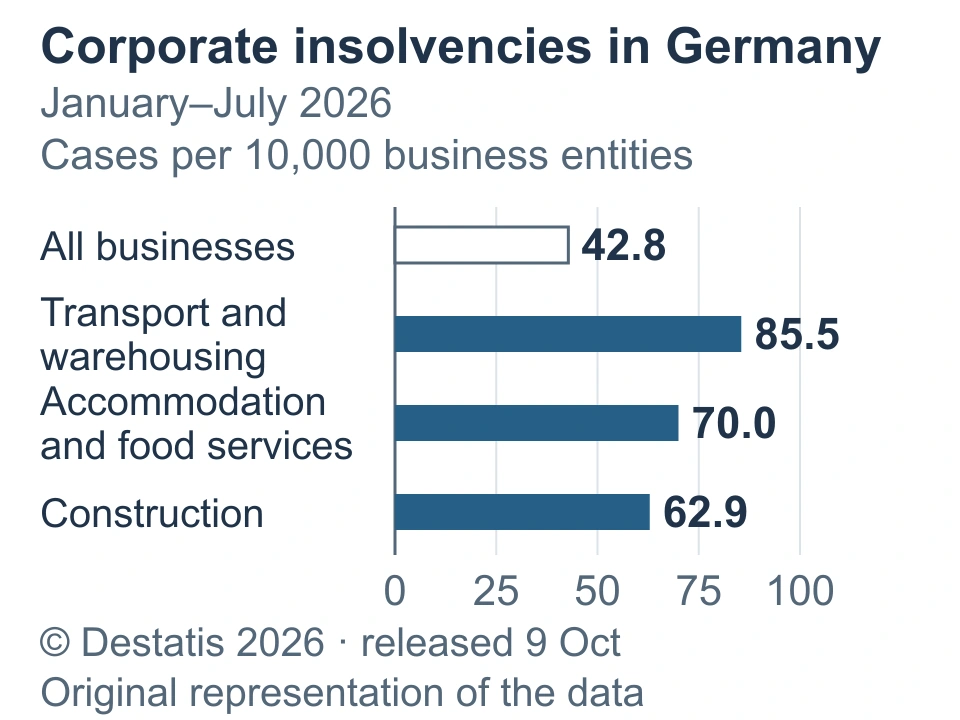
Risk is unevenly distributed. In January–July, transport and warehousing recorded 85.5 insolvency cases per 10,000 companies, compared with 42.8 across Germany’s economy. That is almost twice the frequency. The comparison highlights weakness in the sector, but does not tell us whether a particular logistics company can repay its bonds.
The number of cases is not the whole credit-risk story. Creditors’ claims in January–July cases amounted to about EUR21.9 billion, compared with EUR31.8 billion a year earlier. Destatis explains that more economically significant companies had filed for insolvency in the earlier period. More frequent cases therefore do not necessarily mean a larger aggregate sum of creditors’ claims.
? Corporate insolvency frequency: what does it measure?
Frequency is the number of court-registered cases per 10,000 companies in the relevant sector; it is not the probability that an individual bond will default. A filing enters the statistics after the court’s first decision, often about three months after submission. Creditors’ claims are not realised losses, and businesses closing for other reasons are not counted here.
Professional portfolio management
A plan for your portfolio. No rush.
Let’s discuss your goals, risk tolerance and time horizon. Find out how your portfolio would be built and managed.
The first conversation is free, with no obligation.
Week
What matters now
Fuel users need delivered diesel, not just another pledge
Transport-company shares and industrial corporate bonds are exposed to fuel bills and to how much of those costs companies can pass on to customers. If additional diesel actually reaches buyers, fuel users’ costs could fall. Slow delivery or another supply disruption, however, would keep pressure on profits and the cash available to repay debt.
Oil-producer shares face a different risk: more fuel reaching the market may ease conditions for their customers, while restored supply may weigh on crude selling prices. Refiners’ profits also depend on the gap between fuel selling prices and the cost of their feedstock. One blanket view of the energy sector would therefore be too broad. Specified additional volumes and delivery schedules would help distinguish genuine cost relief from merely improved expectations.
For consumer businesses, the question is whether caution is already reducing sales
The University of Michigan’s 9 October survey sends a different signal to sellers of major purchases and consumer-equity funds than to companies supplying everyday necessities. A car or household appliance is easier to postpone, while people may keep buying essential goods by switching to cheaper alternatives. These are possible patterns of demand, not company sales results already reported.
Consumer lenders also need to consider borrowers’ ability to repay. If price pressures eased, demand for major purchases could recover; if household incomes failed to keep pace with costs, risks to sales and credit losses would increase. Results from US bank JPMorganChase on 13 October will help assess borrowers’ finances, while US September retail-sales data on 15 October will show actual sales.
A higher yield for a new buyer is not the same as a gain on an existing bond
On 9 October, existing fixed-rate US Treasury bond prices could have come under pressure at maturities where yields rose. At the same time, a buyer of a new 2- or 10-year bond could have obtained a higher yield than on Thursday. For debt-funded property companies, refinancing costs matter; an existing fixed-rate loan payment does not change with daily market quotations.
If US September consumer-price data on 14 October showed weaker inflation pressure, longer-maturity bond prices could find support. More persistent price growth would strengthen the risk of expensive financing for both bonds and debt-sensitive equities. The US central bank’s policy-rate range set in September remains 3.75–4.00%; its next decision is scheduled for 28 October.
A company's ability to repay matters more than the insolvency headline
For holders of higher-risk European corporate bonds, the issue is not just the interest rate but whether the issuer will have enough cash to pay interest and principal. Bank and supplier shareholders, meanwhile, face customers’ late payments and potential credit losses. Sector statistics help identify where company finances deserve closer scrutiny, but do not replace an assessment of cash, debt maturities and customer concentration.
The smaller aggregate sum of claims is a counterweight, so more registered cases do not automatically imply equal pressure on every creditor. An opportunity could arise where a bond’s price already reflects its specific risk and the company has sufficient cash to meet its obligations. Germany’s final September inflation release on 13 October will update the cost assessment; it will not establish whether an individual borrower is solvent. That requires its results and actual payments.
For 12 October, a holiday closure is recommended for the US bond market, while US stock exchanges have no scheduled holiday. Japanese share trading is closed; some derivatives continue trading. Friday’s bond level should therefore not be treated as a measured Monday response to weekend news.
Week
What comes next
On 13 October, Germany will release final September inflation; US bank JPMorganChase will release quarterly results at about 14:00 Lithuanian time and discuss them at 15:30. Do price pressures and borrowers’ finances fit consumers’ poorer assessment of current conditions?
On 14 October, the IEA will publish its Oil Market Report, while the US Bureau of Labor Statistics will release September’s Consumer Price Index at 15:30 Lithuanian time. Do tight fuel supply and actual price growth reinforce the risk of expensive borrowing?
On 15 October, the IEA Governing Board will review stock-release actions. US September retail sales will be released that day at 15:30, followed at 19:00 by the US Energy Information Administration’s stocks for the week ending 9 October. Will additional diesel plans become specified volumes and dates, and is consumer caution already visible in sales?
The final Michigan October survey is due on 23 October at 17:00. The US central bank’s next decision is expected on 28 October at 20:00; the ECB’s follows on 29 October. Will new price and demand data justify changing interest rates or keeping them unchanged?
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.