Year · Market review
Year: the rate turn, energy and sustainable profits
Over the trailing year, central-bank rate cuts gave way to pauses and increases. Changing trade rules and war fed into delivery and fuel costs, while technology investment widened the gap between equipment suppliers’ earnings and customers’ spending. The 11 October request to assess more diesel is a reminder that a stock-release pledge is not yet fuel delivered to a buyer.
Period covered: 2025-10-13 – 2026-10-12Information as of 28 min read
On 11 October, the IEA asked members to assess additional diesel releases. The US survey and German insolvency statistics published on 9 October add to the assessment of demand and credit risk.
No additional diesel volume has been agreed. The US policy-rate range remains 3.75–4.00%, and the euro area deposit rate is 2.50%; the stock-release request does not change those decisions.
Year
What happened
Autumn 2025: US interest rates fell while Europe opted for a pause
Before this rolling period began, on 17 September 2025, the Federal Reserve cut its target range from 4.25–4.50% to 4.00–4.25%. That is the starting background before the period beginning on 13 October 2025. It cut the range by another quarter point on both 29 October and 10 December, reaching 3.50–3.75%. Each decision took effect the following day.
Lower interest rates helped some borrowers, but their benefits cannot be separated from the reason for the cuts. If a central bank cuts rates because it sees weaker demand, a company’s cheaper loan may be offset by poorer sales. That is why the simple rule that “rates were cut, so that is good for shares” does not explain the market’s entire reaction.
During the autumn, the European Central Bank kept the rate paid on banks’ overnight deposits at 2.00%. Its 11 September decision was announced before this rolling twelve-month period began, but established its starting backdrop. The rate remained unchanged at the October and December meetings. The US and the euro area were therefore already following different paths.
November: the US and China agreed to ease some tariffs and export restrictions
On 1 November 2025, the US announced the terms of an agreement with China. The US committed to reducing the cumulative fentanyl-related tariff on Chinese goods by 10 percentage points from 10 November. China committed to suspending new rare-earth export controls announced on 9 October. These materials are used in industrial and technological equipment, so supply conditions matter to more than just their producers.
However, temporary relief is not a permanent, unchanging rule. A factory needs to know when a component will arrive and what its final cost will be. Uncertainty encourages companies to hold larger inventories or seek a more expensive alternative supplier. The November decision therefore cannot automatically be presented as the tariff applying to all goods today: subsequent measures have their own legal bases and conditions.
December: the UK cut interest rates while Japan raised them
On 18 December 2025, the Bank of England announced a 0.25 percentage point cut in Bank Rate to 3.75%. The next day, the Bank of Japan announced an increase in its overnight interest-rate target from 0.50% to 0.75%, effective from 22 December. UK borrowers gained the prospect of cheaper credit, while conditions for new borrowing and replacing old debt with new loans tightened in Japan.
January 2026: switching energy suppliers became a concrete plan
On 26 January, the Council of the European Union approved a gradual phase-out of Russian gas imports. A full ban on liquefied natural gas is scheduled from the beginning of 2027, and on pipeline gas from autumn 2027. These are future deadlines with transition periods, not a halt to all imports on that January date.
Replacing Russian gas required new supply contracts and infrastructure. Other suppliers, ships, terminals and reserves were needed. Over time, a wider choice of suppliers may reduce dependence, but the transition itself also costs money. Investors need to distinguish the long-term benefits of resilience from the near-term bills for energy and infrastructure.
Meanwhile, the US central bank was in no hurry to continue the autumn cuts. The 3.50–3.75% range remained unchanged at its January, March and April meetings. Europe’s February, March and April decisions also maintained the 2.00% deposit facility rate. Earlier cuts were not a promise that every subsequent meeting would follow the same pattern.
February: the legal basis for tariffs changed
On 20 February, the US Supreme Court ruled that the International Emergency Economic Powers Act does not authorise the president to impose tariffs. The decision restricted a specific legal basis. It did not mean that all US import tariffs disappeared, because other measures relied on different laws.
On the same day, the administration announced a temporary 10% import surcharge, with exemptions, under a different section of the Trade Act. The proclamation specified a start on 24 February and a 150-day period until 24 July. This is a historical measure, not a tariff automatically applying to all imports today.
For businesses, changes like these mean having to recheck a product’s origin, classification code, delivery date and exemptions. An importer uncertain of the final cost may delay an order or hold more inventory. Even a politically favourable headline therefore does not always immediately reduce a company’s costs or increase its sales.
February's results showed that technology demand was more than a promise
On 25 February, chip designer NVIDIA reported results for its financial year ended 25 January. Revenue reached $215.938 billion, while net income under US accounting standards was $120.067 billion. Both figures were 65% higher than in the company’s previous financial year. These are results for a completed period, not a forecast for calendar year 2026.
This matters to the longer story: technology suppliers were generating visible, actual earnings well before the summer results season. But profit does not answer the question of an investment’s price. Even a successful company may be valued on very high expectations for the future that subsequently prove harder to meet.
Spring: geopolitical risk became an oil delivery problem
The war in the Middle East that began on 28 February disrupted oil shipments through the Strait of Hormuz. On 11 March, International Energy Agency member countries agreed to make 400 million barrels of emergency oil reserves available to the market. This was the largest coordinated release amount in the agency’s history. The decision was a commitment to release reserves, not the release of the entire volume in one day.
Reserves can buy time, but cannot replace commercial supply indefinitely. When reliable deliveries are lacking, the effects spread from the oil market to fuel, transport, chemicals and household purchasing power. More expensive energy can simultaneously raise inflation and weaken growth. A central bank faces an uncomfortable choice: raising interest rates does not produce additional oil, but cutting them may stimulate demand at a time when supply is constrained.
May: the EU–Mercosur agreement reduced some tariffs
On 1 May 2026, provisional application began for the European Union’s trade agreement with Argentina, Brazil, Paraguay and Uruguay, the Mercosur countries. Initial tariff reductions took effect for products including cars, pharmaceuticals and some food and drink, such as wine and olive oil. These were applicable trading terms, but not yet the fully ratified partnership agreement.
European exporters gained opportunities to reach buyers on more favourable terms. For importers, a wider choice may help reduce dependence on a single supplier. At the same time, greater competition puts pressure on more vulnerable sectors. Actual orders and the use of trade preferences ultimately reveal the investment significance, not just the headline on the day an agreement is signed or takes effect.
June and July: Europe's interest rate direction reversed
On 11 June, the European Central Bank announced a 0.25 percentage point rate increase. The deposit facility rate rose to 2.25% from 17 June. It was left unchanged on 23 July. The US maintained its 3.50–3.75% target range at the 17 June and 29 July meetings. US cuts had therefore given way to a pause, while Europe had already turned towards higher rates.
On 16 June 2026, the Bank of Japan decided to raise its overnight interest-rate target again, from 0.75% to 1.00%, effective from 17 June. It left that target unchanged on 31 July. Borrowing in Japan was therefore becoming more expensive before the September decision, affecting Japanese bonds and investments financed with borrowed yen.
The 18 June memorandum between the US and Iran raised hopes of normalising supply. But the International Energy Agency’s 10 July report already described ceasefire breaches on 7–8 July. Its August edition showed weaker oil export flows in July. An agreement and its implementation proved to be two separate stages that matter to investors.
On 23 July, the European Union expanded energy and financial sanctions against Russia. On the same day, the Office of the US Trade Representative announced tariff measures on imports from 60 economies, including the European Union, over insufficient bans on imports of goods made with forced labour. Tariffs depended on products and exemptions; this was not an extension of February’s temporary surcharge. Importers had to check both supply availability and the tariff applying to each product.
Summer: NVIDIA’s profits grew while its customers invested heavily in infrastructure
On 26 August, NVIDIA reported revenue of $96.221 billion for the quarter ended 26 July. Revenue was 106% higher and operating profit 124% higher than a year earlier. This result confirmed that demand for the supplier remained real. Its customers, however, pay for equipment, data centres and electricity infrastructure before receiving all their expected revenue.
On 29 July, Microsoft reported that it generated $55.4 billion in operating cash flow during the quarter ended 30 June and spent $35.8 billion in cash on purchases of long-term assets. On 10 September, Oracle reported $28.5 billion in capital expenditure and $23.1 billion in operating cash flow for the quarter ended 31 August. The two companies’ quarters ended on different dates. These are not identical businesses, but the comparison shows why the technology story requires monitoring more than revenue growth.
Early September: prices brought attention back to interest rates
On 9 September, the US Energy Information Administration raised its forecast for the average Brent price in the second half of the year to around $90 per barrel. The publication used model inputs finalised by 3 September. It therefore does not measure the impact of later military reports in September and is not the latest exchange price.
On 10 September, the European Central Bank announced another 0.25 percentage point rate increase. On 11 September, the US Consumer Price Index showed annual price growth of 3.4% in August, unchanged from July. Seasonally adjusted monthly growth increased from 0.1% to 0.4%. However, annual growth in the basket excluding food and energy slowed from 2.5% to 2.4%. Monthly growth in this basket nevertheless increased from 0.2% to 0.3%. Prices therefore rose faster over the month even though annual inflation slowed for some goods and services.
The interest rate path in one place
The table shows changes to key US and euro area interest rates announced within this twelve-month period through 30 September, the July decisions to leave them unchanged, and an earlier US decision establishing the starting backdrop. It is not a list of every meeting. Europe’s decision announced on 10 September took effect on 16 September.
| Decision date | Region | Before | After | When it applies |
|---|---|---|---|---|
| 2025-09-17 | US | 4.25–4.50% | 4.00–4.25% | From 18 September |
| 2025-10-29 | US | 4.00–4.25% | 3.75–4.00% | From 30 October |
| 2025-12-10 | US | 3.75–4.00% | 3.50–3.75% | From 11 December |
| 2026-06-11 | Euro area | 2.00% | 2.25% | From 17 June |
| 2026-07-23 | Euro area | 2.25% | 2.25% | Left unchanged |
| 2026-07-29 | US | 3.50–3.75% | 3.50–3.75% | Range left unchanged |
| 2026-09-10 | Euro area | 2.25% | 2.50% | In effect from 16 September |
| 2026-09-16 | US | 3.50–3.75% | 3.75–4.00% | From 17 September |
For the US, the table shows the federal funds target range; for the euro area, it shows the specific deposit facility rate. Europe’s 2.50% rate took effect on 16 September. On 30 September, the prevailing US range was 0.25 percentage points lower than after the decision of 17 September 2025 that established the starting backdrop. The European deposit rate rose 0.50 percentage points. The US increase of 16 September is included in the table.
? Consumer Price Index: why does the monthly change matter too?
The Consumer Price Index is compiled using the prices of goods and services and their weights in consumption. The annual change compares prices with the same month of the previous year. The seasonally adjusted monthly change helps show the latest pace. The annual figure can therefore remain unchanged even when prices rise faster in the latest month.
Mid-September: oil supply was forecast to fall more than demand
The International Energy Agency’s 11 September forecast projects a larger decline in oil supply than in demand this year. This is a forecast, not a final annual result.
16–24 September: US bond yields rose again after a brief decline
On 16 September the Federal Reserve raised its target range to 3.75–4.00%. An earlier European decision lifting the deposit rate to 2.50% took effect on the same day. The US ten-year yield fell to 4.96% on 21–22 September, but reached 5.18% on 24 September. The fall in US bond yields was therefore short-lived.
The preliminary S&P Global US PMI Composite Output Index, covering manufacturing and services activity, reached 58.4 in the release of 23 September, compared with 56.0 in August. Seasonally adjusted initial unemployment benefit claims of 197,000 for the week ending 19 September, released on 24 September, at that time added to the evidence that the economy was not weakening sharply. On 1 October, that week’s claims were revised to 198,000; the newer week ending 26 September recorded 197,000. Claims are not a count of jobs created or a final measure of an entire quarter’s growth.
? Purchasing Managers’ Index: what does the threshold mean?
The company survey compares activity with the previous month. Above 50 generally indicates expansion and below 50 contraction. A reading of 58.4 does not mean growth of 58.4%; the preliminary measure may be revised.
September’s decisions extended beyond the US and euro area. On 18 September the Bank of Japan set an overnight interest-rate target of 1.25%, effective from 24 September. On 17 September the Bank of England left Bank Rate at 3.75%. These different paths matter for Japanese bonds and yen-funded investments, as well as British companies’ borrowing costs.
25–28 September: uneven demand and trade relief not yet in force
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
On 27 September, the White House published US and Chinese lists covering about $30 billion of imports in each direction, proposed for lower tariffs. The US list of imports from China includes plastic tableware and bedding; China’s list of imports from the US includes beef and dairy products. This publication did not bring tariff reductions into force. On 28 September, China reported that August profit at larger industrial enterprises was 4.2% higher than a year earlier; July’s growth was 11.2%. These are year-on-year comparisons; they do not show whether profit rose or fell from July to August. Companies’ profits would depend not only on lower tariffs, but also on selling more goods at profitable prices.
30 September: spending remained resilient while energy prices rose
Figures released by the US Bureau of Economic Analysis on 30 September showed real consumer spending rising 0.6% month on month in August, while real disposable income was unchanged. The Personal Consumption Expenditures Price Index, or PCE, was 3.4% higher year on year; excluding food and energy, the increase was 3.0%. July’s annual readings were identical in the same revised data series.
? Personal consumption price index: what does it measure?
The Personal Consumption Expenditures Price Index measures price changes for goods and services purchased for consumers, including some spending on their behalf. Excluding food and energy separates out more volatile prices; the measure is not growth in the volume of consumption.
Germany’s preliminary national September inflation rate rose from 2.9% to 3.3%, with energy inflation increasing from 10.5% to 14.9%, while the rate excluding food and energy remained at 2.4%. France’s measure under the common European methodology rose from 2.6% to 3.4%. On the same day, China’s manufacturing Purchasing Managers’ Index rose from 49.8 to 50.1, but its new-orders index fell from 50.6 to 50.5 and the raw-material purchase-price index increased from 56.6 to 60.8. The different indices showed growing activity alongside uneven cost increases.
US Energy Information Administration figures released on 30 September put commercial crude stocks at 427.3 million barrels in the week ending 25 September, 2.6% above a year earlier. Petrol inventories were nevertheless 7.4% lower, and distillates, including diesel and heating products, 14.9% lower. A rise in crude stocks therefore did not by itself resolve the question of finished-fuel supply.
On 30 September, the US Bureau of Economic Analysis revised second-quarter real gross domestic product growth, the value of goods and services produced in the country, from an annualised 1.5% to 2.2%. That is 0.6% above the previous quarter. The revision describes April–June demand, not September production.
30 September: memory-chip maker Micron reported higher revenue
US memory-chip maker Micron reported on 30 September that revenue for its fiscal quarter ended 3 September was $54.229 billion, compared with $11.315 billion a year earlier. This year’s quarter contained 14 weeks against 13 in the previous year, so the periods are not identical in length. The result added to the record of rising technology-supplier revenue. However, the value of the company’s shares depends on more than revenue already earned: it also matters how much future growth investors already expect.
1 October: orders held up while new borrowing cost more
The Institute for Supply Management’s September manufacturing survey, released on 1 October, put its Purchasing Managers’ Index at 54.5. Activity was still expanding, but the prices-paid index increased from 71.1 to 77.9. For a manufacturer, this means an opportunity to sell more without necessarily earning more if higher material costs cannot be passed on to customers.
On the same day, the European Central Bank reported that the euro-area new mortgage rate indicator rose to 3.60% in August, consumer credit rates to 7.92%, while the corporate borrowing cost indicator was almost unchanged at 3.77%. These are averages for new agreements, not changes in payments on existing Lithuanian loans. August statistics do not yet show the effects of the subsequent September rate increase.
Eurostat reported on 1 October that Lithuanian house transaction prices were 14.3% higher year on year in the second quarter, against 4.0% in the euro area. This April–June comparison describes prices, not rental income or net investment returns. A home buyer needs to consider both the purchase price and future mortgage payment, but later euro-area lending rates cannot be presented as the cause of earlier Lithuanian price growth.
2–4 October: US jobs growth slowed while energy risks persisted
On 2 October, the US Bureau of Labor Statistics reported that nonfarm payrolls rose by 29,000 in September, following a revised increase of 133,000 in August. The combined July and August result was revised down by 60,000. The weakness was not confined to the latest month: the earlier path of jobs growth was also lower than previously reported.
The September unemployment rate was 4.2%. Slower jobs growth can limit growth in household income and discretionary spending. These figures do not by themselves establish an economy-wide downturn, however.
? Unemployment rate: what is the denominator?
It is the share of the labour force who are not employed, are actively looking for work and are available to work, rather than a share of the whole population. Unemployment and payroll figures come from different surveys, so their monthly movements need not match.
Also on 2 October, Eurostat’s flash estimate showed euro area annual consumer inflation rising from 3.2% to 3.8% in September. These are prices paid by consumers, not the producer selling prices discussed below. On 4 October, seven countries in the OPEC+ group of oil producers retained September production targets for November; these are agreed volumes, not confirmed actual oil supply.
5–6 October releases: higher costs and uneven demand
On 5 October, the Nasdaq Composite share-price index rose 1.05% from its 2 October close, measured in US dollars. The US 10-year Treasury yield meanwhile increased from 5.28% to 5.31%. These are different market measures: rising share prices do not establish that companies can borrow more cheaply.
On 5 October, the US Institute for Supply Management’s September Services Purchasing Managers’ Index (ISM Services PMI) fell from 55.4 to 54.9, while its prices index increased from 72.6 to 74.0. Activity expanded more slowly but cost pressures became more widespread.
? Services and prices indices: what do they measure?
The services survey index gives equal weight to activity, new orders, employment and delivery times. A reading above 50 indicates prevailing expansion compared with the previous month. The separate prices index measures the breadth of price increases: 74 points does not mean 74% inflation.
On 6 October, Destatis reported that German manufacturing orders fell 10.6% in August from July, but only 0.1% excluding large contracts. The category covering ships, aircraft, trains and military vehicles had received unusually large orders in July. Even so, June–August orders excluding large contracts were 2.6% below the preceding three months, leaving regular demand weak.
? Manufacturing orders: how do they differ from revenue?
These are new orders adjusted for prices, seasonal effects and the calendar; August figures are preliminary. An order is not yet a finished product or collected revenue. The overall series and the population excluding large contracts are not additive components of the decline.
On 5 October, Eurostat reported that euro area industrial producer prices rose 1.9% in August from the previous month, with energy up 5.6% and industry excluding energy up 0.2%.
? Producer prices: what do they not show?
The Industrial Producer Price Index measures domestic selling prices, not a company’s entire input-cost basket or consumer inflation. August is compared with July; the energy group’s 5.6% rise is not its percentage-point contribution to the overall index.
Also on 5 October, ECB Executive Board member Philip Lane explained that costlier energy leaves households less money for other goods, while higher long-term interest rates constrain consumption and investment. This was his assessment, not a new interest-rate decision.
6 October retail data: the recovery remains small
On 6 October, Eurostat reported that euro area retail volumes rose 0.1% in August after declining 0.6% in July. Non-food volumes increased 0.5%, while fuel fell 1.9%. This was a small overall recovery with different product groups moving in different directions.
? Retail volume: how does it differ from revenue?
The volume measure removes price changes, and the monthly comparison is seasonally and calendar adjusted. It therefore describes changes in quantities sold, not retailers’ revenue or profit.
7 October: September Fed minutes and long-term borrowing
The US central bank’s 15–16 September minutes, released on 7 October, recalled that most participants had then envisaged another rate rise. The 0.25-percentage-point rise decided on 16 September took effect the next day, taking the range to 3.75–4.00%. These were earlier meeting discussions, not a new October decision.
On 7 October, the US Treasury sold a further $39 billion of 10-year bonds at a high yield of 5.30%, with a bid-to-cover ratio of 2.77. This is an auction of a specific issue, not a bond fund’s overall return.
German exports fell, but sales to different destinations diverged
The rise in Germany’s August production reported on 7 October was mainly driven by construction; trade figures released on 8 October showed that exports had not recovered in the same way that month. According to the statistical office Destatis, August goods exports fell 0.8% from July to €137.6 billion. Imports rose 0.9% to €118.1 billion. The goods trade surplus narrowed from July’s €21.6 billion to €19.5 billion.
The clearest new difference is between destination markets. Exports to the United States fell 6.3%, while shipments to the euro area rose 0.8%, China 4.7% and the United Kingdom 16.7%. Exporters did not experience a uniform decline. Moreover, sales to the US remained 22.6% above August 2025: the monthly fall did not erase the earlier year-on-year increase.
These figures do not yet explain which goods or causes produced the differences. The decline in exports to the US therefore cannot simply be attributed to tariffs: a more detailed goods breakdown and companies’ own sales may still change the assessment.
? Export change: what is being compared?
August and July goods values in euros are calendar and seasonally adjusted. They measure nominal value, not physical quantities alone. Destination changes are not additive contributions to the total; the annual comparison uses a different denominator.
Europe’s risk assessment linked technology borrowing and profit expectations
On 8 October, the European Systemic Risk Board published the assessment from its 1 October meeting: EU financial-stability risks had increased during the preceding quarter. The Board highlighted technology companies borrowing to expand artificial intelligence and the risk that future profit expectations may be too optimistic. This is a warning about a possible scenario, not a report of those companies already defaulting.
The risk extends beyond technology shares. More expensive government debt servicing reduces fiscal room, while funds investing with borrowed money can amplify bond-market swings. Conversely, the Board noted European banks’ strong capital, liquidity and profitability. Technology-financing concentration is smaller in the EU than in the US, so the two regions should not be treated as carrying identical risks.
8 October context: no promise of a rate pause
US central-bank Governor Christopher Waller on 8 October left open another rate rise if data develop as he expects. The European Central Bank’s September meeting account released that day also announced no new decision. September’s discussion had not yet shown a broad spread of energy inflation to wages and other prices; that remained an important condition for further rises.
In the US Treasury’s $22 billion reopening auction of 30-year bonds on 8 October, the high yield was 5.618%, compared with 5.308% in the same issue’s 10 September auction. This monthly comparison of new government borrowing differs from the indicative Friday yield discussed later; it is not a bond fund return.
The IEA asks members to consider further diesel releases, but no new volume is agreed
On 11 October, the International Energy Agency (IEA) asked member countries to assess whether additional diesel stock releases were needed. If governments chose to proceed, they should specify volumes and timing and clearly distinguish additional releases from earlier commitments. This is a new request, not an agreed additional number of barrels.
On 7 October, IEA members had already supported faster completion of the outstanding March stock-release programme, prioritising diesel. Countries that have fulfilled their earlier commitments are now also being asked to consider further action. The agency also highlighted renewed attacks on Saudi Arabia’s civilian and energy infrastructure.
The important distinction for investors is that crude oil is not yet fuel suitable for a truck. It needs refining and delivery to where diesel is scarce. An improvement in supply therefore depends not just on total stocks, but on which product is released and when it arrives. The IEA Oil Market Report on 14 October will help assess refining and supply conditions; the Governing Board meeting on 15 October will review countries’ actions.
? Emergency oil stocks: does a pledge already mean supply?
Public emergency stocks are oil and oil products held by governments to respond to supply disruptions. A pledged release, a quantity sold and fuel delivered to a buyer are different stages; additional action must be distinguished from the remainder of an earlier commitment.
US consumers rated current conditions more poorly, while their outlook improved
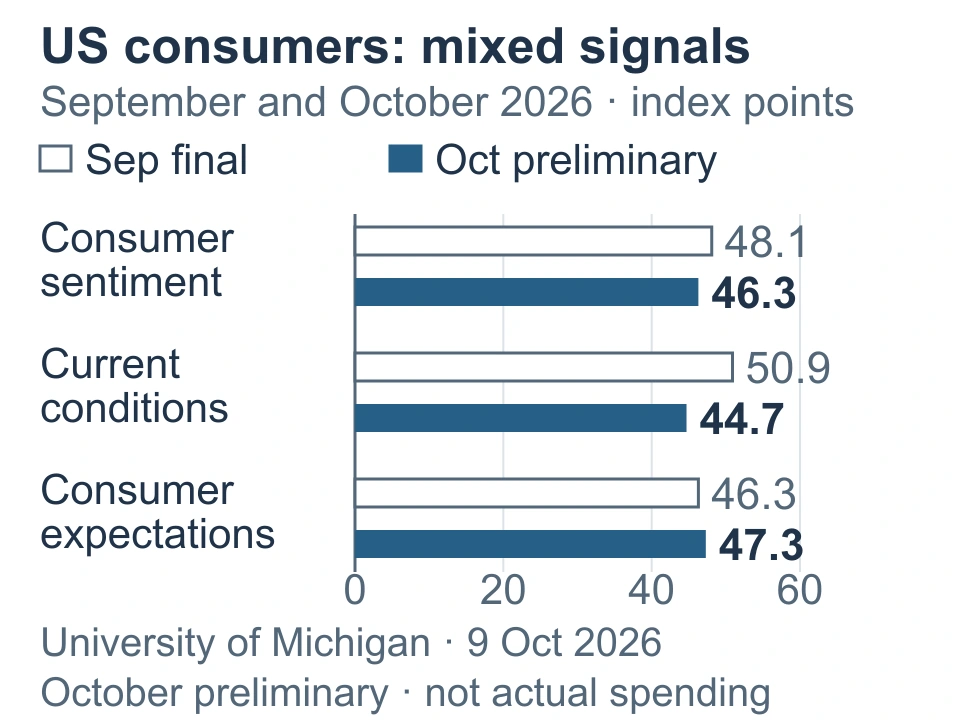
On 9 October, the University of Michigan published its preliminary October survey of US consumers. The sentiment index fell from September’s 48.1 to 46.3 points.
The assessment of current economic conditions deteriorated most sharply: its index fell from 50.9 to 44.7 points. The university highlighted high prices and borrowing costs that made consumers less comfortable with major purchases. However, the expectations index rose from 46.3 to 47.3 points, so the survey does not show a uniform deterioration across all expectations.
Meanwhile, the median of consumers’ expected inflation over the coming year rose from 4.6 to 4.7%. Weaker sentiment and higher price expectations can coexist: people who approach purchases more cautiously do not necessarily expect goods to become cheaper soon.
? Consumer surveys and inflation expectations: what do they show?
The survey measures consumers’ views, not a change in spending that has already taken place. The median is the middle response: half expect inflation no higher and half no lower; it is not a central-bank forecast or actual price growth. October’s results are still preliminary.
US bond yields rebounded on Friday from Thursday’s levels
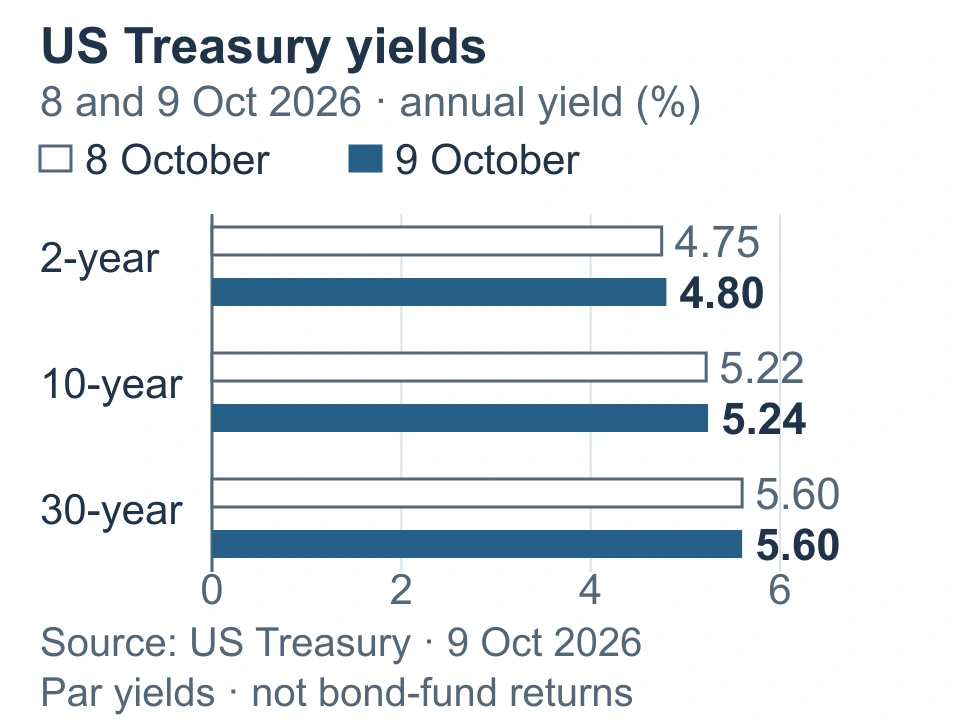
On 9 October, the annual yield on 10-year US Treasury securities rose from the previous trading day’s 5.22 to 5.24%. The decline on 8 October therefore did not continue on Friday. This is the latest officially published observation available before Monday morning.
The two-year yield rose from 4.75 to 4.80%, while the 30-year yield remained at 5.60%. However, the weekly comparison points in the other direction: since 2 October, yields at these maturities fell by 3, 4 and 3 basis points respectively. One day’s rebound did not erase the small weekly decline.
? Bond yield: how does it differ from return?
This is an indicative annual constant-maturity yield derived from US Treasury quotations, not a fund return already earned or the central bank’s policy rate. One basis point equals 0.01 percentage point. The table alone does not prove that the consumer survey caused Friday’s move.
German insolvency cases rise, but creditors' total claims fall
On 9 October, Germany’s statistical office Destatis reported that in July 2026 courts registered 2,373 corporate insolvency cases. That was 8.0% more than in July 2025.
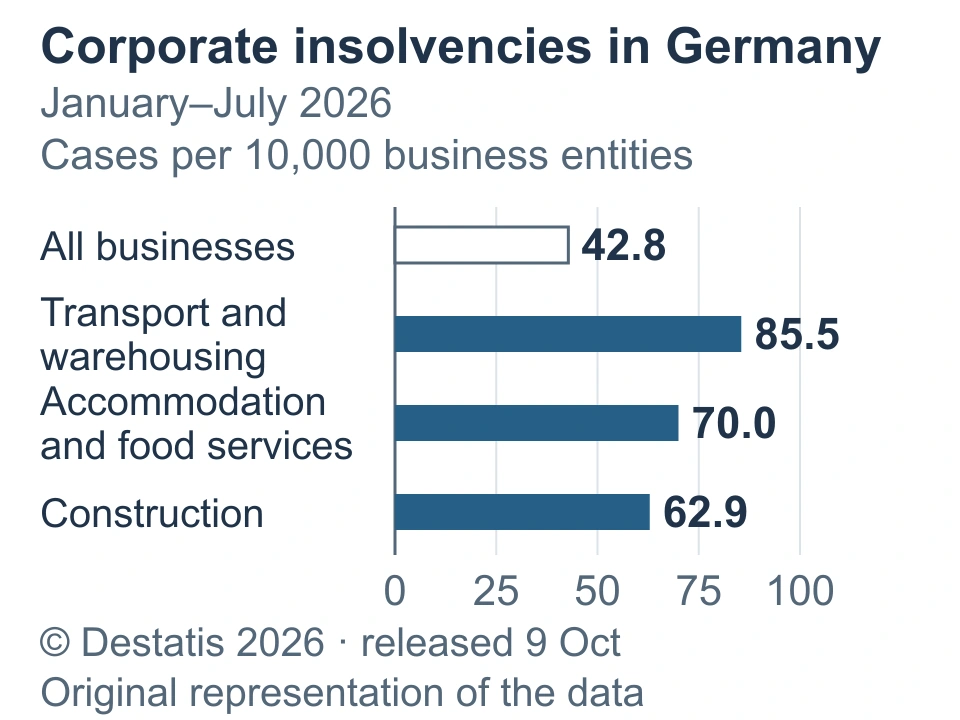
Risk is unevenly distributed. In January–July, transport and warehousing recorded 85.5 insolvency cases per 10,000 companies, compared with 42.8 across Germany’s economy. That is almost twice the frequency. The comparison highlights weakness in the sector, but does not tell us whether a particular logistics company can repay its bonds.
The number of cases is not the whole credit-risk story. Creditors’ claims in January–July cases amounted to about EUR21.9 billion, compared with EUR31.8 billion a year earlier. Destatis explains that more economically significant companies had filed for insolvency in the earlier period. More frequent cases therefore do not necessarily mean a larger aggregate sum of creditors’ claims.
? Corporate insolvency frequency: what does it measure?
Frequency is the number of court-registered cases per 10,000 companies in the relevant sector; it is not the probability that an individual bond will default. A filing enters the statistics after the court’s first decision, often about three months after submission. Creditors’ claims are not realised losses, and businesses closing for other reasons are not counted here.
Professional portfolio management
A plan for your portfolio. No rush.
Let’s discuss your goals, risk tolerance and time horizon. Find out how your portfolio would be built and managed.
The first conversation is free, with no obligation.
Year
What matters now
Fuel users need delivered diesel, not just another pledge
Transport-company shares and industrial corporate bonds are exposed to fuel bills and to how much of those costs companies can pass on to customers. If additional diesel actually reaches buyers, fuel users’ costs could fall. Slow delivery or another supply disruption, however, would keep pressure on profits and the cash available to repay debt.
Oil-producer shares face a different risk: more fuel reaching the market may ease conditions for their customers, while restored supply may weigh on crude selling prices. Refiners’ profits also depend on the gap between fuel selling prices and the cost of their feedstock. One blanket view of the energy sector would therefore be too broad. Specified additional volumes and delivery schedules would help distinguish genuine cost relief from merely improved expectations.
For consumer businesses, the question is whether caution is already reducing sales
The University of Michigan’s 9 October survey sends a different signal to sellers of major purchases and consumer-equity funds than to companies supplying everyday necessities. A car or household appliance is easier to postpone, while people may keep buying essential goods by switching to cheaper alternatives. These are possible patterns of demand, not company sales results already reported.
Consumer lenders also need to consider borrowers’ ability to repay. If price pressures eased, demand for major purchases could recover; if household incomes failed to keep pace with costs, risks to sales and credit losses would increase. Results from US bank JPMorganChase on 13 October will help assess borrowers’ finances, while US September retail-sales data on 15 October will show actual sales.
A higher yield for a new buyer is not the same as a gain on an existing bond
On 9 October, existing fixed-rate US Treasury bond prices could have come under pressure at maturities where yields rose. At the same time, a buyer of a new 2- or 10-year bond could have obtained a higher yield than on Thursday. For debt-funded property companies, refinancing costs matter; an existing fixed-rate loan payment does not change with daily market quotations.
If US September consumer-price data on 14 October showed weaker inflation pressure, longer-maturity bond prices could find support. More persistent price growth would strengthen the risk of expensive financing for both bonds and debt-sensitive equities. The US central bank’s policy-rate range set in September remains 3.75–4.00%; its next decision is scheduled for 28 October.
A company's ability to repay matters more than the insolvency headline
For holders of higher-risk European corporate bonds, the issue is not just the interest rate but whether the issuer will have enough cash to pay interest and principal. Bank and supplier shareholders, meanwhile, face customers’ late payments and potential credit losses. Sector statistics help identify where company finances deserve closer scrutiny, but do not replace an assessment of cash, debt maturities and customer concentration.
The smaller aggregate sum of claims is a counterweight, so more registered cases do not automatically imply equal pressure on every creditor. An opportunity could arise where a bond’s price already reflects its specific risk and the company has sufficient cash to meet its obligations. Germany’s final September inflation release on 13 October will update the cost assessment; it will not establish whether an individual borrower is solvent. That requires its results and actual payments.
For 12 October, a holiday closure is recommended for the US bond market, while US stock exchanges have no scheduled holiday. Japanese share trading is closed; some derivatives continue trading. Friday’s bond level should therefore not be treated as a measured Monday response to weekend news.
Year
What comes next
On 13 October, Germany will release final September inflation; US bank JPMorganChase will release quarterly results at about 14:00 Lithuanian time and discuss them at 15:30. Do price pressures and borrowers’ finances fit consumers’ poorer assessment of current conditions?
On 14 October, the IEA will publish its Oil Market Report, while the US Bureau of Labor Statistics will release September’s Consumer Price Index at 15:30 Lithuanian time. Do tight fuel supply and actual price growth reinforce the risk of expensive borrowing?
On 15 October, the IEA Governing Board will review stock-release actions. US September retail sales will be released that day at 15:30, followed at 19:00 by the US Energy Information Administration’s stocks for the week ending 9 October. Will additional diesel plans become specified volumes and dates, and is consumer caution already visible in sales?
The final Michigan October survey is due on 23 October at 17:00. The US central bank’s next decision is expected on 28 October at 20:00; the ECB’s follows on 29 October. Will new price and demand data justify changing interest rates or keeping them unchanged?
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.