30 days · Market review
Chip sales grew while borrowing became more expensive again
On 10 November, the US reported slower overall monthly price growth, but prices excluding food and energy did not slow. US bond yields rose that day. Across these 30 days, chip manufacturers kept growing revenue, while future profits had to cover more expensive financing and uneven relief in energy costs.
Period covered: 2026-10-13 – 2026-11-11Information as of 10 min read
October US prices and TSMC revenue, still awaited in the 9 November edition, have now been released. US yields rose, while today’s confirmed German inflation slowdown does not establish the same outcome for every country.
The US 3.75–4.00% target range retained in late October remains in force. A chip manufacturer’s sales do not establish that its equipment-buying customers have already earned a return on their investment.
30 days
What happened
By mid-October, higher energy costs had reached consumer prices
The US Bureau of Labor Statistics release on 14 October showed why oil matters beyond energy shares. Annual consumer-price inflation accelerated from 3.4% to 3.7% in September. Petrol prices rose 9.1% over the month and accounted for more than half of the overall monthly price increase. This left households with less money for other purchases while making the case for rapid interest-rate cuts more difficult.
Also on 14 October, the International Energy Agency reported that world oil supply had increased by 2.5 million barrels a day to 102.3 million in September. Recovering supply was an important counterweight, but the agency still described diesel markets as strained. More crude production does not necessarily mean that the right fuels are available everywhere: refining, logistics and regional supply disruptions also affect their prices.
? Consumer and producer prices: why can they diverge?
The consumer price index measures a basket of household goods and services, while the producer index measures businesses’ selling prices. Higher energy costs may reach customers later or only partly, so producer inflation is not a copy of future consumer inflation.
Strong chip-sector results did not stop every market setback
Dutch chipmaking-equipment supplier ASML reported third-quarter revenue of €11.662 billion on 14 October, compared with €9.326 billion in the second quarter. The company described strong customer demand, but interest in equipment for later years does not yet represent a complete flow of final orders and paid sales. This distinction matters to the equipment manufacturer and its suppliers as they plan additional capacity.
Taiwanese chip manufacturer TSMC reported third-quarter revenue of US$46.72 billion on 15 October. It forecast US$52.3–54.3 billion for the fourth quarter. These figures show a substantial existing business and an ambitious further sales plan, but forecast revenue has not yet been earned. A chip foundry’s revenue also does not prove that all its customers’ data centres are already generating a return on their investment.
On 15 October, market stress in South Korea triggered an automatic safeguard: after the broad KOSPI index fell at least 8% and remained there for a minute, trading was halted for 20 minutes at 12:38 local time. This describes a specific October session, not a November trading halt. A suspension temporarily pauses transactions but does not guarantee that prices will rise when trading resumes.
Chinese growth concealed a large gap between industry and construction
On 19 October, China reported that its real economy grew 4.5% year on year in the third quarter, compared with 4.3% in the second. However, property-development investment during the first nine months of the year was 20.6% below the preceding year’s level. The headline growth figure was therefore not equally favourable for industrial-equipment exporters, construction-material suppliers and property developers.
Central banks took different paths at the end of October
On 28 October, the US Federal Reserve retained its 3.75–4.00% target range, while the Bank of Canada raised its policy rate by 0.25 percentage points to 2.50%. The European Central Bank kept its deposit rate at 2.50% on 29 October. These were different decisions for different economies, not a single worldwide phase of cheaper borrowing.
The Bank of Japan retained its 1.25% policy rate on 30 October. It also announced that it would increase the pace of disposals of its exchange-traded-fund holdings from January 2027. This was a future plan, not additional selling already completed in November. Australia subsequently raised its rate to 4.85% on 3 November and the Bank of England to 4.00% on 5 November, each by 0.25 percentage points.
November’s equity decline extended beyond technology
On 5 November, the US S&P 500 price index fell 4.36% and the Nasdaq Composite lost 5.52%. Japan’s Nikkei 225 dropped 5.96% on 6 November. These are specific session price changes, not returns for this entire 30-day period. Declines in the broader US index and Japan matter to an investor expecting to reduce risk merely by spreading money across several equity funds.
New political intentions also followed the US election on 3 November: on 5 November, Senate Democratic leader Chuck Schumer listed stopping tariffs and protecting households from electricity-infrastructure costs shifted onto them because of concessions to data centres. These were not enacted laws. A possible redistribution of expenses could change data-centre investment returns, but it does not establish a single cause for the broad equity sell-off.
The latest economic releases did not point in one direction
US October figures released on 6 November showed 165,000 additional non-farm payroll jobs and unemployment of 4.1%. The combined August and September payroll increases were revised upwards by 84,000. This is an important counterweight to the assumption that household incomes are already weakening sharply, but it also prevents rate cuts from being treated as an automatic response to falling shares.
China’s October price release on 9 November added another divergence: annual consumer-price inflation slowed from 0.9% to 0.7%, while producer-price inflation accelerated from 5.0% to 5.7%. September figures released in Europe on 5 November had already shown a 30.8% annual increase in producer energy prices. Resilient demand therefore had to be assessed alongside business costs that were unevenly distributed.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
On 10 November, US prices left the risk of higher rates intact
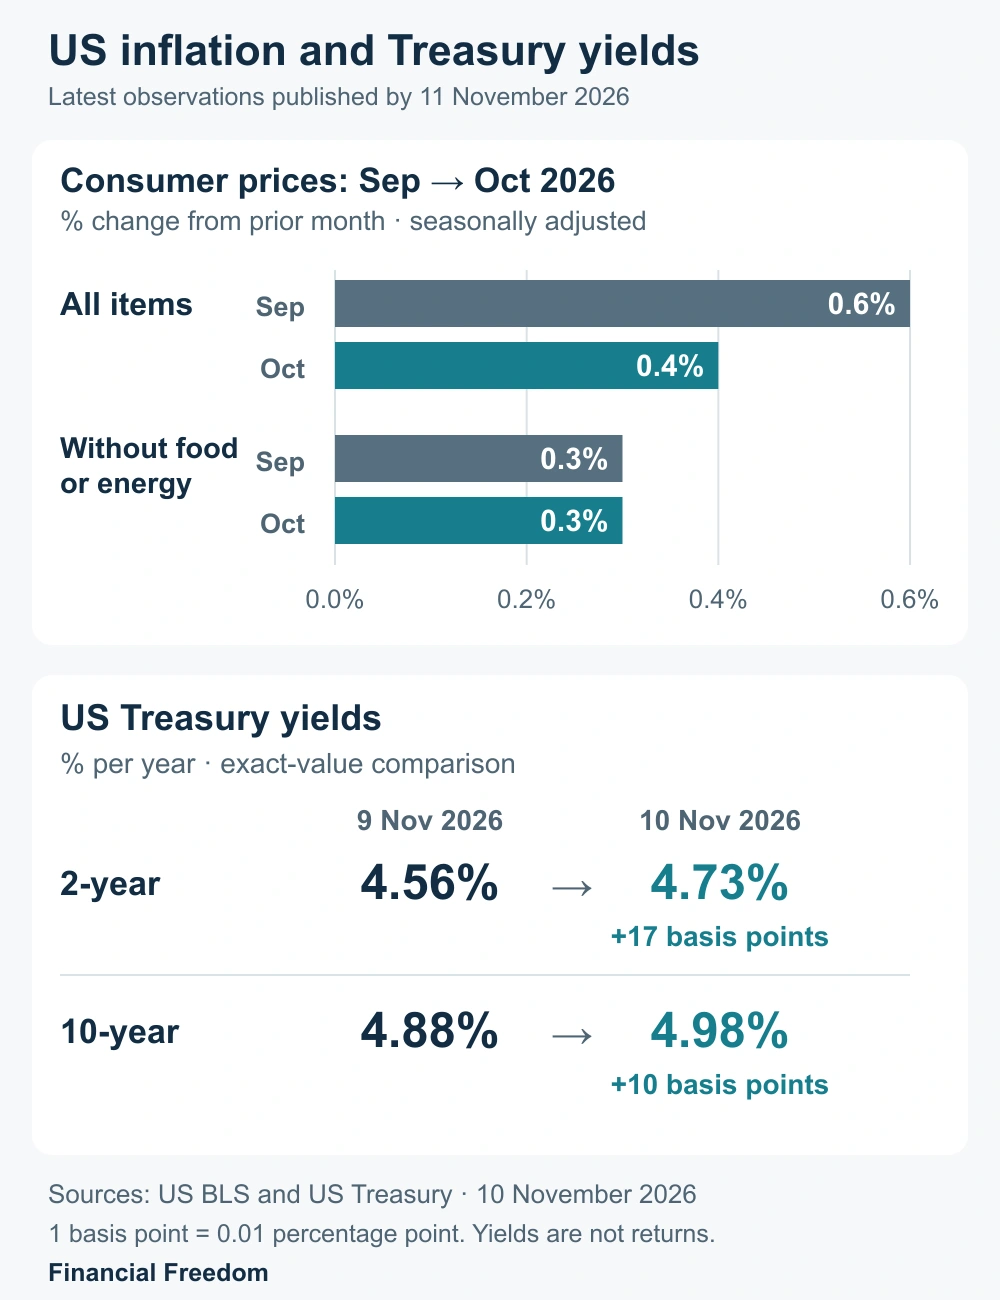
The US Bureau of Labor Statistics reported on 10 November that consumer prices rose 0.4% in October from September, after adjustment for normal seasonal patterns. September’s increase had been 0.6%. But prices excluding food and energy rose 0.3% for a third consecutive month. A slower headline increase therefore did not show the same easing across all sources of inflation.
? Monthly inflation: why is this not an annual comparison?
These changes compare the consumer basket with the preceding month after seasonal adjustment. Most October annual comparisons lack an October 2025 index because survey data were not collected then; annual inflation cannot be derived from a single monthly reading.
Federal Reserve governor Christopher Waller spoke that same day, before the price release, saying he leaned towards supporting a 0.25-percentage-point rate increase in December. If the monthly core increase were around 0.3% or higher, he thought a 0.50-percentage-point rise should also be considered. The later reading matched his stated condition, but this remained one official’s position, not a committee decision or a market probability.
The US Treasury’s indicative ten-year yield rose to 4.98% on 10 November from 4.88% on 9 November, reversing the direction of the preceding completed week. The Nasdaq Composite price index fell 0.74% that day. Their timing illustrates the tension between financing costs and equity valuations, but does not establish that the price release alone caused every transaction.
? Yield: is this change a bond fund’s return?
US Treasury indicative yields are calculated from market prices for consistent maturities and expressed as annual percentages. One basis point is 0.01 percentage point. A yield change is not a fund return; other things equal, a higher yield reduces the price of an existing fixed-rate bond.
Chip-manufacturer sales provided a concrete counterweight
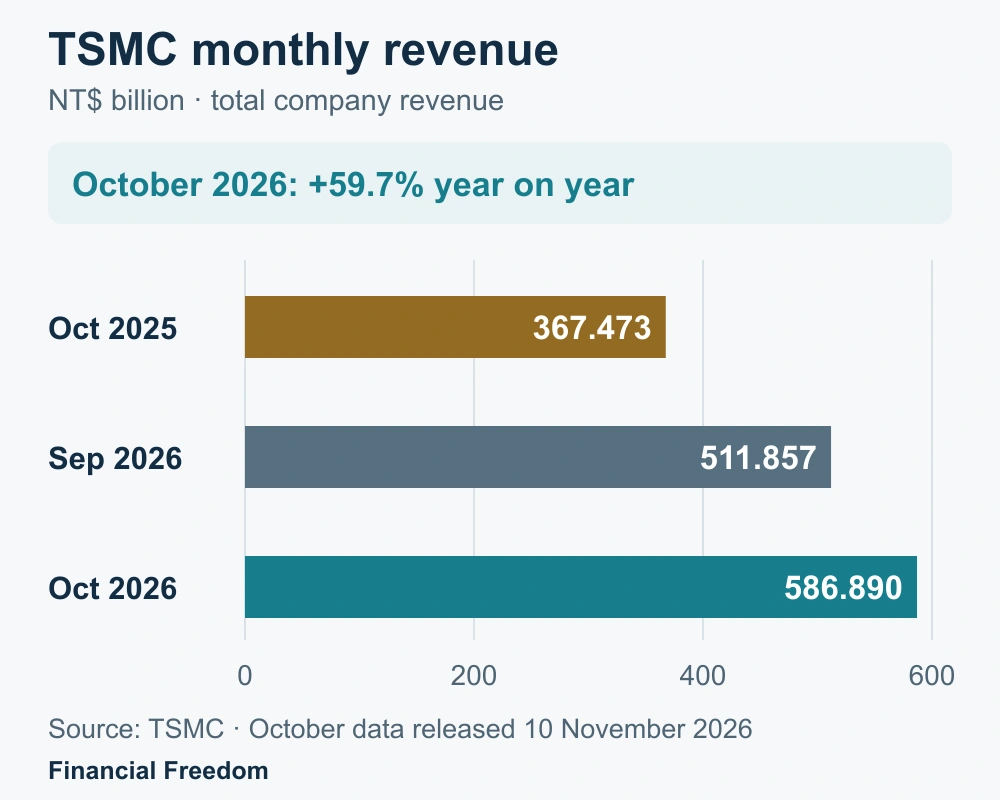
Taiwanese chip manufacturer TSMC reported on 10 November that October revenue reached 586.890 billion New Taiwan dollars. This was 14.7% higher than September and 59.7% above October 2025. Actual sales in the new quarter add to the earlier quarterly results, but they are neither monthly profit nor a measure of all its customers’ investment payback.
Japan’s Nikkei 225 closed 1.31% higher on 11 November than in the preceding session. This is a dated Japanese price-index recovery, not a return for all Asian markets or this entire review period. These US and Japanese sessions therefore moved in different directions.
Energy supply improved while October’s average price remained high
On 10 November, the US Energy Information Administration estimated that Middle Eastern oil-production shut-ins averaged about 2.5 million barrels a day in October, against 10.9 million at the May peak. Smaller disruptions are an important counterweight to supply fears. Nevertheless, Brent averaged US$124 a barrel in October, compared with US$114 in September. A monthly average is not today’s quotation and does not reprice every fuel contract at once.
Today Germany confirmed its previously reported inflation slowdown
Germany’s statistics office confirmed on 11 November that annual consumer-price inflation slowed to 2.8% in October, with inflation excluding food and energy at 2.1%. These were final figures confirming the earlier preliminary estimate, not an unexpected revision of that earlier estimate. Fuel-tax relief effective from 1 October helped reduce fuel expenses; its effect cannot automatically be extrapolated to every future month or the entire euro area.
30 days
What matters now
Sales growth matters alongside what the business retains
The technology story over this period requires a distinction between three things: an equipment supplier’s sales, orders received by the factory buying that equipment, and the eventual data centre’s earnings. The first may already appear in revenue while the third still requires years and further investment. Equipment and chip suppliers can therefore grow while their customers have less cash available. This is an economic relationship, not a finding about every individual company’s current cash flow.
An opportunity would arise if strong demand persisted while construction, electricity and financing costs remained manageable. The opposing risk is that weaker final usage or additional expenses reduce the future profits underpinning share prices. Semiconductor manufacturers, software suppliers and data-centre owners should therefore not be treated as completely interchangeable investments.
Energy and interest rates affect several portfolio exposures at once
More expensive fuel can support some energy producers’ revenue while making profitability harder for airlines, logistics companies and chemical manufacturers. Cheaper commodities could reverse that direction. A company’s ability to pass expenses on to customers matters: a long-term fixed-price sales contract and flexible pricing create different risks even within the same industry.
For bonds, maturity matters: longer-dated fixed-rate debt generally loses more value when market yields rise. Shorter maturities reduce this price exposure but require earlier reinvestment of returned principal. The borrower’s creditworthiness and the currency remain separate risks.
Currency remains a separate risk for a euro investor: the euro–dollar exchange rate can increase or reduce a dollar-denominated result. Several different global equity funds may also hold the same large technology companies. Portfolio diversification is therefore better assessed through actual companies, industries, currencies and debt maturities than through the number of funds owned.
30 days
What comes next
13 November: prices and output answer different questions
The US October producer-price release is due on 13 November at 15:30 Lithuanian time. It will show whether price pressure persists in goods and services sold by businesses, but is not a direct forecast of future consumer inflation. The next estimate of euro-area third-quarter economic growth, due the same day, will help assess whether demand withstood more expensive energy.
17–18 November: chip profits and an earlier rate discussion
NVIDIA’s quarterly results are scheduled for late on 17 November Lithuanian time, with its results discussion starting at 00:00 on 18 November. They will test how chip sales translate into profit and what signals the company sees in future orders. The Federal Reserve’s October minutes, due at 21:00 on 18 November, will reveal earlier discussions, not the committee’s response to the 10 November price figures.
December: a rate decision and another month of sales
On 8–9 December, the Federal Reserve will consider the 3.75–4.00% target range still in force. TSMC’s November revenue, scheduled for 10 December at 07:30 Lithuanian time, will show whether October’s sales strength continued. US November consumer prices follow at 15:30 that day, after the Fed decision; they therefore cannot be described as an advance signal for that meeting.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.