Week · Market review
10–16 September: energy and interest rates test profits
Over seven days, the energy story became more tightly linked to interest rates and corporate profits. Europe’s rate increase is now in force, US Treasury yields reached 5%, and New York factories report slower activity growth and dearer inputs. Microsoft’s dividend increase counters the idea that every technology expansion is financially weak. This review covers the calendar days of 10–16 September, not a separate completed trading week.
Period covered: 2026-09-10 – 2026-09-16Information as of 11 min read
On 15 September, the US ten-year Treasury yield reached 5.00%. A new New York survey showed slower activity growth and greater price pressure. Microsoft raised its future dividend, while Europe’s rate increase takes effect on 16 September.
Energy delivery, borrowing costs and cash left after investment remain the common question. Higher sales do not automatically mean higher profits. The US central bank’s decision is still due this evening; its outcome is unknown in this morning’s review.
Week
What happened
The starting backdrop before 10 September: energy volumes and forecast dates
Unreliable energy supply continued to shape the backdrop at the start of the week. A company needs to know more than the price of oil: will the cargo arrive on time, and how much will delivery cost? Bigger fuel bills squeeze transport and industry, leaving households less money for other goods. A disruption announcement alone is not enough to calculate the volume of oil lost or the change in a particular company’s profits.
The outlook published by the US Energy Information Administration on 9 September added a longer-term perspective. Its model inputs, however, had been collected by 3 September. Events announced later therefore cannot be described as the reason for that forecast revision. Nor is a forecast average price for a future period today’s exchange price. For an investor, this distinction separates a possible scenario from a price move that has already happened.
10 September: Europe approved a decision taking effect on 16 September
The European Central Bank decided to raise all three key interest rates by 0.25 percentage points. The deposit facility rate rose from 2.25% to 2.50% on 16 September. This is the rate paid on banks’ overnight deposits at the central bank, not a household deposit or mortgage offer.
The decision matters because higher rates can help restrain price growth while making new investments harder to finance. Companies that must soon refinance debt need to assess the terms of their next loan. A variable-rate loan payment changes according to its specific contract and reset date, not automatically alongside the central bank. Higher rates can help banks’ income, but they do not erase the risk that some customers will find repayment harder.
11 September: US headline price growth accelerated, but not every measure worsened
US consumer prices rose 0.4% in August from the previous month after adjustment for normal seasonal patterns, compared with 0.1% in July. Annual inflation remained at 3.4%. At the same time, annual inflation excluding food and energy slowed from 2.5% to 2.4%. One release therefore offered both a warning about faster price growth in the latest month and a counterbalancing signal of slower core inflation.
What is the Consumer Price Index?
The Consumer Price Index summarises the prices of a basket of goods and services bought by households, using consumption weights. The monthly change shows the latest pace, while the annual change compares with the same month of the previous year. It is not each family’s personal change in spending. Removing food and energy helps track a more stable price trend, but does not mean households avoid these costs.
11 September: new wealth data explained another side of economic resilience
Federal Reserve statistics showed that the net worth of US households and nonprofit organisations reached 195.9 trillion US dollars in the second quarter, up about 7% from the previous quarter. Equities held directly and through funds and other vehicles were worth 74.0 trillion dollars, while owner-occupied housing was worth 49.8 trillion. These are end-June asset balances, not September trading results or cash in bank accounts.
11 September: supply problems remained larger than demand weakness
The International Energy Agency’s 11 September forecast projected a larger fall in oil supply than in demand this year. This is a forecast, not the final annual result.
Lower demand does not automatically mean cheaper oil. If the volume reaching buyers falls faster, fuel bills can remain high even as the economy slows. This can help an energy producer only if it can deliver its output. For a haulier or an energy-buying factory, the same situation raises costs.
14 September: more expensive government debt did not mean a shortage of buyers
France’s ten-year market yield indicator, published by its Treasury, stood at 4.48% on Monday, compared with 4.19% on 1 September. At the short-term Treasury bill auctions on the same day, 14 September, bids were 2.78–4.26 times the amount issued. These are instruments of different maturities: the auction does not prove equally strong demand for ten-year debt.
These facts help distinguish two situations. Borrowing can cost more even when there is no shortage of willing lenders. The price of new borrowing matters to the government budget, while fluctuations in market value matter to an existing holder of a longer-term bond. A higher yield is neither proof of insolvency nor a promise of risk-free returns.
Investment consultation
Do your investments work together?
Review where your money is invested, how much depends on a single market and whether your plan fits your goals. Leave with clearer next steps.
See the consultation process and terms on the registration page.
Week
What matters now
15 September: the ten-year US Treasury yield reached 5%
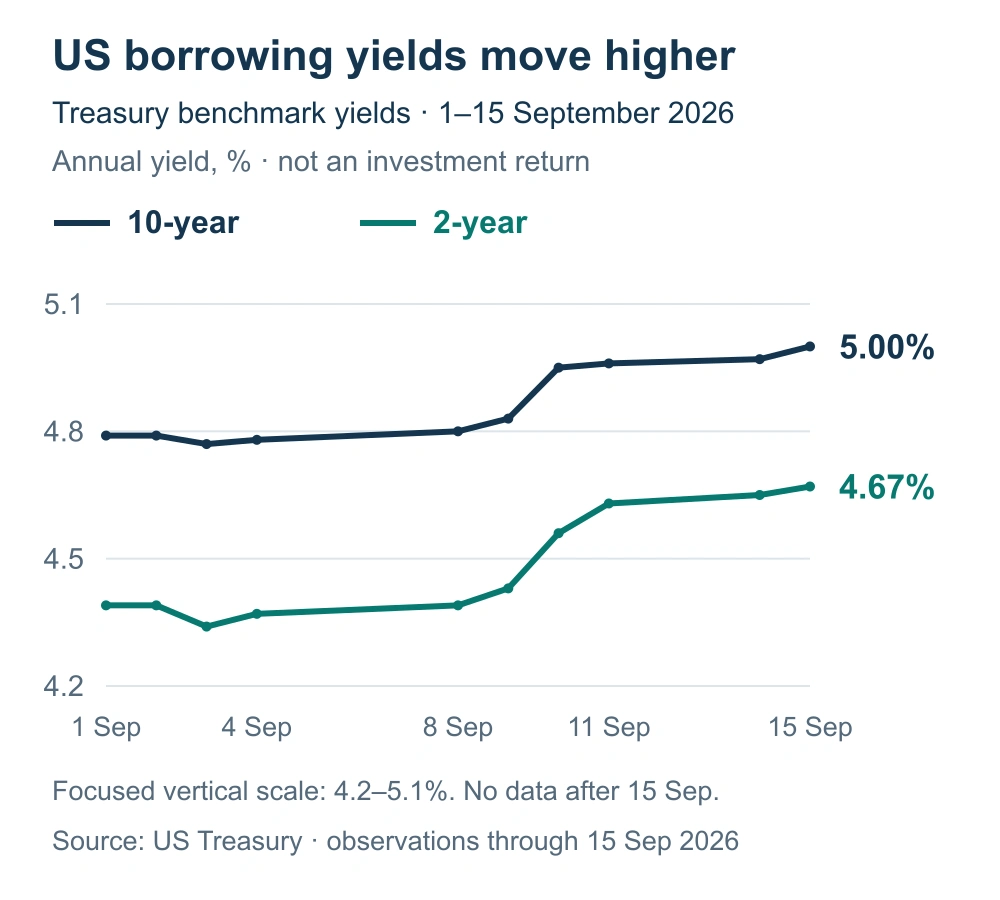
Before the US central bank’s decision on the evening of 16 September, the bond market was already signalling more expensive long-term financing. The ten-year Treasury yield reached 5.00% on 15 September, compared with 4.97% on 14 September and 4.78% on 4 September. The last session’s rise was small, but part of a larger move over several sessions. The two-year yield was 4.67% on 15 September and the thirty-year yield was 5.36%.
A new bond buyer sees a higher yield, while the holder of an older fixed-rate bond may see a lower market price. A company refinancing debt now may face a higher interest bill. For technology and property projects, what matters is not just future revenue, but the cost of waiting for it. These market moves cannot be attributed to a decision that has not yet been announced.
? What does a 5% bond yield mean?
A bond yield relates its price to future payments. These are annual yields for standard maturities calculated by the US Treasury from market quotations. They are not that day’s earnings, the US central bank’s policy rate or a return guaranteed to every investor. A euro-based investor’s result may also change with the dollar exchange rate.
Factories report slower growth in orders, while inputs keep getting dearer
In the New York State manufacturing survey released on 15 September, the general business conditions index fell from 20.6 points in August to 7.6 in September. The prices paid index rose from 58.6 to 63.1. This is a regional warning, not evidence of a contraction across all US manufacturing: activity was still growing, but cost pressure was not easing.
A factory finds it harder to protect profits if material bills rise faster than its ability to raise selling prices. Orders can still help equipment suppliers, while buyers exposed to energy costs and debt face the other side of the trade. The next broader production and sales figures will show whether this regional signal is repeated.
? How should the New York manufacturing survey be read?
The Empire State Manufacturing Survey compares the shares of companies reporting an increase and a decrease in each measure. Zero separates a balance towards growth from a balance towards decline. A prices index of 63.1 points does not mean that prices rose 63.1%. This is not a purchasing managers’ index, for which the usual threshold is 50 points.
A higher dividend does not tell us how much cash remains after expansion
Software and cloud company Microsoft announced on 15 September that its quarterly dividend would rise from $0.91 to $0.98 per share, or about 7.7%. Payment is scheduled for 10 December. This is a future distribution, not income already received. The decision shows that heavy expansion and returning cash to shareholders can coexist, but a dividend alone cannot establish whether investment is paying off.
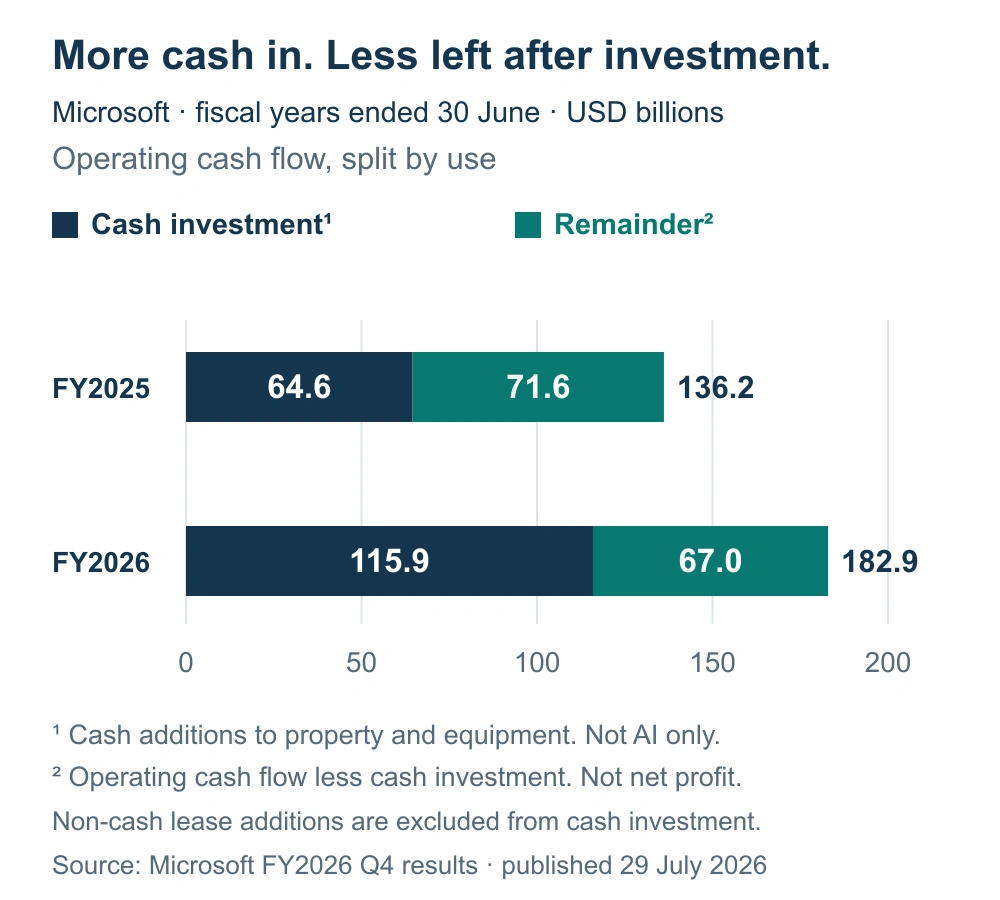
In the latest annual cash-flow statement, released on 29 July for the year ended 30 June, operating cash flow increased from $136.2 billion to $182.9 billion. Cash additions to property and equipment rose from $64.6 billion to $115.9 billion. They absorbed about 63% of operating cash, compared with 47% a year earlier. The calculated remainder after those outlays fell from $71.6 billion to $67.0 billion.
These investments are not all artificial-intelligence spending and exclude non-cash finance-lease additions. The remainder is not net income or cash reserved exclusively for dividends. The opportunity for investors is new capacity turning into profitable services; the risk is revenue arriving slowly when equipment and electricity already have to be paid for. Operating cash, actual investment payments and lease commitments matter next, not revenue growth alone.
Europe's rate decision is now in force, while the trade recovery remains uneven
The European Central Bank’s decision of 10 September takes effect on 16 September. The rate paid on banks’ overnight deposits is now 2.50%, up from 2.25%. This implements an earlier decision rather than delivering a fresh surprise this morning. A loan payment depends on its contract and reset date, so not every borrower’s bill changes today.
Euro-area trade figures for July, released on 15 September, provided a counterweight: nominal goods exports rose 9.0% year on year and imports 7.9%. July’s surplus was €14.2 billion, but the January–July surplus totalled only €17.0 billion, compared with €92.8 billion a year earlier. These are non-seasonally adjusted goods values. One better month has not offset the earlier weakness, and higher sales values alone do not prove larger volumes or profits.
Lithuania is expected to grow, but purchasing power still matters
The Bank of Lithuania’s forecast published on 15 September projects real economic growth of 2.7% in 2026, 2.4% in 2027 and 3.1% in 2028. Average annual inflation is forecast at 5.1%, 3.1% and 2.6%, respectively. These are forecasts, not completed annual results. A smaller one-off consumption boost from withdrawals from the second-pillar pension system would also mean a smaller subsequent reversal.
Domestic retailers depend on household purchases; Baltic exporters also depend on orders from abroad. Their prospects need not move together. Inflation erodes the purchasing power of money held for a long time without interest, but a forecast alone does not justify hastily taking more risk. What matters most is when the money will be needed and how much fluctuation in value can be tolerated.
15 September: China’s factories strengthened, but consumers were slow to spend
August year-on-year changes released on 15 September: China’s industrial output grew 5.2% in real terms, while retail sales increased 0.4% in nominal terms.
The unevenness itself matters to investors. An equipment or technology supplier can receive more orders while a business dependent on household spending experiences sluggish demand. China’s headline growth rate alone therefore cannot tell us how a European exporter or a commodity company will perform. We need to know who its customers are and what they use its products for.
? What are we actually comparing in China’s data?
Industrial value added measures the value created in production, and its real growth rate removes the effect of prices. Retail sales here measure the monetary value of sales at current prices. They do not cover all household spending, because many services fall outside this measure. Both percentages compare with August of the previous year, but their coverage and price adjustments differ.
The influence of equities extends beyond the stock market
Wealth statistics offer another explanation for why demand need not weaken as quickly as an investor watching only borrowing rates might expect. Someone seeing a higher value for their investments may feel more confident about spending. That is a possible transmission channel, not a guarantee of every household’s behaviour. Equity ownership is unevenly distributed, and wealth gains include both revaluations and transactions.
Both sides matter to a portfolio. Resilient demand supports consumer-goods and services companies, but an equity correction could undermine some customers’ confidence. Higher selling prices help energy producers if they can deliver their output; the same prices raise costs for energy users. For a euro-based investor, the dollar exchange rate also changes the result from US assets. A higher US interest rate alone does not guarantee a stronger dollar.
Week
What comes next
The evening of 16 September: the US decision is still ahead
The Federal Reserve, the US central bank, is already holding its 15–16 September meeting. The decision is scheduled for today at 21:00 Lithuanian time and the press conference at 21:30. At this morning’s information cutoff, the outcome is unknown and the federal funds target range maintained on 29 July remains 3.50–3.75%. The outcome must not be presented as something that has already happened.
Before that, US August retail sales and import-price data are scheduled for 15:30 Lithuanian time. They will help show whether demand is withstanding higher prices. A more restrictive central bank signal than markets expect could support yields and put pressure on highly valued shares; a softer signal could ease that tension. These are conditional scenarios, not guaranteed price directions. US industrial production on 18 September will provide a broader check than one regional survey.
What would change the week’s conclusion?
A broader recovery in Chinese consumption would benefit not only factories but also retailers and services. In Europe, lower energy bills would leave more income for other spending. Until several indicators confirm that improvement, it helps investors to distinguish the seller from the buyer and the lender from the borrower. The same changes in interest rates and energy prices affect their results in different directions.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.