
Year · Market review
Year: rate cuts gave way to a renewed test of costs
Across twelve months, the direction of rates, trade rules and the reliability of energy supply all changed. Technology companies earned more, but their customers needed substantial investment to expand. The latest rise in US yields reinforces the year’s broader lesson: a growing economy does not protect investors from overpaying for assets or taking on too much debt.
Period covered: 2025-09-26 – 2026-09-25Information as of 14 min read
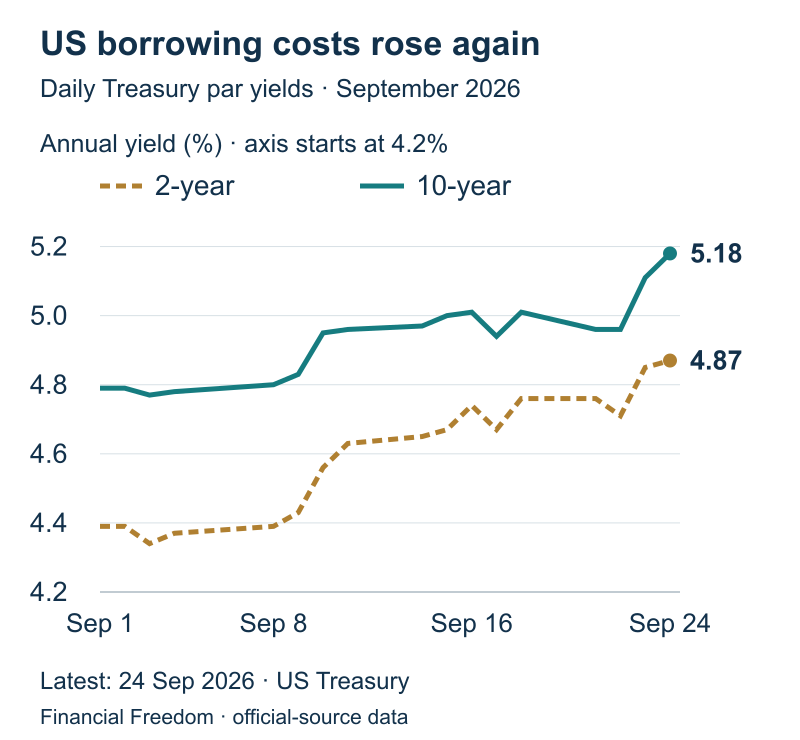
Since the previous edition, the US ten-year yield rose from 4.96% on 22 September to 5.18% on 24 September. The business survey released on 23 September showed faster US expansion, while benefit claims on 24 September did not show a sudden surge in redundancies. New energy and OECD evidence shows that resilient demand, thin fuel stocks and slower European growth can coexist.
The distinction between a company’s sales, its profit and the price an investor pays still matters. Higher revenue does not always cover energy, labour and debt costs. A higher bond yield does not guarantee a short-term return, and an interest-rate decision cannot by itself restore energy supply.
Year
What happened
Autumn 2025: US interest rates fell while Europe opted for a pause
Before this rolling period began, on 17 September 2025, the Federal Reserve cut its target range from 4.25–4.50% to 4.00–4.25%. That is the starting background, not an event after 26 September. It cut the range by another quarter point on both 29 October and 10 December, reaching 3.50–3.75%. Each decision took effect the following day.
Lower interest rates helped some borrowers, but their benefits cannot be separated from the reason for the cuts. If a central bank cuts rates because it sees weaker demand, a company’s cheaper loan may be offset by poorer sales. That is why the simple rule that “rates were cut, so that is good for shares” does not explain the market’s entire reaction.
During the autumn, the European Central Bank kept the rate paid on banks’ overnight deposits at 2.00%. Its 11 September decision was announced before this rolling twelve-month period began, but established its starting backdrop. The rate remained unchanged at the October and December meetings. The US and the euro area were therefore already following different paths.
November: trade gained some breathing room, but not an end to every barrier
On 1 November, the US announced the terms of an agreement with China providing for reductions in some tariffs and a suspension of rare-earth export restrictions from 10 November. This was an important signal of relief for supply chains. Rare earths are used in a range of industrial and technological equipment, so the availability of these materials matters to more than just their producers.
However, temporary relief is not a permanent, unchanging rule. A factory needs to know when a component will arrive and what its final cost will be. Uncertainty encourages companies to hold larger inventories or seek a more expensive alternative supplier. The November decision therefore cannot automatically be presented as the tariff applying to all goods today: subsequent measures have their own legal bases and conditions.
January 2026: switching energy suppliers became a concrete plan
On 26 January, the Council of the European Union approved a gradual phase-out of Russian gas imports. A full ban on liquefied natural gas is scheduled from the beginning of 2027, and on pipeline gas from autumn 2027. These are future deadlines with transition periods, not a halt to all imports on that January date.
This decision turned diversification into a matter of contracts and infrastructure. Other suppliers, ships, terminals and reserves were needed. Over time, a wider choice of suppliers may reduce dependence, but the transition itself also costs money. Investors need to distinguish the long-term benefits of resilience from the near-term bills for energy and infrastructure.
Meanwhile, the US central bank was in no hurry to continue the autumn cuts. The 3.50–3.75% range remained unchanged at its January, March and April meetings. Europe’s February, March and April decisions also maintained the 2.00% deposit facility rate. Earlier cuts were not a promise that every subsequent meeting would follow the same pattern.
February: the legal basis for tariffs changed
On 20 February, the US Supreme Court ruled that the International Emergency Economic Powers Act does not authorise the president to impose tariffs. The decision restricted a specific legal basis. It did not mean that all US import tariffs disappeared, because other measures relied on different laws.
On the same day, the administration announced a temporary 10% import surcharge, with exemptions, under a different section of the Trade Act. The proclamation specified a start on 24 February and a 150-day period until 24 July. This is a historical measure, not a tariff automatically applying to all imports today.
For businesses, changes like these mean having to recheck a product’s origin, classification code, delivery date and exemptions. An importer uncertain of the final cost may delay an order or hold more inventory. Even a politically favourable headline therefore does not always immediately reduce a company’s costs or increase its sales.
February's results showed that technology demand was more than a promise
On 25 February, chip designer NVIDIA reported results for its financial year ended 25 January. Revenue reached $215.938 billion, while net income under US accounting standards was $120.067 billion. Both figures were 65% higher than in the company’s previous financial year. These are results for a completed period, not a forecast for calendar year 2026.
This matters to the longer story: technology suppliers were generating visible, actual earnings well before the summer results season. But profit does not answer the question of an investment’s price. Even a successful company may be valued on very high expectations for the future that subsequently prove harder to meet.
Spring: geopolitical risk became an oil delivery problem
The war in the Middle East that began on 28 February disrupted oil shipments through the Strait of Hormuz. On 11 March, International Energy Agency member countries agreed to make 400 million barrels of emergency oil reserves available to the market. This was the largest coordinated release amount in the agency’s history. The decision was a commitment to release reserves, not the release of the entire volume in one day.
Reserves can buy time, but cannot replace commercial supply indefinitely. When reliable deliveries are lacking, the effects spread from the oil market to fuel, transport, chemicals and household purchasing power. More expensive energy can simultaneously raise inflation and weaken growth. A central bank faces an uncomfortable choice: raising interest rates does not produce additional oil, but cutting them may stimulate demand at a time when supply is constrained.
May: the story of global trade was not only one of closing borders
On 1 May, provisional application of the trade agreement between the European Union and the South American Mercosur countries began. Tariffs on some goods were reduced or removed. This marked a move from negotiations to applicable trade preferences, but was not yet the full, finally ratified partnership agreement.
European exporters gained opportunities to reach buyers on more favourable terms. For importers, a wider choice may help reduce dependence on a single supplier. At the same time, greater competition puts pressure on more vulnerable sectors. Actual orders and the use of trade preferences ultimately reveal the investment significance, not just the headline on the day an agreement is signed or takes effect.
June and July: Europe's interest rate direction reversed
On 11 June, the European Central Bank announced a 0.25 percentage point rate increase. The deposit facility rate rose to 2.25% from 17 June. It was left unchanged on 23 July. The US maintained its 3.50–3.75% target range at the 17 June and 29 July meetings. US cuts had therefore given way to a pause, while Europe had already turned towards higher rates.
The 18 June memorandum between the US and Iran raised hopes of normalising supply. But the International Energy Agency’s 10 July report already described ceasefire breaches on 7–8 July. Its August edition showed weaker oil export flows in July. An agreement and its implementation proved to be two separate stages that matter to investors.
On 23 July, the European Union expanded its energy and financial sanctions against Russia. The Office of the US Trade Representative announced a decision concerning 60 economies under Section 301 of the Trade Act on the same day. Tariffs depended on the product and applicable conditions; this was not an automatic extension of the temporary surcharge announced in February. Over the year, both supply routes and the rules governing what buyers pay for goods changed.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
Summer: the supplier's profits grew while customers faced the expansion bill
On 26 August, NVIDIA reported revenue of $96.221 billion for the quarter ended 26 July. Revenue was 106% higher and operating profit 124% higher than a year earlier. This result confirmed that demand for the supplier remained real. Its customers, however, pay for equipment, data centres and electricity infrastructure before receiving all their expected revenue.
In late July, Microsoft reported that it generated $55.4 billion in operating cash flow during the quarter ended 30 June and spent $35.8 billion in cash on purchases of long-term assets. In Oracle’s quarterly results released in September, capital expenditure already exceeded operating cash flow. These are not identical businesses, but the comparison shows why the technology story requires monitoring more than revenue growth.
Early September: prices brought attention back to interest rates
On 9 September, the US Energy Information Administration raised its forecast for the average Brent price in the second half of the year to around $90 per barrel. The publication used model inputs finalised by 3 September. It therefore does not measure the impact of later military reports in September and is not the latest exchange price.
On 10 September, the European Central Bank announced another 0.25 percentage point rate increase. On 11 September, the US Consumer Price Index showed annual price growth of 3.4% in August, unchanged from July. Seasonally adjusted monthly growth increased from 0.1% to 0.4%. However, annual growth in the basket excluding food and energy slowed from 2.5% to 2.4%. Monthly growth in this basket nevertheless increased from 0.2% to 0.3%. The conclusion is therefore not that “all price indicators are worsening”, but a more complex combination of differing rates of change.
The interest rate path in one place
The table shows every change to key US and euro area interest rates announced during this twelve-month period, together with the latest July decisions to leave them unchanged. It is not a list of every meeting. Europe’s decision announced on 10 September took effect on 16 September.
| Decision date | Region | Before | After | When it applies |
|---|---|---|---|---|
| 2025-09-17 | US | 4.25–4.50% | 4.00–4.25% | From 18 September |
| 2025-10-29 | US | 4.00–4.25% | 3.75–4.00% | From 30 October |
| 2025-12-10 | US | 3.75–4.00% | 3.50–3.75% | From 11 December |
| 2026-06-11 | Euro area | 2.00% | 2.25% | From 17 June |
| 2026-07-23 | Euro area | 2.25% | 2.25% | Left unchanged |
| 2026-07-29 | US | 3.50–3.75% | 3.50–3.75% | Range left unchanged |
| 2026-09-10 | Euro area | 2.25% | 2.50% | In effect from 16 September |
| 2026-09-16 | US | 3.50–3.75% | 3.75–4.00% | From 17 September |
For the US, the table shows the federal funds target range; for the euro area, it shows the specific deposit facility rate. On 16 September, Europe’s rate is already 2.50%. Compared with the start of this period after the US decision of 17 September 2025, the US range is now 0.25 percentage points lower. The European deposit rate rose 0.50 percentage points. The US increase of 16 September is included in the table.
? Consumer Price Index: why does the monthly change matter too?
The Consumer Price Index is compiled using the prices of goods and services and their weights in consumption. The annual change compares prices with the same month of the previous year. The seasonally adjusted monthly change helps show the latest pace. The annual figure can therefore remain unchanged even when prices rise faster in the latest month.
Mid-September: the timing of recovery became a key assumption again
The International Energy Agency’s 11 September forecast projects a larger decline in oil supply than in demand this year. This is a forecast, not a final annual result.
16–24 September: the relief in interest rates did not last
On 16 September the Federal Reserve raised its target range to 3.75–4.00%. An earlier European decision lifting the deposit rate to 2.50% took effect on the same day. The US ten-year yield fell to 4.96% on 21–22 September, but reached 5.18% on 24 September. A few days of easier financing conditions did not become a lasting direction.
The preliminary US Purchasing Managers’ Index, or PMI, reached 58.4 in the release of 23 September, compared with 56.0 in August. Initial unemployment benefit claims of 197,000 for the week ending 19 September, released on 24 September, reinforced the picture of resilience. These are newer signals, but neither a survey nor one week of claims is a final measure of an entire quarter’s growth.
? Purchasing Managers’ Index: what does the threshold mean?
The company survey compares activity with the previous month. Above 50 generally indicates expansion and below 50 contraction. A reading of 58.4 does not mean growth of 58.4%; the preliminary measure may be revised.
September’s decisions extended beyond the US and euro area. On 18 September the Bank of Japan set an overnight interest-rate target of 1.25%, effective from 24 September. On 17 September the Bank of England left Bank Rate at 3.75%. These different paths matter for Japanese bonds and yen-funded investments, as well as British companies’ borrowing costs.

Check your saving plan
Are your monthly contributions enough?
Compare your monthly contribution with your target future income. Adjust the time horizon to see how the amount you need changes.
This compares scenarios; it does not promise a future outcome.
Year
What matters now
23–25 September: growth did not remove cost risk
Crude stocks are rising, but fuel stocks offer less comfort
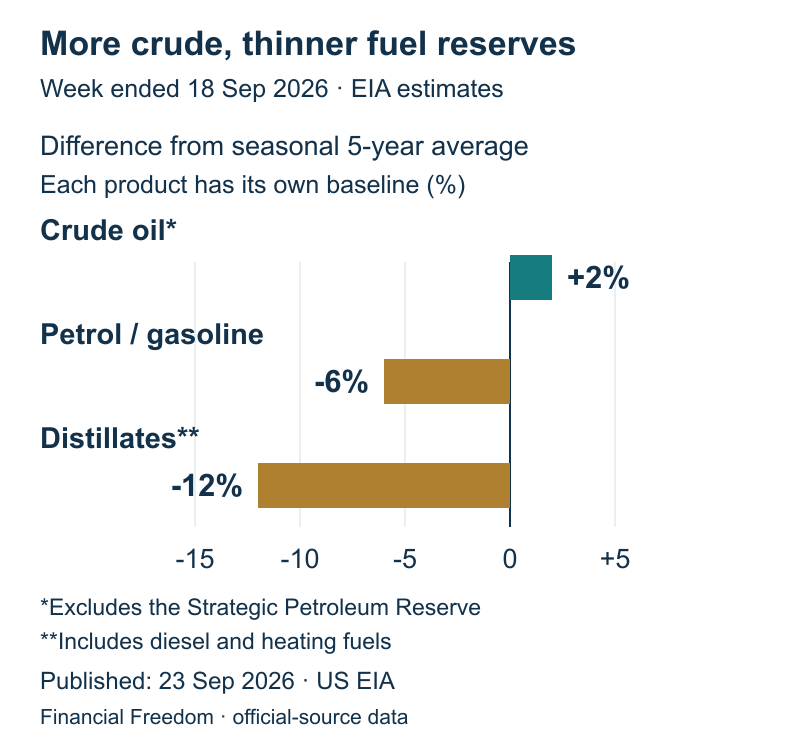
More crude oil in storage does not mean fuel-supply pressure is over. On 23 September the US Energy Information Administration reported that commercial crude stocks, excluding the strategic reserve, rose by 3.0 million barrels to 426.4 million in the week ending 18 September. They were around 2% above the five-year seasonal average. Petrol stocks, however, were 6% below their own average and distillate stocks 12% below theirs.
? Distillates and seasonal averages: what is being compared?
Distillates include diesel and heating-oil products. Each product’s stock is compared with its own average for the same time of year over five years. A 12% shortfall is neither a 12% rise in diesel prices nor the same share of total fuel demand.
Refining helps explain the gap. US plants processed 519,000 fewer barrels of crude per day than a week earlier, taking throughput to 16.8 million barrels a day. Less crude being processed can leave more in storage while replenishment of finished fuels slows. This does not mean every missing barrel must translate into a higher price, but it shows where there is less protection against another disruption.
For hauliers, airlines and energy-intensive manufacturers, the final fuel bill matters. For refiners, the difference between product selling prices and crude purchase prices matters, so rising crude inventories alone do not explain their profits. Higher refining throughput and replenished product stocks would create an opportunity for fuel-sensitive sectors. Another supply interruption before stocks recover is the risk. Subsequent EIA weekly reports will show whether the gap is narrowing.
Europe has less growth to absorb higher costs, while technology must earn a return on expansion
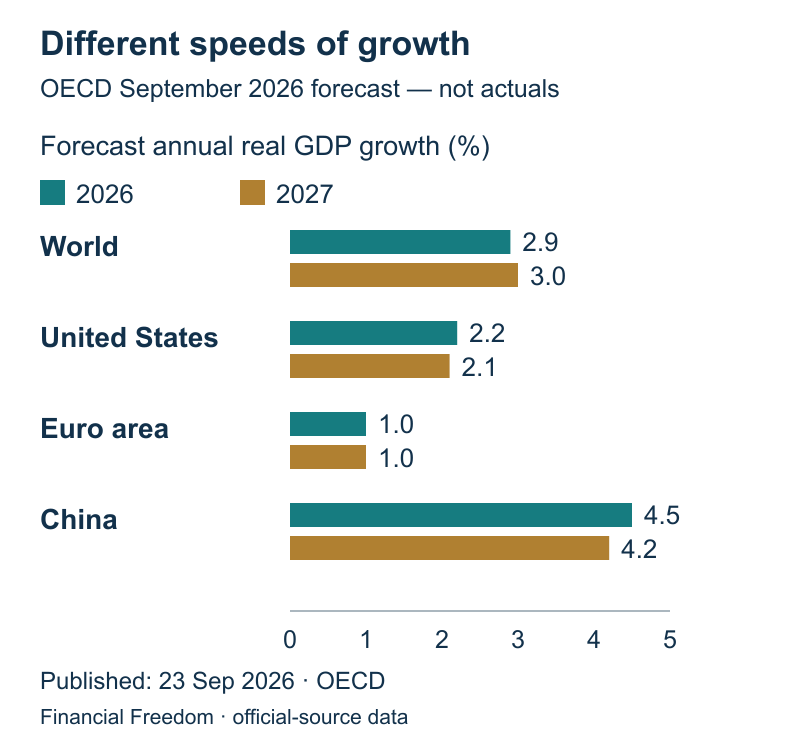
The world economy has not stalled, but regions face different cost pressures. On 23 September the Organisation for Economic Co-operation and Development forecast global growth of 2.9% in 2026. Its projections were 2.2% for the US and 1.0% for the euro area. These are forecasts from the same organisation, not final full-year results. Slower European demand leaves companies less room to pass higher energy and interest costs on to customers.
Revenue growth alone is therefore insufficient in European industry and retail. What matters is whether sales volumes also increase and profit margins hold up. Property businesses refinancing debt face an additional interest bill. An earlier European Central Bank decision raised its deposit rate to 2.50% from 16 September. That remains part of the backdrop, not a new decision today.
Investment in artificial-intelligence infrastructure provides a counterweight. The organisation identifies it as a support for growth and trade, but also warns about greater reliance on external funding. An equipment order can immediately lift the supplier’s revenue, while the data-centre owner still needs customers, electricity and enough cash flow to service loans. A supplier making a sale and its customer earning a return on that investment are not the same event.
The opportunity remains with companies able to support expansion with real orders and cash generated by their operations. Risk is greater where expensive construction and debt pay off only under an optimistic demand scenario. Memory-chip maker Micron’s results presentation on 30 September will help test data-centre demand and supply. It is an upcoming signal for the supply chain, not a promise that its shares or the technology sector will rise.
Two opposing forces are shaping portfolios
Resilient US demand supports business sales, but higher bond yields increase the cost of new finance. Energy adds another constraint: rising crude inventories do not guarantee the same improvement in finished fuels. It therefore makes little sense to label every bond unattractive or every technology company equally resilient. Debt maturity, cash reserves and the speed at which investment starts earning money differ.
In bonds, the higher starting yield must be weighed against potential price swings and the issuer’s ability to pay. In equities, revenue growth needs to be checked against margins and cash flow. Slower European growth makes it harder to pass costs on, while stronger US demand may keep rates elevated for longer. For a euro investor, exchange rates also affect unhedged dollar holdings; an unverified currency move is not presented as fact here.
A more favourable combination would be slower price increases, rebuilding fuel stocks and resilient corporate profit. The adverse combination would be expensive funding alongside weakening demand. The latest evidence does not make either outcome inevitable.
Year
What comes next
Three signals that could change the conclusion
- US prices and spending on 30 September. The August Personal Consumption Expenditures Price Index will test whether price pressure is easing; real spending will separate a greater volume of purchases from a larger bill.
- Micron’s results on 30 September. Memory-chip orders, pricing and planned investment matter alongside headline revenue growth. The results had not been released by this edition’s cutoff.
- The next US fuel-stock reports. Watch whether refining throughput, petrol stocks and distillate stocks recover together. An increase in crude alone will not answer the whole question.
? Personal Consumption Expenditures Price Index: what does it measure?
This index measures changes in the prices of goods and services consumed, including spending made by others on consumers’ behalf. Its weights adjust with the composition of spending, so it is not identical to the Consumer Price Index. Price growth and growth in real consumption answer different questions.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.





