
Quarter · Market review
Quarter: dearer finance added to energy disruption
Across 90 days, June’s hopes of normalising supply met uneven flows, changing trade rules and higher interest rates. Technology results showed real demand, while customers still faced the bill for financing expansion. Late-September evidence extends this story: US activity is strong and long-term borrowing is getting dearer.
Period covered: 2026-06-28 – 2026-09-25Information as of 11 min read
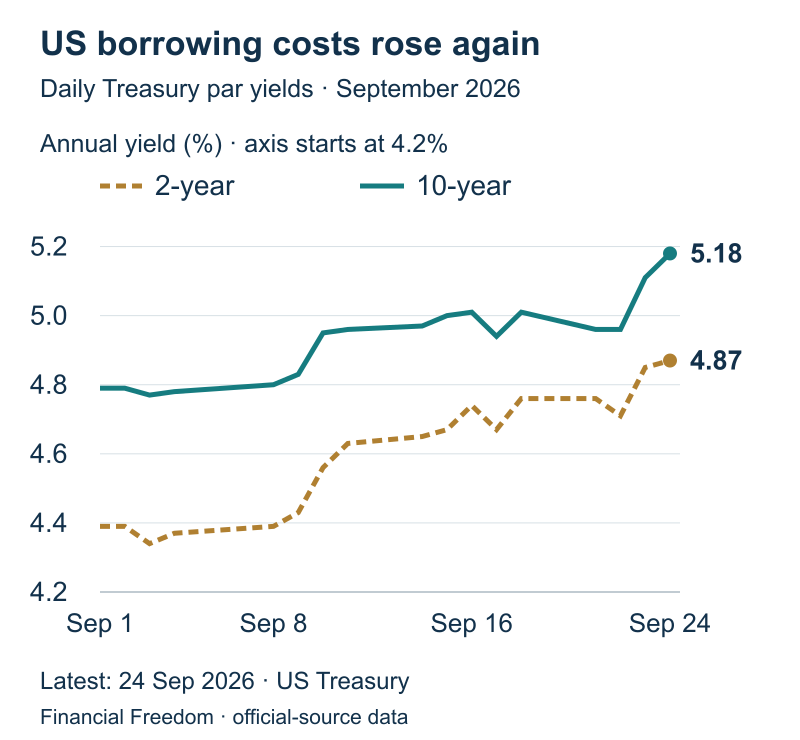
Since the previous edition, the US ten-year yield rose from 4.96% on 22 September to 5.18% on 24 September. The business survey released on 23 September showed faster US expansion, while benefit claims on 24 September did not show a sudden surge in redundancies. New energy and OECD evidence shows that resilient demand, thin fuel stocks and slower European growth can coexist.
The distinction between a company’s sales, its profit and the price an investor pays still matters. Higher revenue does not always cover energy, labour and debt costs. A higher bond yield does not guarantee a short-term return, and an interest-rate decision cannot by itself restore energy supply.
Quarter
What happened
The starting point: interest rates had already risen on 17 June
This 90-day period begins on 28 June. Before it began, on 17 June, the European Central Bank’s previously announced interest rate increase took effect. The rate on banks’ overnight deposits rose from 2.00% to 2.25%. These are the initial conditions before the period under review, not a new event within it.
Also on 17 June, the Federal Reserve left the federal funds target range at 3.50–3.75%. It made no change on 29 July. Europe also chose a pause on 23 July. For a business with debt, this meant that energy costs would not be offset by automatically and rapidly falling interest rates.
The starting backdrop: the 18 June agreement had not yet restored shipping
The US–Iran memorandum was presented as a route towards ending hostilities and reopening the Strait of Hormuz. The economic benefit depended on what happened after the signatures: could ships sail safely, would insurance be available, and would oil actually reach buyers?
More reliable deliveries would have reduced importing industries’ need to hold expensive inventories. Hauliers would have found fuel and route planning easier. But the agreement itself was not a statistical record of restored flows. July and August data later required a more cautious assessment of precisely this assumption.
July: the supply recovery was not sustained
The International Energy Agency’s 10 July review described a partial recovery in June flows and ceasefire violations on 7–8 July. Its 12 August report said Persian Gulf oil exports in July, including routes bypassing the strait, averaged 15 million barrels per day. That was 2.1 million, or about 12%, below June.
This comparison describes two monthly averages, not a one-day shipping halt. It showed that June’s hopes had not been enough to deliver a lasting improvement. US military statements on 5 and 8 September about strikes on Iranian tankers were a reminder that delivery security remained unresolved. A particular price move cannot be attributed solely to these statements.
23 July: trade rules and sanctions added to the planning burden
The European Union’s 21st sanctions package against Russia expanded restrictions on energy, financial services and the shadow fleet. For companies, this matters beyond politics: payment, insurance and cargo transport options change. But an announced restriction is not a measured fall in exports of the same size.
On the same day, the Office of the US Trade Representative announced measures concerning 60 economies under Section 301 of the Trade Act. Tariff treatment depended on the product, origin and exemptions. A broad tariff headline was therefore not enough for an importer: the specific supply chain had to be assessed. This legal and logistical burden added conditions that an oil price chart alone cannot show.
Late July and August: the technology transaction had two sides
Demand for technology was visible both in sellers’ revenue and in customers’ investment bills. On 29 July, Microsoft reported capital expenditure, including finance leases, of 41 billion US dollars for the quarter ended 30 June. Cash purchases of property and equipment were 35.8 billion dollars. These amounts must not be added together: the first includes finance leases, while the second shows asset purchases paid for in cash during the quarter.
The company generated 55.4 billion dollars in operating cash flow. Subtracting cash purchases of property and equipment left 19.6 billion dollars. This explains why a rapid pace of construction is not automatically a bad signal: what matters is how much cash the business generates and how much more it needs from outside.
On 26 August, chip designer NVIDIA reported revenue of 96.221 billion dollars for the quarter ended 26 July, up 106% year on year. Operating profit grew 124%. Some customer spending had therefore already become real earnings for the supplier. For customers to earn a return on their investments, however, their new services need demand and must cover equipment, electricity and financing costs.
August and September: growth continued, but costs did not disappear
Economic data showed resilience, not a general halt in growth. The second estimate of US second-quarter gross domestic product showed annualised growth of 1.5%, or about 0.4% quarter on quarter. Euro-area growth was revised to 0.6% quarter on quarter on 7 September. These figures need to be put on the same time basis before comparing the regions.
The US added 162,000 jobs in August; the data were released on 4 September. On 9 September, second-quarter revenue growth in selected US service industries was revised to 3.0% from the previous quarter. This revenue measure has not been adjusted for prices. Rising sales and a greater real volume of services delivered are therefore not the same thing.
9–11 September: the energy question reached monetary policy
On 9 September, the US Energy Information Administration raised its second-half average Brent price forecast to about 90 dollars per barrel. Model inputs were finalised on 3 September. This is a conditional average for a future period, not the oil price on 15 September and not an already measured effect of later military action.
On 10 September, the European Central Bank announced another interest rate increase of 0.25 percentage points. The deposit facility rate rose from 2.25% to 2.50% on 16 September. On 11 September, the US Consumer Price Index showed annual inflation of 3.4% in August, the same as in July. The seasonally adjusted monthly change accelerated from 0.1% to 0.4%. These data were known before the Federal Reserve meeting of 15–16 September, which subsequently raised the target range.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
? How should we read GDP and price indices?
Gross domestic product measures the value of final goods and services produced in an economy. Real growth removes the effect of prices. US quarterly growth is often reported at an annualised rate, as if the same change continued for four quarters. The Consumer Price Index measures a basket of prices weighted by consumption. Its annual and monthly changes have different comparison bases. The Personal Consumption Expenditures Price Index also includes spending made on consumers’ behalf, uses different weights and accounts for changes in the composition of consumption; these two price indices should not be treated as interchangeable.
Mid-September: June’s hopes were not enough to restore supply
The International Energy Agency’s 11 September forecast projected a larger fall in oil supply than in demand this year. This is a forecast, not the final annual result.
Lower demand does not automatically mean cheaper oil. If the volume reaching buyers falls faster, fuel bills can remain high even as the economy slows. This can help an energy producer only if it can deliver its output. For a haulier or an energy-buying factory, the same situation raises costs.
16–24 September: the relief in interest rates did not last
On 16 September the Federal Reserve raised its target range to 3.75–4.00%. An earlier European decision lifting the deposit rate to 2.50% took effect on the same day. The US ten-year yield fell to 4.96% on 21–22 September, but reached 5.18% on 24 September. A few days of easier financing conditions did not become a lasting direction.
The preliminary US Purchasing Managers’ Index, or PMI, reached 58.4 in the release of 23 September, compared with 56.0 in August. Initial unemployment benefit claims of 197,000 for the week ending 19 September, released on 24 September, reinforced the picture of resilience. These are newer signals, but neither a survey nor one week of claims is a final measure of an entire quarter’s growth.
? Purchasing Managers’ Index: what does the threshold mean?
The company survey compares activity with the previous month. Above 50 generally indicates expansion and below 50 contraction. A reading of 58.4 does not mean growth of 58.4%; the preliminary measure may be revised.
September’s decisions extended beyond the US and euro area. On 18 September the Bank of Japan set an overnight interest-rate target of 1.25%, effective from 24 September. On 17 September the Bank of England left Bank Rate at 3.75%. These different paths matter for Japanese bonds and yen-funded investments, as well as British companies’ borrowing costs.

Check your saving plan
Are your monthly contributions enough?
Compare your monthly contribution with your target future income. Adjust the time horizon to see how the amount you need changes.
This compares scenarios; it does not promise a future outcome.
Quarter
What matters now
23–25 September: growth did not remove cost risk
Crude stocks are rising, but fuel stocks offer less comfort
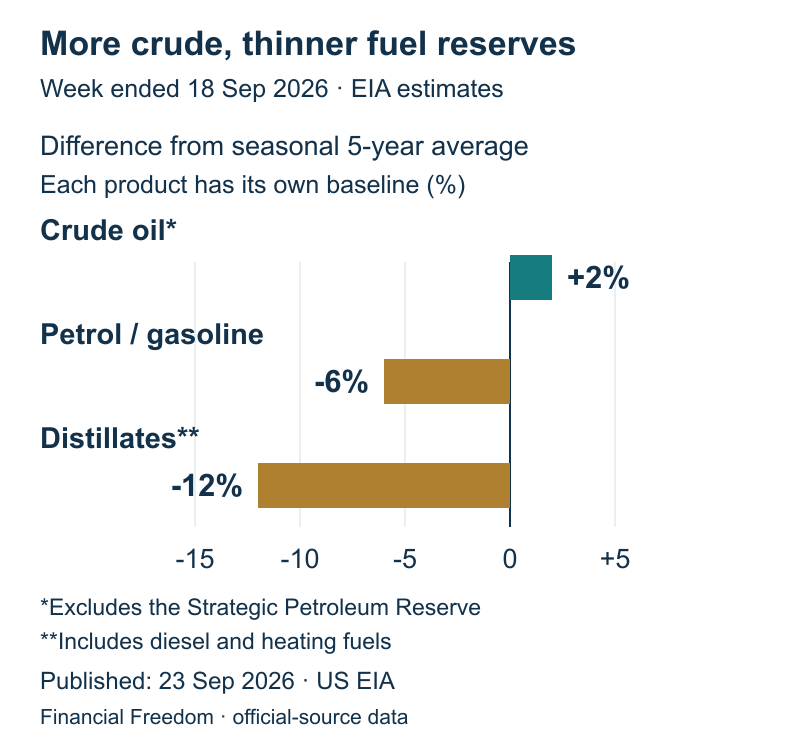
More crude oil in storage does not mean fuel-supply pressure is over. On 23 September the US Energy Information Administration reported that commercial crude stocks, excluding the strategic reserve, rose by 3.0 million barrels to 426.4 million in the week ending 18 September. They were around 2% above the five-year seasonal average. Petrol stocks, however, were 6% below their own average and distillate stocks 12% below theirs.
? Distillates and seasonal averages: what is being compared?
Distillates include diesel and heating-oil products. Each product’s stock is compared with its own average for the same time of year over five years. A 12% shortfall is neither a 12% rise in diesel prices nor the same share of total fuel demand.
Refining helps explain the gap. US plants processed 519,000 fewer barrels of crude per day than a week earlier, taking throughput to 16.8 million barrels a day. Less crude being processed can leave more in storage while replenishment of finished fuels slows. This does not mean every missing barrel must translate into a higher price, but it shows where there is less protection against another disruption.
For hauliers, airlines and energy-intensive manufacturers, the final fuel bill matters. For refiners, the difference between product selling prices and crude purchase prices matters, so rising crude inventories alone do not explain their profits. Higher refining throughput and replenished product stocks would create an opportunity for fuel-sensitive sectors. Another supply interruption before stocks recover is the risk. Subsequent EIA weekly reports will show whether the gap is narrowing.
Europe has less growth to absorb higher costs, while technology must earn a return on expansion
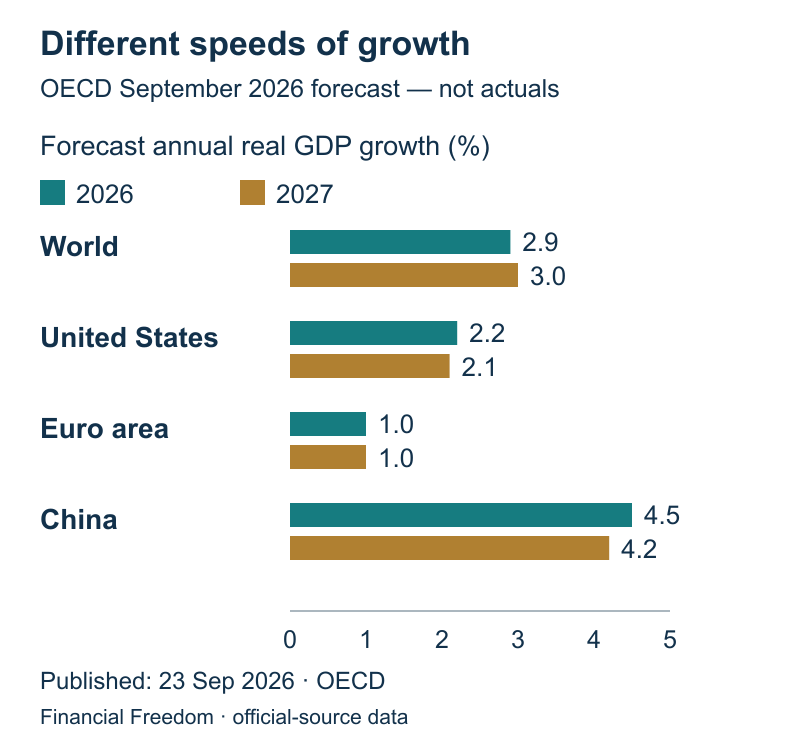
The world economy has not stalled, but regions face different cost pressures. On 23 September the Organisation for Economic Co-operation and Development forecast global growth of 2.9% in 2026. Its projections were 2.2% for the US and 1.0% for the euro area. These are forecasts from the same organisation, not final full-year results. Slower European demand leaves companies less room to pass higher energy and interest costs on to customers.
Revenue growth alone is therefore insufficient in European industry and retail. What matters is whether sales volumes also increase and profit margins hold up. Property businesses refinancing debt face an additional interest bill. An earlier European Central Bank decision raised its deposit rate to 2.50% from 16 September. That remains part of the backdrop, not a new decision today.
Investment in artificial-intelligence infrastructure provides a counterweight. The organisation identifies it as a support for growth and trade, but also warns about greater reliance on external funding. An equipment order can immediately lift the supplier’s revenue, while the data-centre owner still needs customers, electricity and enough cash flow to service loans. A supplier making a sale and its customer earning a return on that investment are not the same event.
The opportunity remains with companies able to support expansion with real orders and cash generated by their operations. Risk is greater where expensive construction and debt pay off only under an optimistic demand scenario. Memory-chip maker Micron’s results presentation on 30 September will help test data-centre demand and supply. It is an upcoming signal for the supply chain, not a promise that its shares or the technology sector will rise.
Two opposing forces are shaping portfolios
Resilient US demand supports business sales, but higher bond yields increase the cost of new finance. Energy adds another constraint: rising crude inventories do not guarantee the same improvement in finished fuels. It therefore makes little sense to label every bond unattractive or every technology company equally resilient. Debt maturity, cash reserves and the speed at which investment starts earning money differ.
In bonds, the higher starting yield must be weighed against potential price swings and the issuer’s ability to pay. In equities, revenue growth needs to be checked against margins and cash flow. Slower European growth makes it harder to pass costs on, while stronger US demand may keep rates elevated for longer. For a euro investor, exchange rates also affect unhedged dollar holdings; an unverified currency move is not presented as fact here.
A more favourable combination would be slower price increases, rebuilding fuel stocks and resilient corporate profit. The adverse combination would be expensive funding alongside weakening demand. The latest evidence does not make either outcome inevitable.
Quarter
What comes next
Three signals that could change the conclusion
- US prices and spending on 30 September. The August Personal Consumption Expenditures Price Index will test whether price pressure is easing; real spending will separate a greater volume of purchases from a larger bill.
- Micron’s results on 30 September. Memory-chip orders, pricing and planned investment matter alongside headline revenue growth. The results had not been released by this edition’s cutoff.
- The next US fuel-stock reports. Watch whether refining throughput, petrol stocks and distillate stocks recover together. An increase in crude alone will not answer the whole question.
? Personal Consumption Expenditures Price Index: what does it measure?
This index measures changes in the prices of goods and services consumed, including spending made by others on consumers’ behalf. Its weights adjust with the composition of spending, so it is not identical to the Consumer Price Index. Price growth and growth in real consumption answer different questions.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.





