30 days · Market review
30 days: growth continues, but costs squeeze profits
China’s figures on 19 October showed faster economic growth but weak consumer spending. Across 21 September–20 October, this connects with earlier US income and spending signals: higher output or expenditure does not automatically mean a firmer foundation for household spending and business profits.
Period covered: 2026-09-21 – 2026-10-20Information as of 21 min read
Chinese growth and Canadian inflation figures added to the monthly picture. US technology rebounded after Asia’s equity shock, but Japanese shares fell again on 20 October.
Resilient production does not remove weak consumer demand or higher fuel bills. Companies need to pass on higher costs without losing sales.
30 days
What happened
Context before 21 September: starting conditions
Euro-area second-quarter real growth was revised to 0.6% from the previous quarter on 7 September. NVIDIA’s 26 August results and Broadcom’s 2 September report of 29.6 billion US dollars of revenue for the quarter ending 2 August, up 86% year on year, already demonstrated technology demand. Euro-area August inflation was finally revised from an initial 3.3% to 3.2% on 17 September, after July’s 2.9%. The French 10-year bond yield was 4.48% on 14 September after 4.19% on 1 September, a 0.29 percentage-point change, not an investment return. On 11 September, the International Energy Agency forecast a larger decline in this year’s oil supply than demand.
Markets entered the period beginning on 21 September with the US rate increase already in effect. On 16 September, the Federal Reserve raised its target rate range to 3.75–4.00%, effective from 17 September. The European Central Bank’s 10 September decision to raise its deposit rate from 2.25% to 2.50% took effect on 16 September. On 18 September, the Bank of Japan set a 1.25% overnight rate target from 24 September, while the Bank of England left its rate at 3.75% on 17 September.
21–28 September: interest-rate effects and uneven economic signals
The US 10-year Treasury yield had fallen to 4.96% on 21–22 September but reached 5.18% on 24 September. On 23 September, the preliminary S&P Global US PMI Composite Output Index rose from August’s 56.0 to 58.4. The initial unemployment-claim count for the week ending 19 September, revised on 1 October, was 198 thousand; the week ending 26 September recorded 197 thousand. The earlier estimate for the first week had been 197 thousand.
On 25 September, US August durable-goods orders were 338.6 billion dollars, almost unchanged from revised July. Non-defence capital-goods orders excluding aircraft rose 1.6%, with shipments up 0.6%. However, the final University of Michigan September sentiment index fell from August’s 51.7 to 48.1. Monthly order changes remove seasonality, not price effects; claims are not the number of new jobs.
On 27 September, the White House published proposed US–China tariff-relief product lists, each covering roughly 30 billion US dollars in one trade direction. The US list included plastic tableware and bedding from China; China’s list included US beef and dairy products. At the time of the announcement, this proposed relief was not yet in force. On 28 September, China reported that larger industrial companies’ August profits rose 4.2% year on year, after July’s 11.2%; these are not changes between adjacent months.
30 September: spending held up while energy and technology demand increased
On 30 September, the US Bureau of Economic Analysis reported that real August spending rose 0.6% month on month while real disposable income was unchanged. The Personal Consumption Expenditures Price Index rose 3.4% year on year, or 3.0% excluding food and energy. July’s annual rates were the same in that revised data vintage. Second-quarter real gross domestic product growth was revised from a 1.5% to a 2.2% annualised rate, equivalent to 0.6% from the previous quarter.
Destatis’s preliminary German September figures published on 30 September showed faster price growth; the final estimate on 13 October confirmed this, as discussed below. France’s annual harmonised consumer-price inflation rose from 2.6% to 3.4%.
China’s National Bureau of Statistics reported on 30 September that the manufacturing purchasing managers’ index rose from 49.8 in August to 50.1 in September. Over the same period, the new-orders index fell from 50.6 to 50.5 while the input purchase-price index rose from 56.6 to 60.8.
On 30 September, the US Energy Information Administration reported 427.3 million barrels of commercial crude stocks for the week ending 25 September, 2.6% more than a year earlier. Gasoline stocks were 7.4% lower and distillates, including diesel and heating products, 14.9% lower. More crude was not the same as adequate finished-fuel stocks.
Memory-chip maker Micron reported 54.229 billion US dollars of revenue on 30 September for its quarter ending 3 September, versus 11.315 billion a year earlier. This year’s quarter lasted 14 weeks and the earlier one 13, so the comparison is not equal-length.
Real spending and gross domestic product growth remove price effects; a US annualised quarterly rate is not growth achieved in three months. Consumer-price and consumption-expenditure indices use different baskets and weights; the latter also covers some spending paid on consumers’ behalf. A purchasing managers’ index above 50 indicates broad expansion, not percentage growth of that size; a price index measures how widespread increases are.
1–7 October: fewer new jobs and higher costs
On 1 October, the US Institute for Supply Management’s September manufacturing purchasing managers’ index was 54.5, while prices paid rose from 71.1 to 77.9. The European Central Bank reported August new-mortgage rates of 3.60%, consumer-credit rates of 7.92%, and an almost unchanged corporate borrowing-cost measure of 3.77%. These are euro-area averages for new agreements and do not yet capture September’s rate increase.
On 1 October, Eurostat reported second-quarter Lithuanian housing transaction prices 14.3% higher year on year, versus 4.0% in the euro area. These are prices, not rental income or net investment returns.
On 2 October, the US Bureau of Labor Statistics reported 29 thousand additional non-farm jobs in September after revised August growth of 133 thousand. The combined July–August result was reduced by 60 thousand; July became a loss of 10 thousand jobs. September unemployment was 4.2%. Eurostat’s preliminary estimate that day showed euro-area September consumer inflation rising from 3.2% to 3.8%. On 4 October, seven OPEC+ countries kept September output targets for November, not confirmed actual supply.
On 5 October, the Nasdaq Composite price index rose 1.05% in US dollars from the 2 October close, while the US 10-year Treasury yield rose from 5.28% to 5.31%. The September ISM Services PMI published that day fell from 55.4 to 54.9, while prices rose from 72.6 to 74.0.
On 5 October, Eurostat reported euro-area August industrial producer prices up 1.9% from July: energy rose 5.6%, and industry excluding energy 0.2%. These are domestic-market selling prices, not all production costs or consumer inflation. European Central Bank Executive Board member Philip Lane said that day that dearer energy left families less money for other goods and higher long-term interest rates restrained spending and investment; this was his assessment, not a new decision.
On 6 October, Destatis reported German August factory orders down 10.6% from July, or 0.1% excluding large orders. Ships, aircraft, trains and military vehicles had exceptionally large July orders. Nevertheless, June–August orders excluding large deals were 2.6% below the preceding three months. Orders are not realised revenue; the measure removes price, seasonal and calendar effects, and August figures are preliminary.
On 6 October, Eurostat reported euro-area August retail volumes recovering 0.1% after July’s 0.6% decline. Non-food volumes rose 0.5%, while fuel fell 1.9%. This measures quantities sold after removing price, seasonal and calendar effects, not retailers’ revenue or profit.
The Federal Reserve’s 15–16 September minutes, published on 7 October, showed most participants then expecting another rate increase; this was not a new October decision. The US Treasury’s 39 billion dollar reopening of a 10-year bond that day had a 5.30% high yield and a 2.77 bid-to-cover ratio.
8–9 October: borrowing remained expensive and demand was uneven
On 8 October, Federal Reserve Governor Christopher Waller left another rate increase open if the data developed as he expected. The European Central Bank’s September meeting account, published that day, recalled that energy costs had not yet spread broadly into wages and other prices. This described an earlier meeting, not a new decision.
At the US Treasury’s 22 billion US dollar reopening of a 30-year bond on 8 October, the high yield was 5.618%, versus 5.308% at the same issue’s 10 September auction. On 9 October, reference 2-, 10- and 30-year yields were 4.80%, 5.24% and 5.60%. The first two rose from the previous day’s 4.75% and 5.22%, while the third was unchanged. From 2 October they nevertheless fell by 3, 4 and 3 basis points respectively.
An auction high yield describes one issue; reference yields are derived from constant-maturity US Treasury quotations. Neither is a realised fund return; one basis point equals 0.01 percentage point.
On 8 October, Destatis reported that German August exports fell 0.8% from July to 137.6 billion euros, while imports rose 0.9% to 118.1 billion euros. The goods trade surplus fell from 21.6 to 19.5 billion euros. Exports to the US fell 6.3%, while sales to the euro area rose 0.8%, China 4.7% and the UK 16.7%. US sales were still 22.6% higher than a year earlier. These are seasonally and calendar-adjusted euro values, not physical volumes; the breakdown alone does not establish a tariff effect.
On 8 October, the European Systemic Risk Board’s assessment of its 1 October meeting warned of higher financial-stability risks, technology companies’ borrowing and excessive future-profit expectations. Leveraged funds could amplify bond volatility. Counterweights were European banks’ strong capital, liquidity and profitability and lower technology-financing concentration than in the US. This was a risk scenario, not a report of actual insolvency.
The University of Michigan’s preliminary 9 October survey showed US consumer sentiment falling from September’s 48.1 to 46.3. Current conditions fell from 50.9 to 44.7, but expectations rose from 46.3 to 47.3. The university highlighted expensive goods and borrowing that made large purchases harder. Median expected inflation for the coming year rose from 4.6% to 4.7%.
The survey measures attitudes, not actual spending or a central-bank forecast. The median is the middle response: half expect no higher inflation and half no lower inflation; October’s figures are preliminary.
On 9 October, Destatis reported 2,373 German business insolvency cases in July, 8.0% more than a year earlier. From January to July, transport and storage recorded 85.5 cases per 10,000 businesses, versus 42.8 across the economy. However, creditors’ claims over those seven months fell from 31.8 to 21.9 billion euros: more economically significant businesses had failed a year earlier.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
9–13 October: fuel, interest-rate and technology costs persisted
On 9 October, the US Treasury’s Office of Foreign Assets Control issued General License 135. Under its 9 October terms and the specified US rules, the licence authorised transactions involving the sale, delivery, offloading and import of Russian-origin diesel, including US imports, until 7 April 2027 at 00:01 Eastern Daylight Time (EDT). It does not permit debits from accounts of Russia’s central bank, National Wealth Fund or Finance Ministry at US financial institutions. This does not remove all sanctions: the licence neither changes other countries’ rules nor sets a delivery volume or schedule.
On 11 October, the International Energy Agency identified renewed attacks on Saudi civilian and energy infrastructure and asked countries to consider an additional diesel-stock release. No new quantity had been agreed. On 7 October, countries had already agreed to accelerate the uncompleted remainder of March’s stock programme, prioritising diesel; that was an earlier commitment, not an additional quantity.
On 12 October, Cleveland Federal Reserve President Beth Hammack said demand-restraining interest rates were still needed to bring inflation down. She highlighted energy, tariff-related import costs and demand for artificial-intelligence equipment that was raising the price of components used elsewhere. This was her personal assessment, not a Federal Reserve decision.
The Reserve Bank of Australia’s minutes published on 13 October explained the unanimous 0.25 percentage-point rate rise to 4.60% at its 28–29 September meeting. The bank discussed energy disruptions, constrained production capacity and artificial-intelligence equipment costs. Strong profits and resilient borrowers and banks were, for now, counterweights to rising technology debt and optimistic profit expectations. The minutes were not a new rate rise on 13 October.
The Bank of Japan’s preliminary September Corporate Goods Price Index, published on 13 October, showed annual growth of 6.8% after August’s 7.6%, and a 0.3% monthly decline. Import prices fell 0.2% from August in yen but rose 1.0% in contract currencies. Petroleum, coal and natural gas became 2.3% more expensive in contract currencies and contributed 0.69 percentage point to overall import-price growth.
The producer index measures goods traded between businesses, not consumer prices or all production costs. Converting imports into yen changes the comparison; annual and monthly changes have different bases, and preliminary figures may be revised.
On 12 October, chip designer NVIDIA and networking supplier Cisco presented a plan for denser optical connections. Against 200-gigabit-per-second-per-lane modules, their design envisages four times the bandwidth density and about 1.3 times the energy efficiency. NVIDIA also contributed some rack and computing-module designs to the open-standards community. Processor designer AMD presented the open Helion rack design for AI agents that execute tasks; it planned November 2026 availability for equipment still being developed with partners.
A gigabit is one billion bits. The vendors’ comparison describes particular connections, not a whole data centre’s electricity bill or profit; an open design and planned availability are not realised sales revenue.
The European Central Bank’s 12 October reference rate was 1.1181 US dollars per euro, after 1.1206 on 9 October. The euro weakened by about 0.22% between those reference points. The rate was published before Beth Hammack’s speech, so this comparison neither establishes a reaction to her remarks nor represents a transaction price.
13 October: a better growth forecast and higher energy costs
On 13 October, the International Monetary Fund raised its 2026 global real-growth forecast from July’s 3.0% to 3.1%. Its 3.4% assessment for next year was unchanged. This is projected economic activity, not an achieved full-year result or an investment return. Technology investment supports demand, while energy-importing countries face higher costs.
That day, Germany’s statistical office confirmed September annual consumer-price inflation of 3.3%, after August’s 2.9%. Growth excluding food and energy remained 2.4%, while energy prices were 14.9% higher than a year earlier. The fuel-tax reduction from 1 October was not yet reflected in September’s measurement. These are German figures, not a reading for the entire euro area.
On 13 October, US bank JPMorganChase reported 6% higher third-quarter net profit. Net interest income rose 13% and operating expenses 12%, while provisions for credit losses fell from roughly 3.4 to 2.7 billion US dollars. One bank does not describe the entire sector: profit depends on expenses and provision estimates as well as demand for loans.
14 October: consumer prices rose while equipment sales grew
On 14 October, the US Bureau of Labor Statistics reported that annual consumer-price inflation rose from August’s 3.4% to 3.7% in September, and from 2.4% to 2.6% excluding food and energy. Petrol prices rose 9.1% over the month and accounted for more than half of the overall 0.6% monthly increase. These were September prices, reported in October.
Preliminary figures released the same day showed average hourly earnings for US private non-farm employees rising 0.1% in September, but their purchasing power falling 0.5% after price changes. A larger number on a payslip therefore did not necessarily buy more.
On 14 October, the International Energy Agency estimated September world oil supply at 102.3 million barrels a day. That was 2.5 million, or about 2.5%, more than in August. The agency also described continuing diesel shortages: more crude oil does not yet mean fuel reaches consumers when needed.
Chipmaking-equipment supplier ASML reported third-quarter revenue of 11.66 billion euros on 14 October, about 55% more than a year earlier. Net profit of 4.96 billion euros included an approximately 0.51 billion-euro gain from an increase in the value of an investment. Not all profit growth therefore came from equipment sales.
Asia’s decline was severe, but the US did not repeat it
On 15 October, South Korea’s main share index, the KOSPI, closed down 7.57%. Japan’s Nikkei 225 lost 4.90% and Taiwan’s TAIEX fell 3.41%. This was not a single-company problem: several markets important to the technology industry came under pressure together.
In South Korea, the fall reached the threshold for a temporary halt across the KOSPI market. At 12:38 Korean time on 15 October, the Korea Exchange announced a 20-minute suspension of KOSPI market trading. This was a pause triggered by a sharp price decline, not an all-day exchange closure or a restriction limited to certain automated orders.
The sequence matters. The US Nasdaq Composite technology-heavy share index had fallen 1.88% on 14 October, before pressure reached Asia the following day. At their 15 October meeting, South Korean financial authorities identified US interest-rate expectations, uncertainty over the profitability of artificial-intelligence investment and oil prices as risks. That is the authorities’ explanation, not proof that every sale had the same cause.
The subsequent US session on 15 October was different: the S&P 500 gained 0.33% and the Nasdaq Composite rose 0.08%. On 16 October, Japan’s Nikkei 225 closed 1.39% higher and Taiwan’s TAIEX gained 0.30%. Japan’s index nevertheless remained 3.57% below its 14 October close. A modest rebound is not the same as recovering the full loss.
US sales rose, but not simply because people bought more
On 15 October, the US published September retail and food-service sales. Their value rose 0.8% from August, but only 0.2% excluding petrol stations. Petrol-station sales increased 6.4%. These figures measure dollars spent, not quantities purchased: higher fuel prices can lift the value of sales without an increase in the amount bought.
Figures released the same day showed that prices received by US producers increased 1.3% in September from August and 6.3% from a year earlier. The statistical agency attributed more than four fifths of the monthly rise in goods prices to energy. This is not a forecast of shop prices: a business can pass higher expenses to customers or absorb some of them through lower profit.
These releases came after the Asian sessions described above had ended, so they could not have caused the earlier falls that day. They add to the broader problem: when fuel and other essential bills take more money, less remains for discretionary purchases.
TSMC’s sales outlook provides a counterweight to technology fears
Taiwan’s TSMC, which manufactures chips for other companies, reported third-quarter revenue of US$46.72 billion on 15 October. On 15 October, it forecast US$52.3–54.3 billion for the fourth quarter. The midpoint implies roughly 14.1% growth from the third quarter, but this remains guidance rather than revenue already earned.
The company reiterated its US$60–64 billion investment plan for 2026. Strong chip demand supports manufacturers and equipment suppliers, but does not establish that buying more equipment will pay off for every data centre. Revenue at the start of the supply chain is not the same as profit at its end.
European industry has yet to show a broad recovery
Eurostat reported on 15 October that euro-area industrial production fell 0.5% in August from July and 1.1% from August a year earlier. However, the production of capital goods, such as equipment, increased 0.4% over the month. This is an important exception: weaker industry overall does not prevent growth in individual areas of investment.
15–16 October: US bond yields fell while production grew
On 15 October, the indicative annual yield on 10-year US Treasuries was 5.10%, compared with 5.19% on 14 October.
On 16 October, the Federal Reserve reported a 0.7% monthly increase in US real industrial production in September, with manufacturing up 0.3%. Both changes are seasonally adjusted. These figures cover a later month than the euro-area August statistics discussed earlier, so they are not a like-for-like comparison of the same period across countries.
Korean shares fell despite the previous US rebound
On 20 October, South Korea’s main KOSPI index closed at 5,552.74 points, down 3.73% on the day. The KOSDAQ index fell 3.33% to 781.97 points. In its daily review compiled at 09:45 Lithuanian time, the exchange linked the KOSPI decline to concerns about artificial-intelligence profitability and financing, and the international situation. This is the exchange’s market interpretation, not proof that every seller had the same motive.
On 19 October, the US Nasdaq Composite equity index rose 1.11%, while the Nasdaq-100 index of large non-financial companies gained 1.17%. The PHLX Semiconductor index advanced 1.61%. These are results from the previous US trading day, not changes during the 20 October US session.
At 09:25 Lithuanian time on 20 October, Japan’s Nikkei 225 stood at 64,037.26 points, 1.35% below its previous close. The Nikkei Semiconductor Stock Index was down 2.82% at that point. These were intraday readings, not Japan’s final daily result. They show that companies in similar businesses were not moving in the same direction across markets that morning.
Index changes alone do not establish why investors bought or sold. Nor do they show a euro investor’s return: that would require the particular fund’s holdings, fees and currency movement.
Chinese production grew much faster than consumer sales
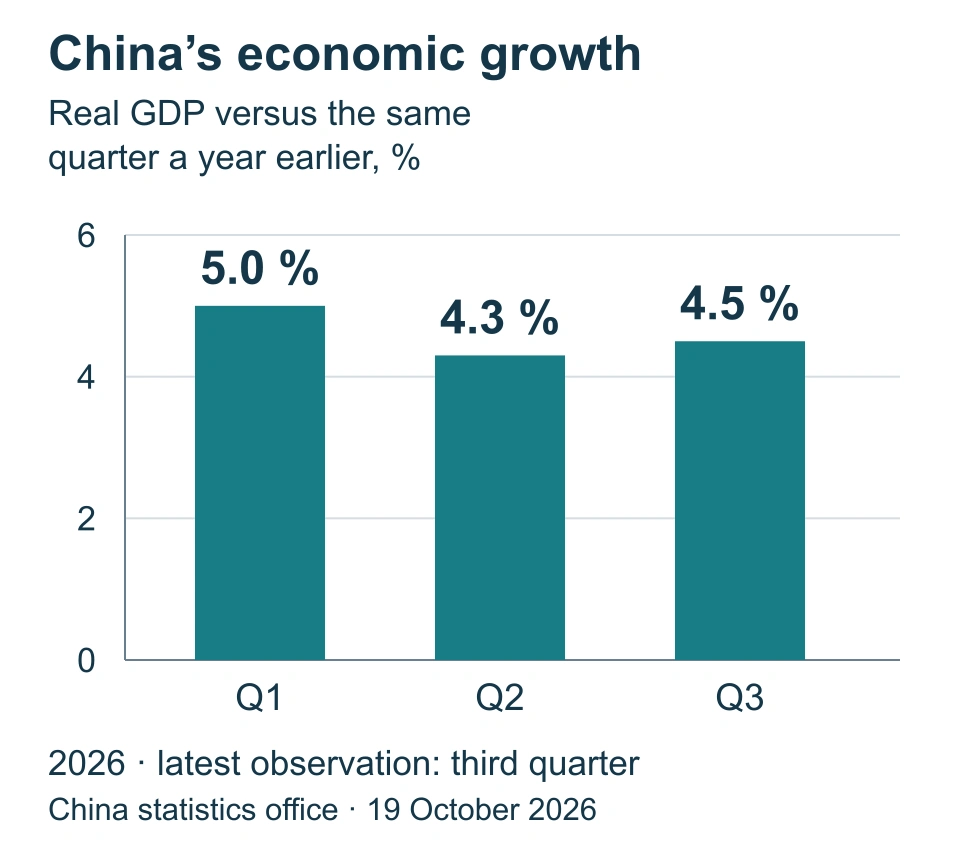
On 19 October, China’s statistics office reported that real gross domestic product in the third quarter was 4.5% higher than a year earlier. Growth had been 4.3% in the second quarter. In September, value added by industrial enterprises meeting the specified size threshold increased 5.5% year on year, but retail sales grew only 1.1%. Industrial value added is adjusted for price changes, whereas sales are reported at current prices; these are not identically calculated measures of volume.
Property exposed another weak part of domestic demand: investment in property development over January–September was 20.6% lower than a year earlier. This is a change in investment over nine months, not a September house-price decline. A shortage of construction orders can directly reduce revenues for suppliers of building materials and equipment.
On 20 October, China’s one-year loan prime rate was set at 3.0%, and the rate for loans over five years at 3.5%. These are reference rates used in bank loan pricing. An individual borrower’s interest rate also depends on the contract and the bank’s risk assessment, so neither figure is a loan price available equally to everyone.
Petrol pushed Canada’s headline price measure higher
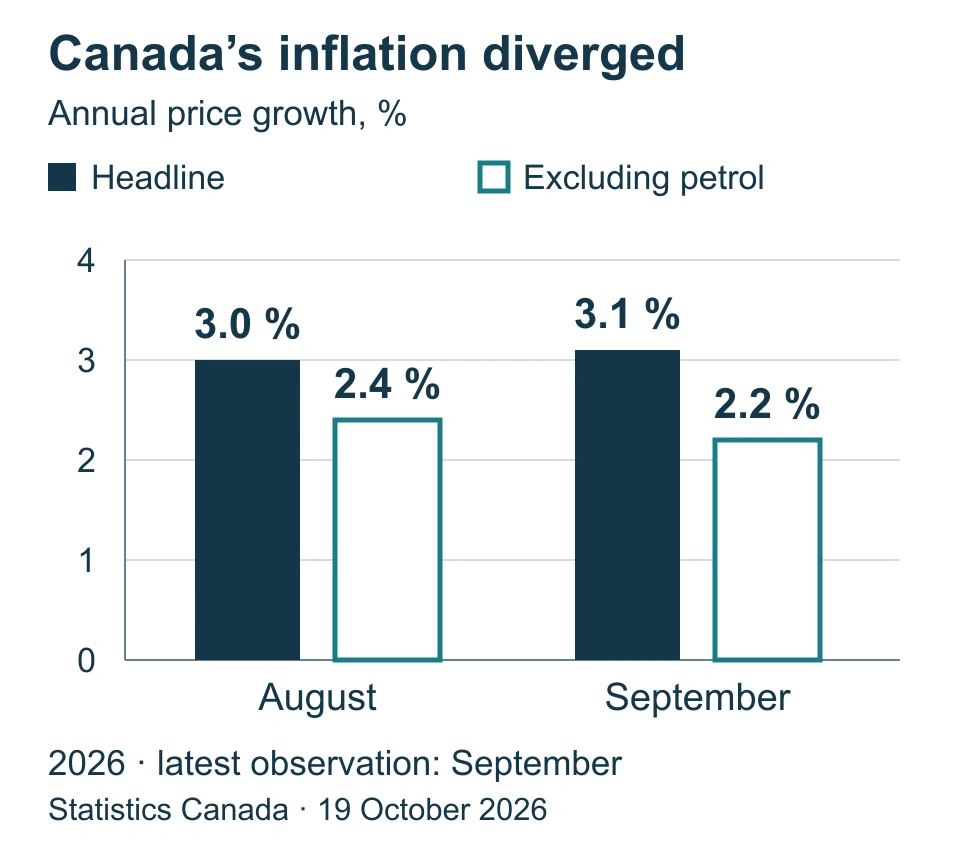
On 19 October, Statistics Canada reported that annual inflation in September had accelerated from 3.0% to 3.1%. Excluding petrol, however, price growth slowed from 2.4% to 2.2%. Petrol cost 27.8% more than a year earlier, compared with annual growth of 22.8% in August. The higher headline inflation rate therefore does not indicate uniformly stronger pressure across all prices.
? Annual inflation: which prices are being compared?
This compares a consumer price basket with the same month a year earlier, not with the previous month. The measure excluding petrol helps separate its influence but is not the same as a measure excluding all energy products.
30 days
What matters now
Funds covering different regions can depend on the same customers
A portfolio holding US technology companies, Korean electronics businesses and Japanese semiconductor producers has a shared link to electronics and data-centre investment. When the same customers reduce orders, geographical diversity does not always mean different earnings risks. A Korean equity fund and a broader Asian fund will also depend on their individual company weights. An opportunity can arise where a lower share price accompanies firm orders and cash generation; a falling price alone does not establish that case.
Suppliers of industrial equipment to China may be in a different position from sellers of consumer goods or construction materials. The former depend on factory orders, while the latter need household purchases and new building activity. Someone assessing a Chinese equity fund or a European exporter should therefore ask which customers generate revenue, rather than rely only on the country’s headline economic growth rate.
More expensive fuel changes household spending and bond risks
For Canadian transport companies, petrol and other fuel prices matter through costs; for retailers, they matter through the money customers have left for discretionary purchases. Higher selling prices can help energy companies, but production, refining and financing costs still shape their profits. The overall consumer price index does not establish the profitability of each of these businesses.
For Canadian government bonds, the question is whether the central bank regards the petrol surge as temporary or sees it spreading to other prices. Expectations of higher interest rates for longer would put pressure on long-dated fixed-rate bond prices. Weaker demand would be a counterweight. For holdings without a currency hedge, changes in the Canadian dollar also affect the return measured in euros.
For US consumer-goods and leisure businesses, stronger spending can support revenue, but slow employment growth weakens its foundation. Sellers of inexpensive essentials may therefore face a different outlook from producers of more expensive goods that buyers can postpone.
Cheaper, more readily available diesel would help transport companies and fuel-intensive manufacturers protect profits. Lower crude prices could have the opposite effect on oil producers’ revenue. Stock releases or permission to trade create an opportunity for supply to improve, but the result depends on actual flows.
30 days
What comes next
The US central bank meets on 27–28 October. Its decision will help show how it balances price pressures against economic activity and labour-market conditions.
On 28 October, the Bank of Canada will announce its interest-rate decision and an updated economic assessment. The main question is whether slowing price growth elsewhere will outweigh more expensive petrol.
On 10 November, Taiwanese chipmaker TSMC will release October sales. The result for the first month of the quarter will help test progress towards the fourth-quarter revenue guidance announced on 15 October.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.