Today · Market review
Tech shares rebounded, but growth remains costly to finance
The US Nasdaq Composite rose 1.60% on 11 November. Results released the previous evening by artificial intelligence (AI) computing provider CoreWeave showed that despite rapid revenue growth, operating income still falls short of net interest expense. Today’s 12 November updates from SoftBank and Siemens add to the same question: who is earning money from the data-centre expansion, and who still needs to recover money invested?
Period covered: 2026-11-12Information as of 5 min read
The completed 11 November US session showed an equity rebound. On 12 November, SoftBank updated its equipment-advance recovery plan, while Siemens released new orders and earnings figures.
The US policy-rate target range remains 3.75–4.00%. Higher orders and expected future proceeds are not the same as profits already earned or cash already received.
Today
What happened
The US rebound was not shared equally across markets
The technology-heavy Nasdaq Composite closed on 11 November at 25,466.19 points, compared with 25,065.87 the day before. In intraday commentary, the New York Stock Exchange strategist identified AI infrastructure companies following CoreWeave’s results as one source of strength.
Japan presented a different picture this morning. At 08:20 Lithuanian time on 12 November, the Nikkei 225 was 0.77% below its previous close and Japan’s Nikkei Semiconductor index was down 2.10%. These were intraday readings, not final session results. The contrast means that a rebound in one US index is insufficient evidence of a recovery across global equities.
CoreWeave’s revenue grew, but interest exceeded operating income
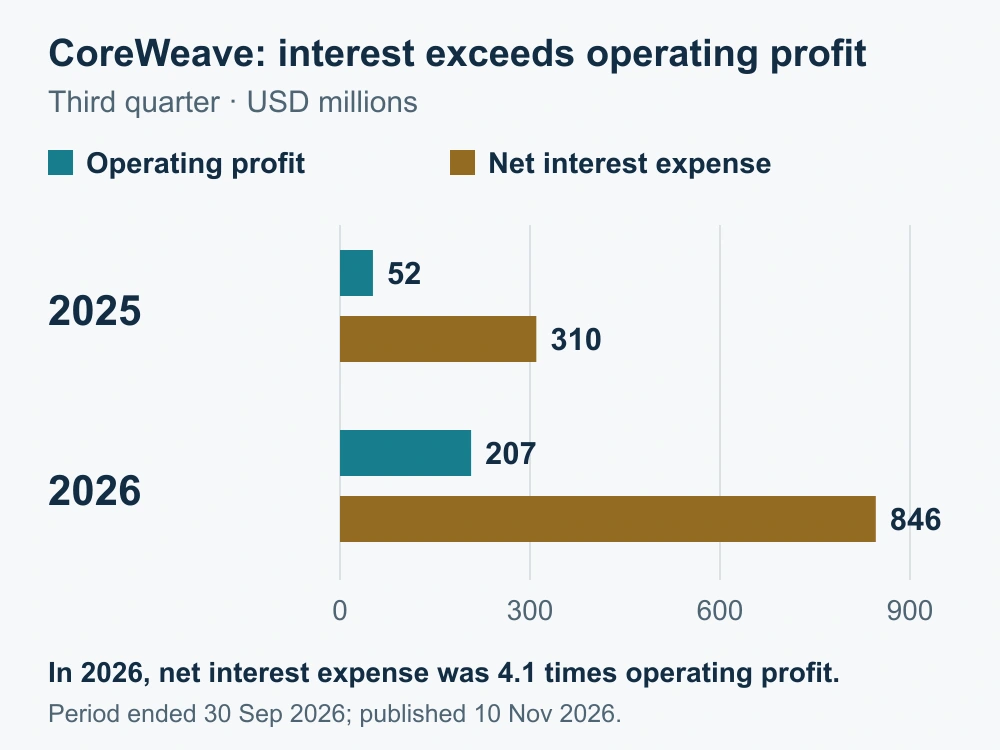
US AI computing provider CoreWeave reported third-quarter revenue of $3.661 billion on 10 November, up 168.2% year on year. Operating income was $207 million, net interest expense $846 million and the net loss $709 million. Strong demand and a loss can therefore coexist.
A data-centre operator must acquire equipment and secure electricity before collecting customer revenue over a longer period. When expansion is debt-funded, interest becomes a separate obstacle to profitability. This differs from an equipment supplier that receives revenue from selling a product and does not necessarily face the same wait for a project to pay for itself.
? Operating income: why is it not the final result?
Operating income measures earnings before net interest expense, tax and other non-operating items. It is not cash flow. Comparing it with interest expense helps explain financing costs but does not establish when a company will become profitable.
After the US bond-market holiday, the observation date matters
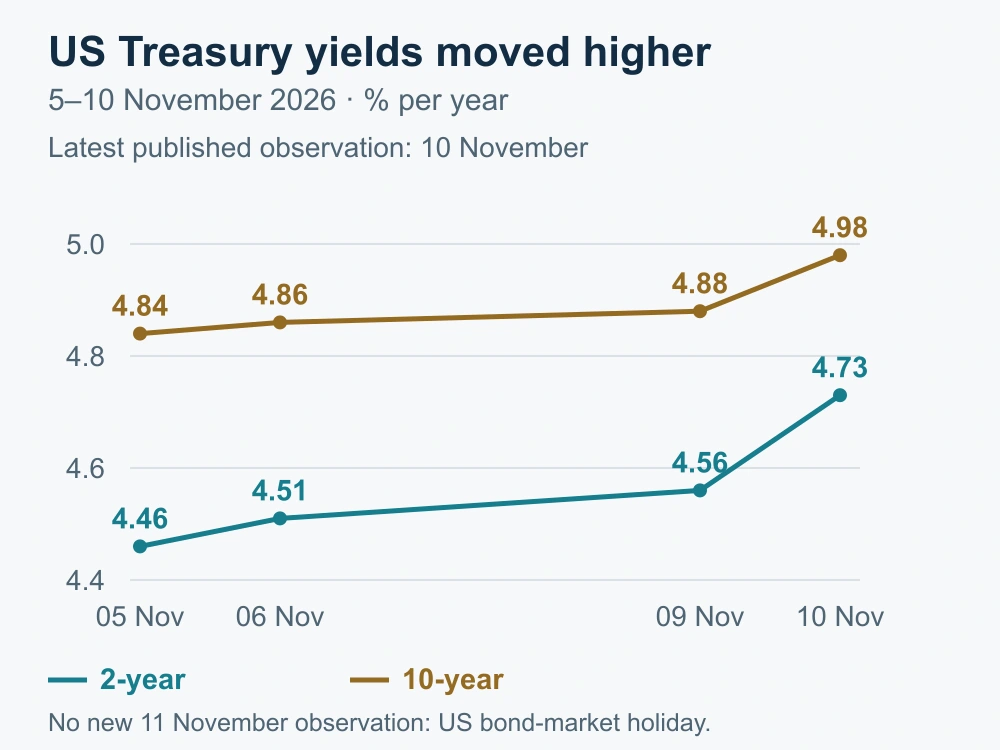
The latest official US Treasury yields are dated 10 November: 4.98% for ten years and 4.73% for two years. They increased by 10 and 17 basis points respectively that day. The United States observed Veterans Day on 11 November, and no new official observation is available.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
SoftBank separated remaining advances from expected proceeds
Japanese investment group SoftBank’s updated US AI data-centre slide dated 12 November details equipment advances as of 30 September. Of $9.5 billion accumulated, $6.6 billion remained after a $2.9 billion write-off. The group expects to recover $5.6 billion through the PORTS-Pike power-generation project: $3.4 billion in the near term and $2.2 billion by the end of 2027. These are expected proceeds, not cash already received. The slide update is not a new financial report dated 12 November: the underlying results were released on 10 November.
Siemens showed how infrastructure demand reaches suppliers
Germany’s Siemens reported on 12 November that July–September orders in its Smart Infrastructure division increased 40% to €8.665 billion from the same quarter of 2025. Profit was €1.468 billion, compared with €1.166 billion a year earlier. Large data-centre orders in the United States and Europe mattered, but US tariff refunds also improved profit. The entire increase therefore cannot be attributed to AI.
Japanese producer-price pressure did not ease this morning
Preliminary figures released by the Bank of Japan on 12 November showed that producer goods prices were 7.1% higher in October than a year earlier, following 6.8% in September. They increased 0.7% over the month. These are business goods prices, not the household consumption basket. More expensive inputs and imports can reduce manufacturers’ earnings if they cannot pass the full increase on to customers.
Today
What matters now
Where a company sits in the data-centre build-out matters
New projects can raise sales for suppliers of chips, electrical equipment and building-management systems. A cloud operator, however, needs customers to use capacity for long enough and receipts to exceed equipment, energy and financing costs. These are different business risks, even though all the companies participate in AI expansion.
The opportunity emerges when genuine orders become profitable sales and the company retains enough cash to invest. Risk increases when the pace of expansion depends on repeated borrowing or expected receipts arrive late. SoftBank’s recovery plan therefore needs to be judged against delivery, and Siemens’ earnings against continuing operations, separating the one-off effect of tariff refunds.
Higher yields affect existing and new investments differently
Prices of long-dated fixed-rate bonds generally fall when market interest rates rise. For a new investor, the same change may offer higher interest income. Property companies and debt-funded businesses face the cost of new borrowing; an existing fixed-rate loan payment does not change merely because market rates move. For a euro-based investor, the dollar exchange rate also affects the outcome of US investments.
? A basis point: how large is the change?
One basis point is 0.01 percentage point. A yield increase from 4.88% to 4.98% is 10 basis points, not a 10% change in the bond’s price. Yield is not a fund’s return for that day.
Today
What comes next
12 November: the labour market and UK growth
UK September and third-quarter economic data are scheduled for 09:00 Lithuanian time today. They will help assess whether activity remains resilient under current financing conditions. US weekly unemployment insurance claims are scheduled for 15:30: do low new claims sit alongside people’s ability to find another job?
13 November: are business selling prices still rising quickly?
The United States will release its October Producer Price Index at 15:30 Lithuanian time. It will supplement the consumer-price report published on 10 November and help assess pressure on business costs and selling prices. A slower increase would ease concerns about further price pressure, but would not by itself guarantee lower interest rates.
17 November: another test of price pressure
The United States will publish October import and export price indexes at 15:30 Lithuanian time. These will help separate externally sourced price pressure from domestic economic forces. Investors need to know whether increases in equipment and other goods prices are easing or continuing to raise the cost of new projects.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.