Quarter · Market review
90 days: hopes for supply recovery gave way to higher costs
In June, there were hopes that agreements would help restore energy supply. By September, the picture includes both more expensive oil and another European rate increase. Meanwhile, technology suppliers earned more. The central lesson of this period: strong demand does not solve every problem with delivery, financing and the returns on investment.
Period covered: 2026-06-18 – 2026-09-15Information as of 10 min read
China’s statistics on 15 September added to the longer story: stronger industry does not yet mean a broad recovery in household purchases. The US ten-year yield was 4.97% on Monday. The questions of energy supply and interest rates did not disappear during these 90 days.
Promises of a supply recovery still need to be tested against actual flows. Technology revenue growth needs to be assessed alongside buyers’ investment spending, and owning several funds should not be confused with lower dependence on the same companies.
Quarter
What happened
The starting point: interest rates had already risen on 17 June
This 90-day period begins on 18 June. The day before, on 17 June, the European Central Bank’s previously announced interest rate increase took effect. The rate on banks’ overnight deposits rose from 2.00% to 2.25%. These are the initial conditions from the day before the period under review, not a new event within it.
Also on 17 June, the Federal Reserve left the federal funds target range at 3.50–3.75%. It made no change on 29 July. Europe also chose a pause on 23 July. For a business with debt, this meant that energy costs would not be offset by automatically and rapidly falling interest rates.
18 June: a political agreement raised hopes, but did not yet restore shipping
The US–Iran memorandum was presented as a route towards ending hostilities and reopening the Strait of Hormuz. The economic benefit depended on what happened after the signatures: could ships sail safely, would insurance be available, and would oil actually reach buyers?
More reliable deliveries would have reduced importing industries’ need to hold expensive inventories. Hauliers would have found fuel and route planning easier. But the agreement itself was not a statistical record of restored flows. July and August data later required a more cautious assessment of precisely this assumption.
July: the supply recovery was not sustained
The International Energy Agency’s 10 July review described a partial recovery in June flows and ceasefire violations on 7–8 July. Its 12 August report said Persian Gulf oil exports in July, including routes bypassing the strait, averaged 15 million barrels per day. That was 2.1 million, or about 12%, below June.
This comparison describes two monthly averages, not a one-day shipping halt. It showed that June’s hopes had not been enough to deliver a lasting improvement. US military statements on 5 and 8 September about strikes on Iranian tankers were a reminder that delivery security remained unresolved. A particular price move cannot be attributed solely to these statements.
23 July: trade rules and sanctions added to the planning burden
The European Union’s 21st sanctions package against Russia expanded restrictions on energy, financial services and the shadow fleet. For companies, this matters beyond politics: payment, insurance and cargo transport options change. But an announced restriction is not a measured fall in exports of the same size.
On the same day, the Office of the US Trade Representative announced measures concerning 60 economies under Section 301 of the Trade Act. Tariff treatment depended on the product, origin and exemptions. A broad tariff headline was therefore not enough for an importer: the specific supply chain had to be assessed. This legal and logistical burden added conditions that an oil price chart alone cannot show.
Late July and August: the technology transaction had two sides
Demand for technology was visible both in sellers’ revenue and in customers’ investment bills. On 29 July, Microsoft reported capital expenditure, including finance leases, of 41 billion US dollars for the quarter ended 30 June. Cash purchases of property and equipment were 35.8 billion dollars. These amounts must not be added together: the first includes finance leases, while the second shows asset purchases paid for in cash during the quarter.
The company generated 55.4 billion dollars in operating cash flow. Subtracting cash purchases of property and equipment left 19.6 billion dollars. This explains why a rapid pace of construction is not automatically a bad signal: what matters is how much cash the business generates and how much more it needs from outside.
On 26 August, chip designer NVIDIA reported revenue of 96.221 billion dollars for the quarter ended 26 July, up 106% year on year. Operating profit grew 124%. Some customer spending had therefore already become real earnings for the supplier. For customers to earn a return on their investments, however, their new services need demand and must cover equipment, electricity and financing costs.
August and September: growth continued, but costs did not disappear
Economic data showed resilience, not a general halt in growth. The second estimate of US second-quarter gross domestic product showed annualised growth of 1.5%, or about 0.4% quarter on quarter. Euro-area growth was revised to 0.6% quarter on quarter on 7 September. These figures need to be put on the same time basis before comparing the regions.
The US added 162,000 jobs in August; the data were released on 4 September. On 9 September, second-quarter revenue growth in selected US service industries was revised to 3.0% from the previous quarter. This revenue measure has not been adjusted for prices. Rising sales and a greater real volume of services delivered are therefore not the same thing.
9–11 September: the energy question reached monetary policy
On 9 September, the US Energy Information Administration raised its second-half average Brent price forecast to about 90 dollars per barrel. Model inputs were finalised on 3 September. This is a conditional average for a future period, not the oil price on 15 September and not an already measured effect of later military action.
On 10 September, the European Central Bank announced another interest rate increase of 0.25 percentage points. The deposit facility rate will become 2.50% on 16 September; until then, 2.25% applies. On 11 September, the US Consumer Price Index showed annual inflation of 3.4% in August, the same as in July. The seasonally adjusted monthly change accelerated from 0.1% to 0.4%. These data are already known and form a new backdrop to the approaching Federal Reserve meeting.
? How should we read GDP and price indices?
Gross domestic product measures the value of final goods and services produced in an economy. Real growth removes the effect of prices. US quarterly growth is often reported at an annualised rate, as if the same change continued for four quarters. The Consumer Price Index measures a basket of prices weighted by consumption. Its annual and monthly changes have different comparison bases. The Personal Consumption Expenditures Price Index also includes spending made on consumers’ behalf, uses different weights and accounts for changes in the composition of consumption; these two price indices should not be treated as interchangeable.
Mid-September: June’s hopes were not enough to restore supply
The International Energy Agency’s 11 September forecast projected a larger fall in oil supply than in demand this year. This is a forecast, not the final annual result.
Lower demand does not automatically mean cheaper oil. If the volume reaching buyers falls faster, fuel bills can remain high even as the economy slows. This can help an energy producer only if it can deliver its output. For a haulier or an energy-buying factory, the same situation raises costs.
Check your saving plan
Are your monthly contributions enough?
Compare your monthly contribution with your target future income. Adjust the time horizon to see how the amount you need changes.
This compares scenarios; it does not promise a future outcome.
Quarter
What matters now
15 September: a recovery in production is not a recovery for every consumer
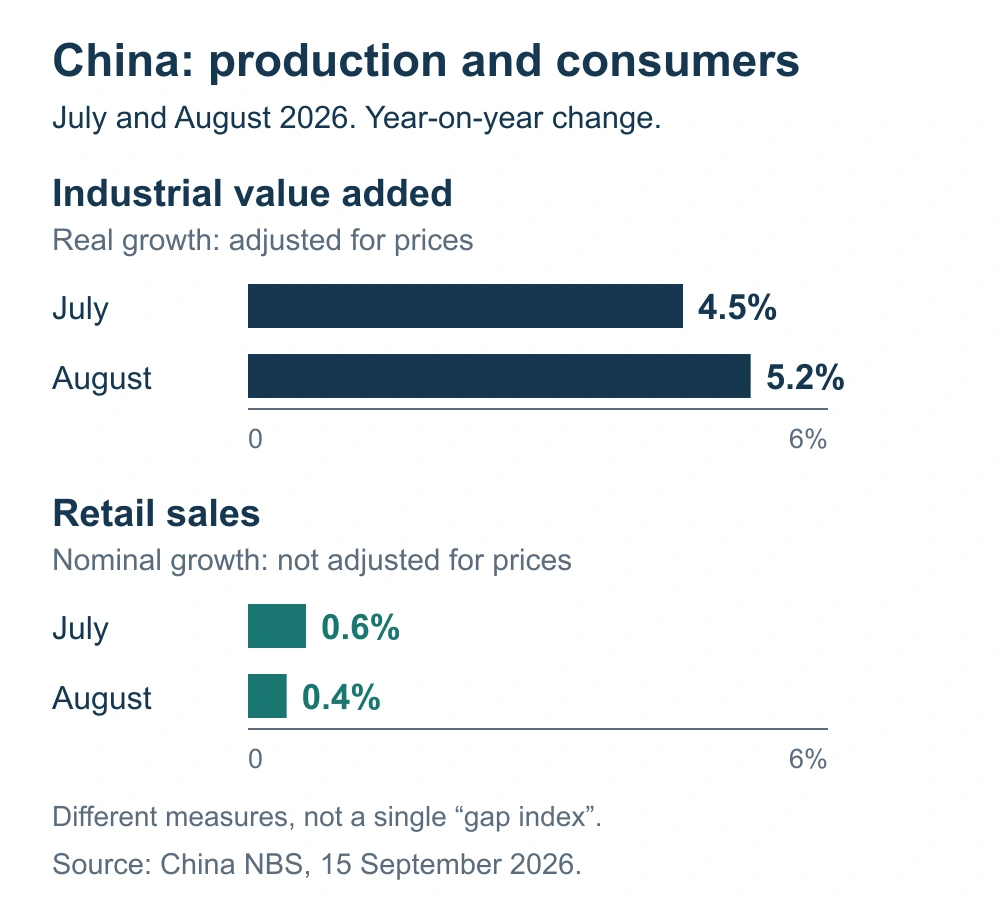
August year-on-year changes released on 15 September: China’s industrial output grew 5.2% in real terms, while retail sales increased 0.4% in nominal terms.
These figures extend an important lesson from this period: a strong result in one part of the economy does not guarantee a strong economy overall.
A European business selling machinery to factories and one selling goods to households can therefore receive different signals from the same country. In a global portfolio, it helps to look beyond country weights to the end customer. The opportunity is where orders turn into profitable sales. Risk rises when a revenue forecast depends on consumers whose spending has not yet recovered.
Higher asset values and higher costs can coexist
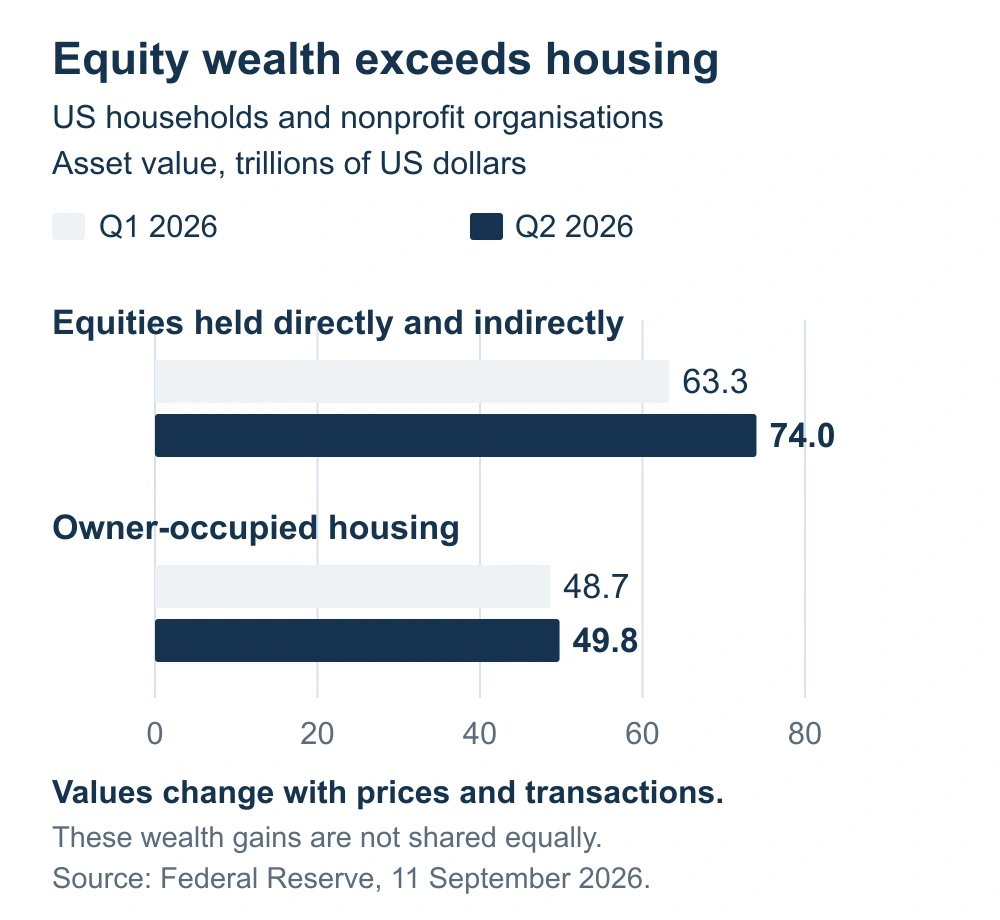
Federal Reserve financial accounts released on 11 September showed a marked second-quarter difference. The value of corporate equities held directly and indirectly by US households and nonprofit organisations rose from 63.32 trillion to 74.03 trillion dollars, about 16.9%. The value of owner-occupied housing rose from 48.67 trillion to 49.79 trillion dollars, about 2.3%.
These are aggregate asset values at quarter-end, not the average family’s return or a performance contest between two investments. Both revaluations and transactions affect the changes. Even so, the data explain why equities matter to the broader economy: market moves can significantly change financial asset owners’ perceived ability to spend. The benefits are unevenly distributed because households do not all own the same amount of equities.
14 September session: long-term financing is still expensive
US Treasury yields on Monday were 4.65% for two years, 4.97% for ten years and 5.34% for thirty years. Friday’s corresponding figures were 4.63%, 4.96% and 5.35%. The direction was not uniform over the session: shorter-maturity yields edged higher, while the longest maturity declined. These are nominal annual yields, not that day’s bond returns.
This small daily move does not remove the larger question: how much will it cost a company to borrow for the full life of an investment? The Federal Reserve decision has not yet been announced, and long-term bond prices reflect more than expectations for the next meeting. Inflation, debt supply and investors’ willingness to lend for a long time also matter. We therefore do not attribute the entire price movement to a single news item.
When a safer alternative pays more, investors may pay less today for a company’s distant future profits. For holders of long-term fixed-rate bonds, higher market yields also put pressure on the price of their existing bonds. But someone buying a new bond now faces different income terms. It is therefore essential to distinguish the price of assets already held from the yield available in the market today.
Quarterly takeaway: not every June assumption stayed intact
Hopes of normalised supply weakened, while the earnings story strengthened for some technology suppliers. The 10 September decision also challenged the simple assumption that European financing would automatically become cheaper soon. However, the slowdown in annual US inflation excluding food and energy from 2.5% to 2.4% is a counterweight to the claim that every inflation measure is worsening equally.
These forces meet in a portfolio’s individual holdings. An energy company and an energy-buying factory are not the same exposure. A supplier paid today and a customer expecting revenue several years from now also face different risks. Several funds do not protect against this overlap if their largest holdings are the same.
What does a change in asset values tell us, and what does it not?
Financial accounts show how much wealth a sector holds on a particular date. Aggregate equity wealth can rise because of prices and net purchases, while housing wealth also depends on the stock of properties and their valuations. Changes in these aggregate amounts are therefore not simply investment returns. A trillion means one thousand billion.
Quarter
What comes next
16 September: a decision ahead, not an outcome already known
The two-day meeting of the Federal Reserve, the US central bank, begins today. Its interest rate decision will be announced on 16 September. Until then, the federal funds target range remains 3.50–3.75%, as left unchanged on 29 July. Also on 16 September, the already approved increase in Europe’s deposit facility rate to 2.50% takes effect. Today, that rate is still 2.25%.
The market assessment will depend on more than the number in the decision. What matters is whether higher energy costs spread to other prices, whether consumers can still increase their spending, and whether companies have more cash left after investing. More reliable supply and slower price growth would be more favourable for bonds and borrowers. The opposite combination would put greater pressure on companies paying their costs now while still waiting for revenue.
The same three assumptions will be tested over the coming months
The first is the actual restoration of oil deliveries. The second is technology customers’ revenue after heavy investment. The third is consumers’ ability to buy more—not just to spend more at higher prices, but to purchase a greater volume of goods and services. If these improve together, more sectors can support growth. If expansion remains narrow, a few strong companies’ results will not offset every weaker part of a portfolio.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.