Today · Market review
After the broad sell-off: a rebound does not settle the inflation question
Japanese shares recovered part of Friday’s loss on 9 November, but the broad US sell-off on 5 November leaves investors with a question that a price rebound alone cannot answer. Can business revenue and productivity offset higher energy and financing costs?
Period covered: 2026-11-09Information as of 5 min read
China reported slower consumer-price inflation but faster producer-price inflation this morning. Japanese shares recovered some ground during a session that had not yet closed.
The Federal Reserve’s 3.75–4.00% target range, retained on 28 October, remains in place. A stronger labour market does not by itself ensure lower inflation or an interest-rate cut.
Today
What happened
Shares are recovering from a broad decline, not one company’s setback
The US equity sell-off on 5 November extended beyond technology companies. The broad S&P 500 price index fell 4.36%, while the technology-heavy Nasdaq Composite lost 5.52%. The Nasdaq rose 1.09% the following day, but that rebound did not erase the preceding session’s decline. This sequence also matters for global equity funds: separate funds can hold the same large US companies.
Asia’s reaction came later and was also broad. Japan’s Nikkei 225 fell 5.96% on 6 November, with 222 of its 225 constituents declining. At 07:50 Lithuanian time on 9 November, the index was up 2.41% from Friday’s close. This was an observation during an ongoing session, not Monday’s closing level or proof that selling pressure had ended.
? Index performance: is this my fund’s return?
A price-index change compares the index with the preceding session’s close and excludes reinvested dividends. A euro-based investor’s fund return is also affected by exchange rates, fees and the fund’s holdings.
Political intentions could alter costs, but they are not yet law
On 5 November, US Senate Democratic leader Chuck Schumer listed stopping tariffs and preventing households from paying higher electricity bills to subsidise data centres among his priorities for the next Congress. These are political intentions whose details and adoption remain unconfirmed. If data-centre owners had to bear more electricity-infrastructure costs, their investments could take longer to pay back. The timing of a speech and a sell-off alone does not establish a single cause for the market’s entire move.
US employment increased and earlier months were revised upwards
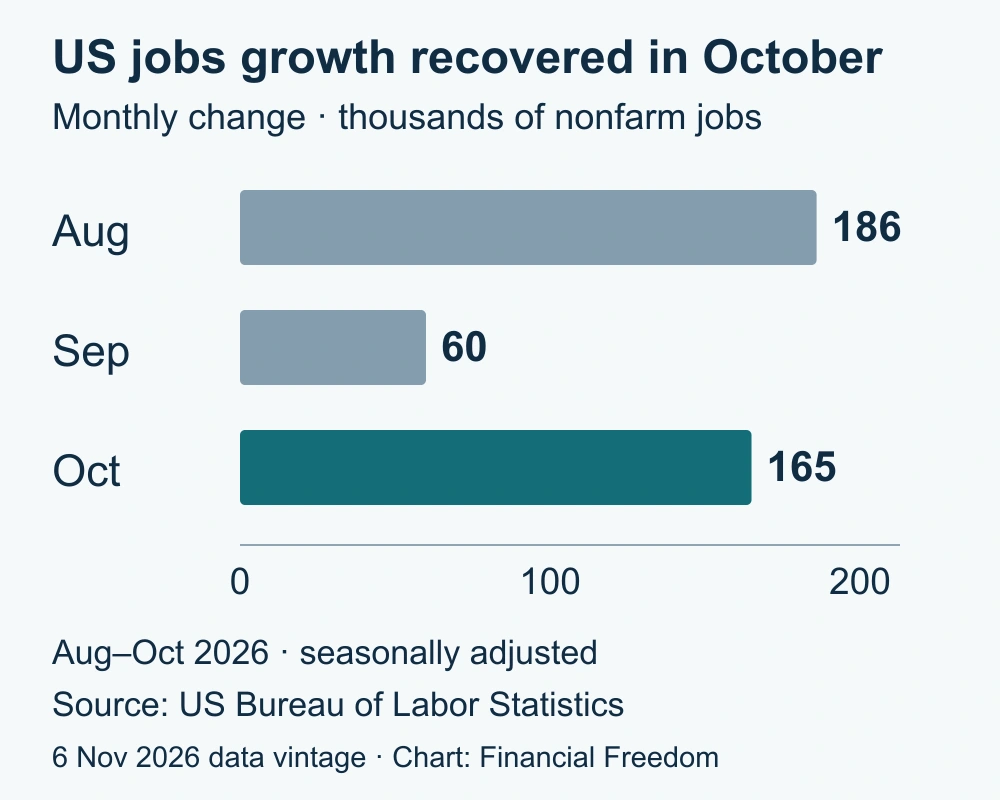
On 6 November, the US Bureau of Labor Statistics reported an increase of 165,000 non-farm payroll jobs in October. The combined August and September increases were revised upwards by 84,000. Unemployment was 4.1%, compared with 4.2% in September. These figures weaken the assumption that a sharply deteriorating labour market is already inevitably undermining household incomes.
? Payroll jobs and unemployment: why are they different measures?
Payroll changes come from a survey of employers, while unemployment is measured in a separate household survey. The unemployment rate uses the labour force as its denominator, not the entire US population; monthly payroll estimates are subsequently revised.
More resilient household incomes are supportive of sales at retailers and consumer-service businesses. They do not promise cheaper loans soon for companies or homebuyers: the US central bank must also assess inflation. A labour-market report can therefore support corporate revenue without necessarily supporting the valuations of expensive growth shares.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
China’s new release shows different pressures on consumers and factories
This morning, 9 November, China’s statistics office published October price data. Consumer prices increased 0.7% from a year earlier, compared with 0.9% in September. In contrast, annual producer-price inflation accelerated from 5.0% to 5.7%. This is not a general fall in prices: consumer prices were still rising, only more slowly.
Chinese manufacturers also face pressure on their inputs: purchasing prices for raw materials and other production inputs rose 7.9% over the year. A company unable to pass that increase on to its customers would retain less profit. However, the difference between these indices is not a direct measure of corporate profit margins because they cover different baskets of goods.
Today
What matters now
After a rebound, distinguish demand from profitability
Resilient US household incomes and rising Chinese manufacturing costs affect different parts of a portfolio. A consumer company with broad distribution may sustain its sales while the supplier producing its goods loses some profit. Revenue growth is therefore more useful when accompanied by evidence about pricing, expenses and cash actually earned, not just promises of future orders.
Semiconductor manufacturers and data-centre developers retain a demand opportunity, but their risks differ. Chip suppliers depend more directly on customer orders, while infrastructure owners also face grid-connection costs and loan pricing. A lower share price does not automatically make an investment cheap if expected profits deteriorate at the same time. The opposite opportunity would emerge if orders held up and additional costs proved smaller than feared.
Energy inflation still limits central banks’ choices
On 5 November, the Bank of England raised Bank Rate by 0.25 percentage points to 4.00%. Euro-area figures for September, published that same day, showed producer energy prices rising 7.8% over the month, whereas producer prices excluding energy increased just 0.1%. This helps explain why energy-intensive factories can face greater pressure than other service businesses.
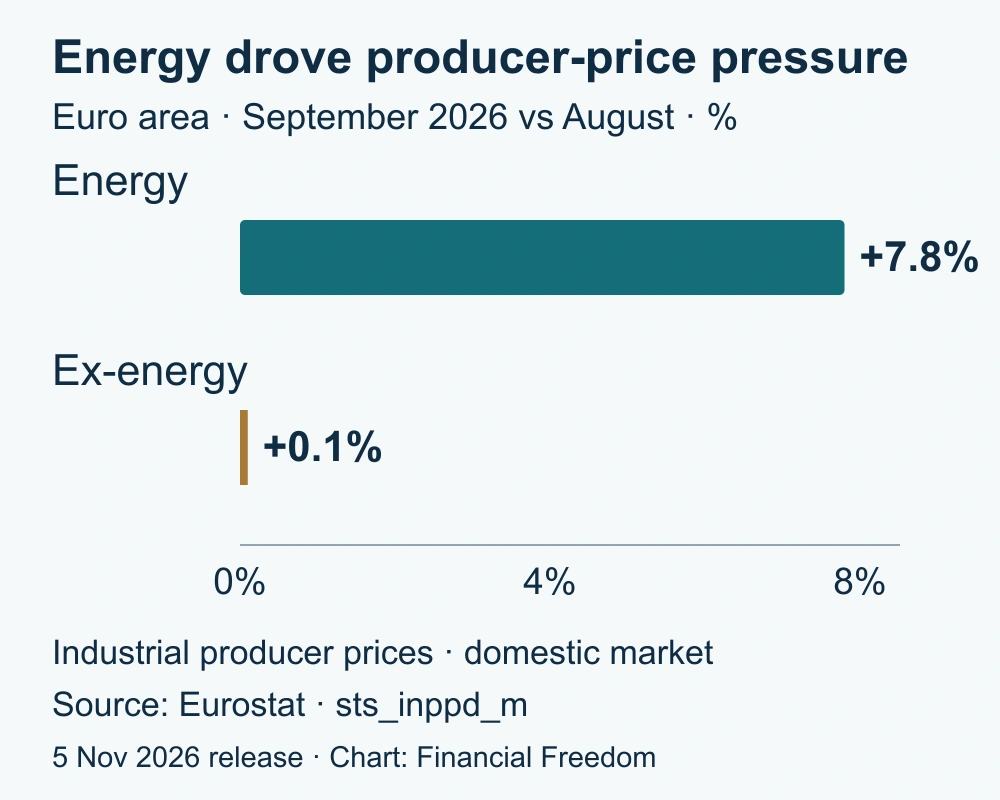
Lower interest rates would support the prices of longer-dated bonds, but renewed inflation could have the opposite effect. Shorter-dated bonds are less exposed to such price swings, although their principal has to be reinvested sooner. This distinction matters more than assuming that all bonds should behave alike after equities decline.
Today
What comes next
10 November: do US prices offer any relief?
The US October consumer price index is due on 10 November at 15:30 Lithuanian time. It will help show whether a stronger labour market is compatible with slowing inflation or whether cheaper borrowing may remain further away. Energy prices and the rest of the consumer basket matter separately: cheaper fuel alone would not demonstrate slower inflation across all services.
10 November: the first check on the new quarter’s chip demand
Taiwanese chip manufacturer TSMC plans to report October revenue on 10 November at 07:30 Lithuanian time. This will provide a concrete sales signal for semiconductor manufacturers and their equipment suppliers in the new quarter. One month’s revenue will not establish the whole quarter’s profit, but it can test whether the order narrative is supported by actual sales.
9–12 November: what return will investors demand from US debt?
The US Treasury is holding auctions of three-year securities on 9 November, ten-year securities on 10 November and thirty-year securities on 12 November. Demand will help assess whether long-term borrowing is becoming cheaper without a central-bank decision. Weaker demand and a higher required yield would pose a risk to longer-dated bonds and investments financed with substantial debt.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.