Quarter · Market review
Strong technology sales did not prevent the sell-off
The US equity sell-off on 5 November showed that strong technology suppliers’ results do not prevent investors from paying less for future growth. Interest rates and energy expenses rose during these 90 days. China’s price figures on 9 November again highlighted the gap between industrial price pressure and restrained consumption.
Period covered: 2026-08-12 – 2026-11-09Information as of 7 min read
Since 21 October, the Canadian, Australian and UK central banks have raised interest rates. Equities fell sharply in early November even as the latest US employment figures improved.
A chip supplier’s revenue does not establish its customer’s investment payback. Profits still depend on whether sales can cover higher energy and financing expenses.
Quarter
What happened
August and September brought both technology demand and higher rates
On 26 August, chip designer NVIDIA reported US$96.221 billion of revenue for its quarter ending 26 July, 106% more than a year earlier. Operating profit increased by 124%. These were earlier-quarter results released within this review period. They demonstrated actual equipment demand, but did not establish when the data centres buying that equipment would recover their investment.
Three major central banks raised interest rates in September. On 10 September, the European Central Bank decided to increase its deposit rate from 2.25% to 2.50%, effective on 16 September. On 16 September, the US Federal Reserve raised its target range from 3.50–3.75% to 3.75–4.00%. On 18 September, the Bank of Japan set a 1.25% target, effective on 24 September, replacing the previous 1.00%.
These decisions affect existing and new transactions differently. A business or household taking out a new loan may face higher interest charges, while an older fixed-rate bond becomes less attractive relative to newly offered debt. However, an individual loan’s cost also depends on the bank’s margin and the contract. Central-bank rates are not deposit or borrowing terms available equally to every customer.
? Rate increases: what are 25 basis points?
This means 0.25 percentage point, such as a move from 2.25% to 2.50%. The US figure is an overnight interest-rate target range; the euro-area figure used here is the central bank’s deposit-facility rate.
A trade proposal and delivered energy are different things
On 25–27 September, the US and China published recommendations for more favourable tariff treatment covering roughly US$30 billion of goods in each direction. US exports included agricultural products and medical equipment; Chinese goods for the US market included small appliances and toys. These were recommended lists requiring domestic legal decisions, not confirmed price reductions across all the products concerned.
On 14 October, the International Energy Agency described a fragile recovery in oil supply during September and renewed attacks in the Gulf. Increased crude production is not enough if refining or delivery is disrupted. A transport company needs a particular fuel at an agreed time, so a lower oil quotation on one day does not guarantee a reduction in its actual expenses.
On 15 October, Taiwanese chip manufacturer TSMC reported third-quarter revenue of US$46.72 billion. It forecast US$52.3–54.3 billion for the fourth quarter. This provided a meaningful counterweight to concerns about technology demand, but the second figure remains company guidance. Equipment orders and growth in the revenue of the customers financing them do not necessarily arrive at the same time.
Central-bank decisions diverged in late October
The Federal Reserve retained its September range on 28 October, the European Central Bank left its three rates unchanged on 29 October, and the Bank of Japan maintained its 1.25% target on 30 October. However, the Bank of Canada raised its overnight target from 2.25% to 2.50% on 28 October. Its explanation emphasised the risk of persistently expensive fuel spreading to other goods and services prices.
After raising its target to 4.60% on 29 September, Australia’s central bank increased it again to 4.85% on 3 November. The Bank of England raised Bank Rate from 3.75% to 4.00% on 5 November. Pauses by several central banks therefore did not mark a worldwide move towards cheaper borrowing. For heavily indebted businesses, the financing currency and the next refinancing date remain important.
For your investments
Let’s discuss your portfolio
 FINANCIAL FREEDOM01 / 04
Investment results since 1999
Are you beating
global equities?

at the end of the period
Jan 1999–Jun 2026 · EUR · Cumulative return, %
Linear scale · * MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM02 / 04Historical comparison
How far did it fall?
How long to recover?
Decline from the previous high

Longest recovery to the previous high

Jan 1999–Jun 2026 · EUR · Monthly data
* MSCI World → MSCI ACWI.
Past performance does not guarantee future returns.
FINANCIAL FREEDOM03 / 04Personal investment consultation
Already investing?
Let’s review your portfolio.
Yet to start
investing?
Let’s build your first
investment plan.
FINANCIAL FREEDOM04 / 04
Personal investment
consultation
Martynas
Juška
Investment manager
Managing a portfolio
of more than€100 million
In early November, risk became visible in equity prices
On 5 November, the US Nasdaq Composite price index fell 5.52%, while the broader S&P 500 lost 4.36%. Nasdaq recovered 1.09% on Friday, but still fell 3.37% between the 30 October and 6 November closes. Japan’s Nikkei 225 lost 9.25% over the same weekly closing-price interval. These weekly changes are not returns for the entire 90-day period.
? Equity-index changes: what is the comparison basis?
US indices are measured in US dollars and the Japanese index in yen; these are price changes excluding dividends. A fund investor’s euro return also depends on exchange rates, fees and the fund’s holdings.
Politics added uncertainty over business expenses. Following the US election on 3 November, Senator Sheldon Whitehouse said on 4 November that Democrats had won control of both chambers of Congress. On 5 November, Senate Democratic leader Chuck Schumer outlined plans to change tariffs and prevent data-centre electricity costs being shifted to households. These were political statements and intentions for a future agenda, not taxes already in force or enacted tariff repeal.
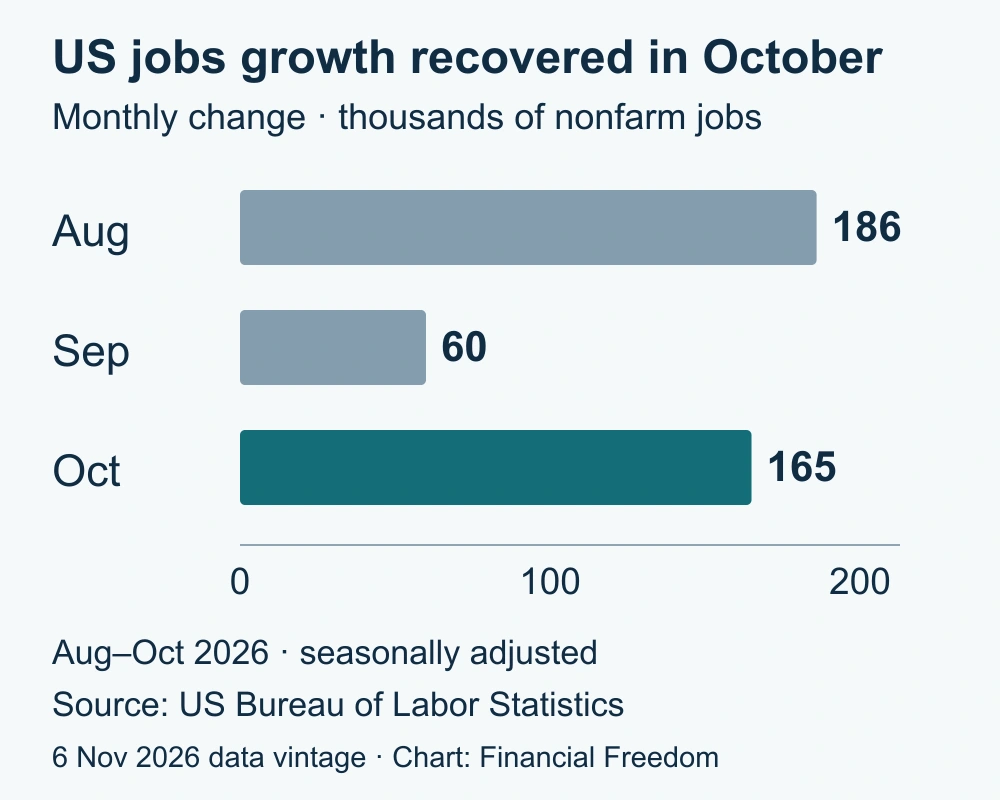
Figures published on 6 November showed that US non-farm employment increased by 165,000 jobs in October and unemployment was 4.1%. Earlier months were also revised upwards. The preliminary third-quarter productivity estimate released on 5 November showed an increase in real output per hour worked. Falling share prices alone therefore did not confirm that the entire economy was already contracting.
Price releases showed another obstacle. On 5 November, Eurostat reported annual growth of 11.1% in euro-area industrial producer prices for September, or 3.5% excluding energy. On 9 November, China reported annual producer-price growth of 5.7% for October, while consumer prices rose only 0.7%.
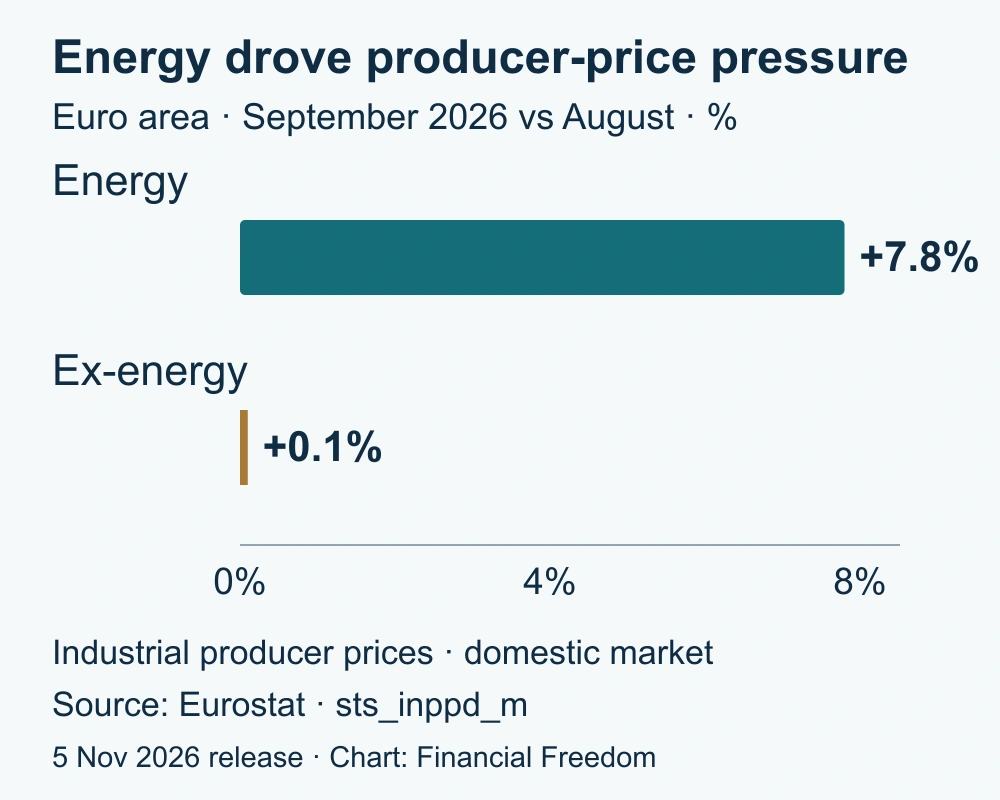
? Producer prices: are they companies’ costs?
The measure tracks changes in prices of goods sold by producers, not every company’s costs. The consumer-price basket and weights differ, so the gap between these indices is not a directly calculated reduction in company profits.
Quarter
What matters now
In technology funds, company names are only part of the exposure
A fund holding NVIDIA or TSMC carries some of the business risk of chip suppliers. Data-centre developers’ shares or bonds also depend on electricity costs, borrowing and equipment replacement. Several funds may hold different companies while depending on the same customers’ investment budgets. Different fund names therefore do not, by themselves, reduce shared exposure to technology demand.
The opportunity would come from orders turning into cash remaining after investment, not simply into reported revenue. Risk is greater where equipment must be replaced continually with borrowed money. A political intention to redistribute electricity-network costs does not yet allow a precise profit impact to be calculated; that requires enacted provisions, an effective date and the company’s contracts.
Bond protection depends on what drives inflation
The indicative yield on ten-year US Treasuries fell from 4.94% on 30 October to 4.86% on 6 November. That was a favourable price factor for existing fixed-rate bonds. But if rising energy costs again strengthened expectations of rate increases, long-dated bond prices could fall alongside equities. Shorter maturities generally mean smaller price swings, not the elimination of credit or currency risk.
? Bond yield: is it a fund’s return?
An indicative yield describes the annual compensation offered for debt in the market, not the return earned by a fund over a period. Other things equal, higher market yields reduce the price of an older fixed-rate bond.
Cheaper oil means different things for different businesses
The latest Brent observation published by the US Energy Information Administration (EIA) before the cutoff was for 3 November: US$107.03 a barrel, compared with US$120.15 on 30 October. This is a partial-week comparison, not the oil price on 9 November. Sustained fuel-cost relief would help transport and energy-intensive manufacturers; it would lower oil producers’ selling prices. Sales volumes and hedging contracts matter on both sides.
Quarter
What comes next
10 November, 15:30 Lithuanian time: US October consumer-price figures will show whether price pressure allows a stronger labour market to be viewed favourably or instead raises expectations of dearer borrowing. The comparison between energy and the rest of the basket will be more informative than the annual headline alone.
9, 10 and 12 November: US Treasury auctions of three-, ten- and thirty-year debt will help show the compensation investors require at different maturities. Strong demand alone does not demonstrate that every company can borrow on equivalent terms.
12–13 November: the next EIA Brent update and US October producer prices will add information about fuel and business expenses. The question is whether cheaper crude reaches later stages of production and delivery.
8–9 December: the next scheduled Federal Reserve meeting will assess whether the higher rates set in September are sufficient. Price and employment figures published before then could change the present assessment in either direction.
Important. This is general market analysis, not a personal recommendation to buy or sell. Historical data and company results do not guarantee future returns. Forecasts and conditional scenarios may not materialise.
How is the history preserved and updated?
All five periods in this edition share one information date. Week means the latest 7 days, quarter means 90 days, and year means the trailing 12 months. The next dated edition will have a separate URL. This text keeps its date and assessment; later events are not silently inserted into an older edition. Longer periods assess new evidence alongside earlier developments without repeating every headline.